Source page — copy text into Substack/LinkedIn, upload the visuals. noindex · not public
Closelook@Global Stock Markets · Weekly Edition
Three Speeds — America's Tech at a Record, Europe Slides, Asia Splits on AI
The Nasdaq 100 made a record close, global tech took out its June high, and Taiwan and Japan's broad fund closed at records — while every mainland European market on the board fell, France, Spain and Austria by four to five percent, Switzerland and Britain with them, and India slid to its lowest close in a year. The dollar made its highest close of 2026 and the euro its lowest; the long bond made a new low every day of the week, and gold broke its first support. The world ex-US index lost its line again, and its lead over America for the year is down to six tenths of a point. America won a fourth week. This letter's read for the fourth quarter — stay home, because the AI trade lives in America and Asia — and TSMC's September sales next week are the first test of it.
Closelooknet is a reader-supported publication — to receive new posts and support the work, become a free or paid subscriber.
1 · This Week's Action
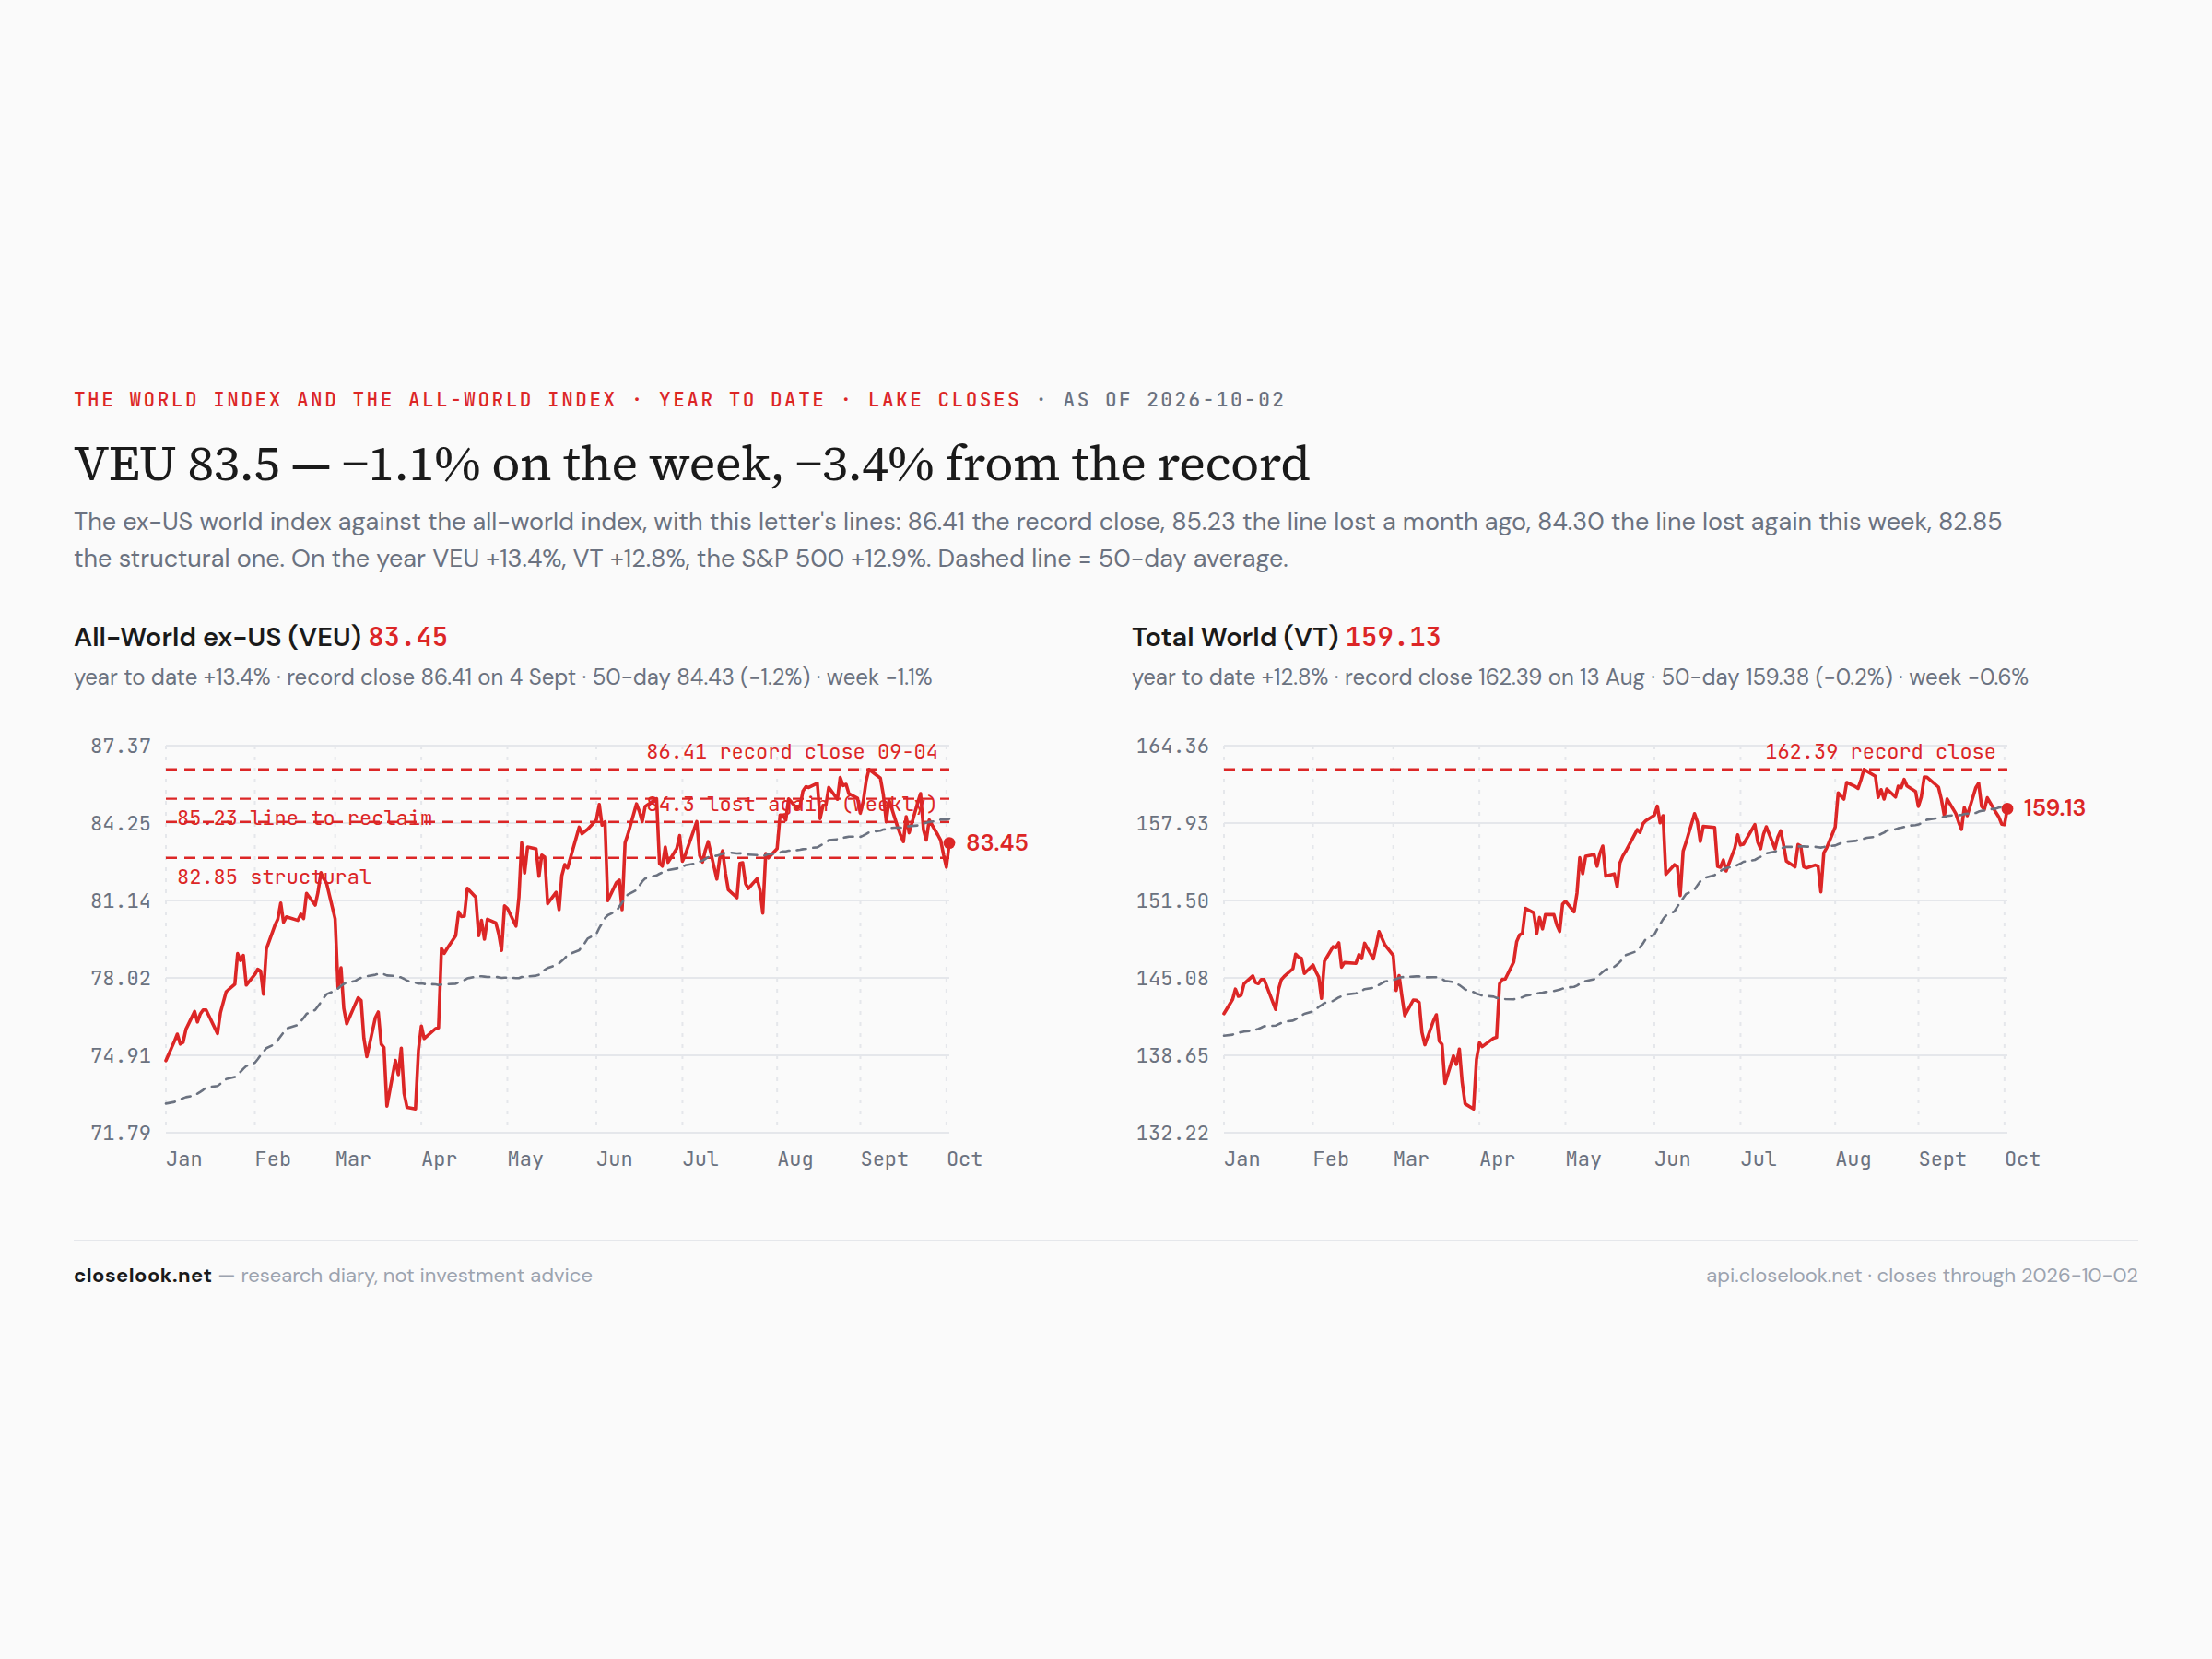
The global view. The ex-US world index closed the week at 83.45, down 1.10% — back under 84.30, the line it took back a week ago by eight cents. The path: Monday 83.77, Tuesday 83.56, Wednesday 82.97, Thursday 82.48 — a daily close under the 82.85 structural line, the first since July — and Friday 83.45, back above it for the weekly close. The index sits 3.4% under its September 4 record of 86.41. The all-world index closed 159.13, down 0.56%, 2.0% under its August high. The S&P 500 fund slipped 0.22%, 1.1% under its August high — but the Nasdaq 100 rose 1.01% to 30,916, a record close on Friday, and the fund that tracks it closed at a record too.
The year's order is close to turning. VEU +13.4% for 2026, the S&P fund +12.9%, VT +12.8% — the ex-US lead over America is 0.6 points, from 1.6 last week, 2.3 the week before, 3.7 and 4.5 before that. Four consecutive stay-home weeks. The Nasdaq 100 fund, the part of America that carries the AI trade, is +22.0% on the year. The house cointegration monitor still lists the VEU/SPY pair as breaking.
Three speeds — the week in one picture. The world did not move as one market this week; it moved at three speeds, and the dividing line was the AI trade. America's technology at records: the Nasdaq 100 at a record close, the US tech sector fund at a record 199.81 (+1.80%), global tech at a record 151.94 (+2.00%) — through the June high this letter has carried as a line since the summer. Asia's chip markets ahead: Taiwan's fund +1.35% to a record close of 116.33, the Taiex at a record 48,476; Korea's fund +2.51% to 191.88; Japan's fund +1.01% to a record close of 98.92. Europe and India behind: the Europe fund −2.54%, France −3.69%, Spain −4.72%, Austria −5.18%, Germany −2.27%, Switzerland −2.36%, Britain −2.41%; India −2.80%, with the Sensex at its lowest close in a year on Thursday.
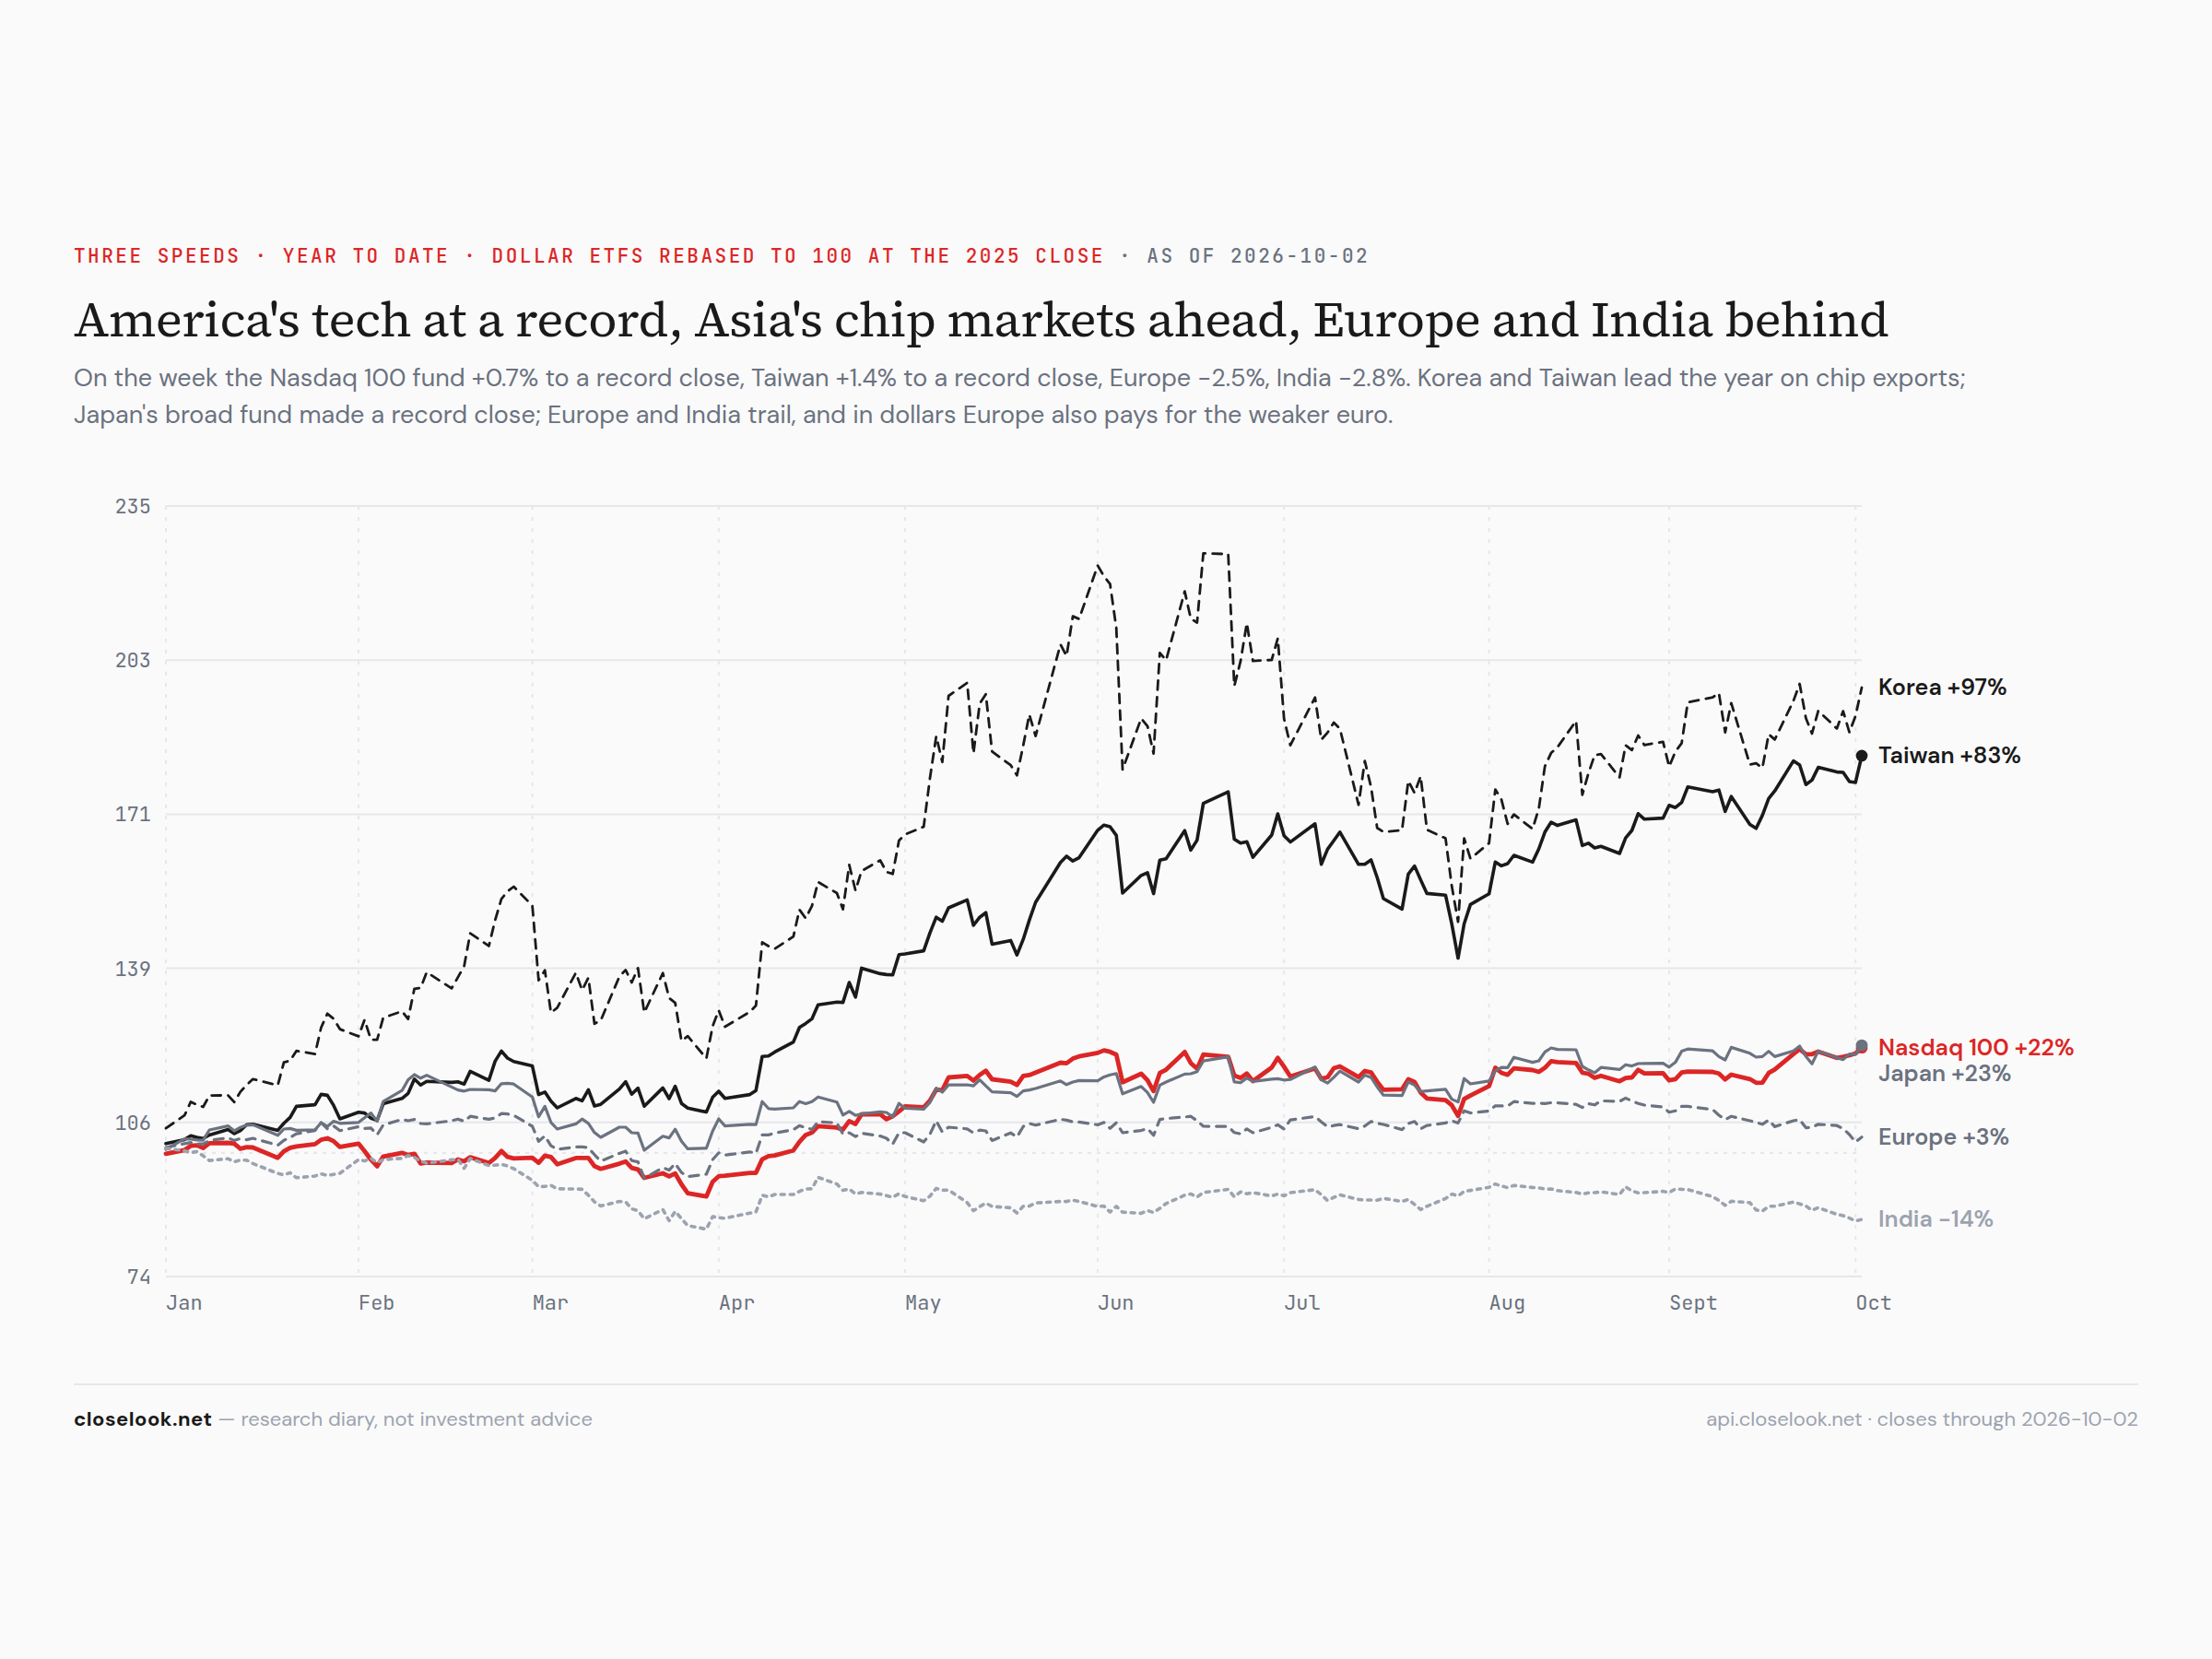
On the year the gap is the whole story: Korea +97%, Taiwan +83%, Japan +23%, the Nasdaq 100 +22% — against Europe +3% and India −14% in dollars. Four of the six legs in that chart carry the AI build-out — the chips, the chip equipment, the platforms that buy them. The two that do not are the two at the bottom.
The dollar — the high of the year, and the euro at its low. The third speed has a currency attached. The dollar fund rose 0.94% and made its highest close of 2026 on Thursday at 28.96; the dollar index closed Friday at 101.92, +0.94%. Against the euro the move was larger: EUR/USD fell 1.22% to 1.1253, after 1.1248 on Thursday — the euro's lowest close of the year — and is down 4.2% since January. A weaker euro is the European market's second cost this year: a dollar investor who owns Europe loses on the market and again on the translation, and a euro investor at home holds an asset that buys less of everything priced in dollars, from chips to oil.
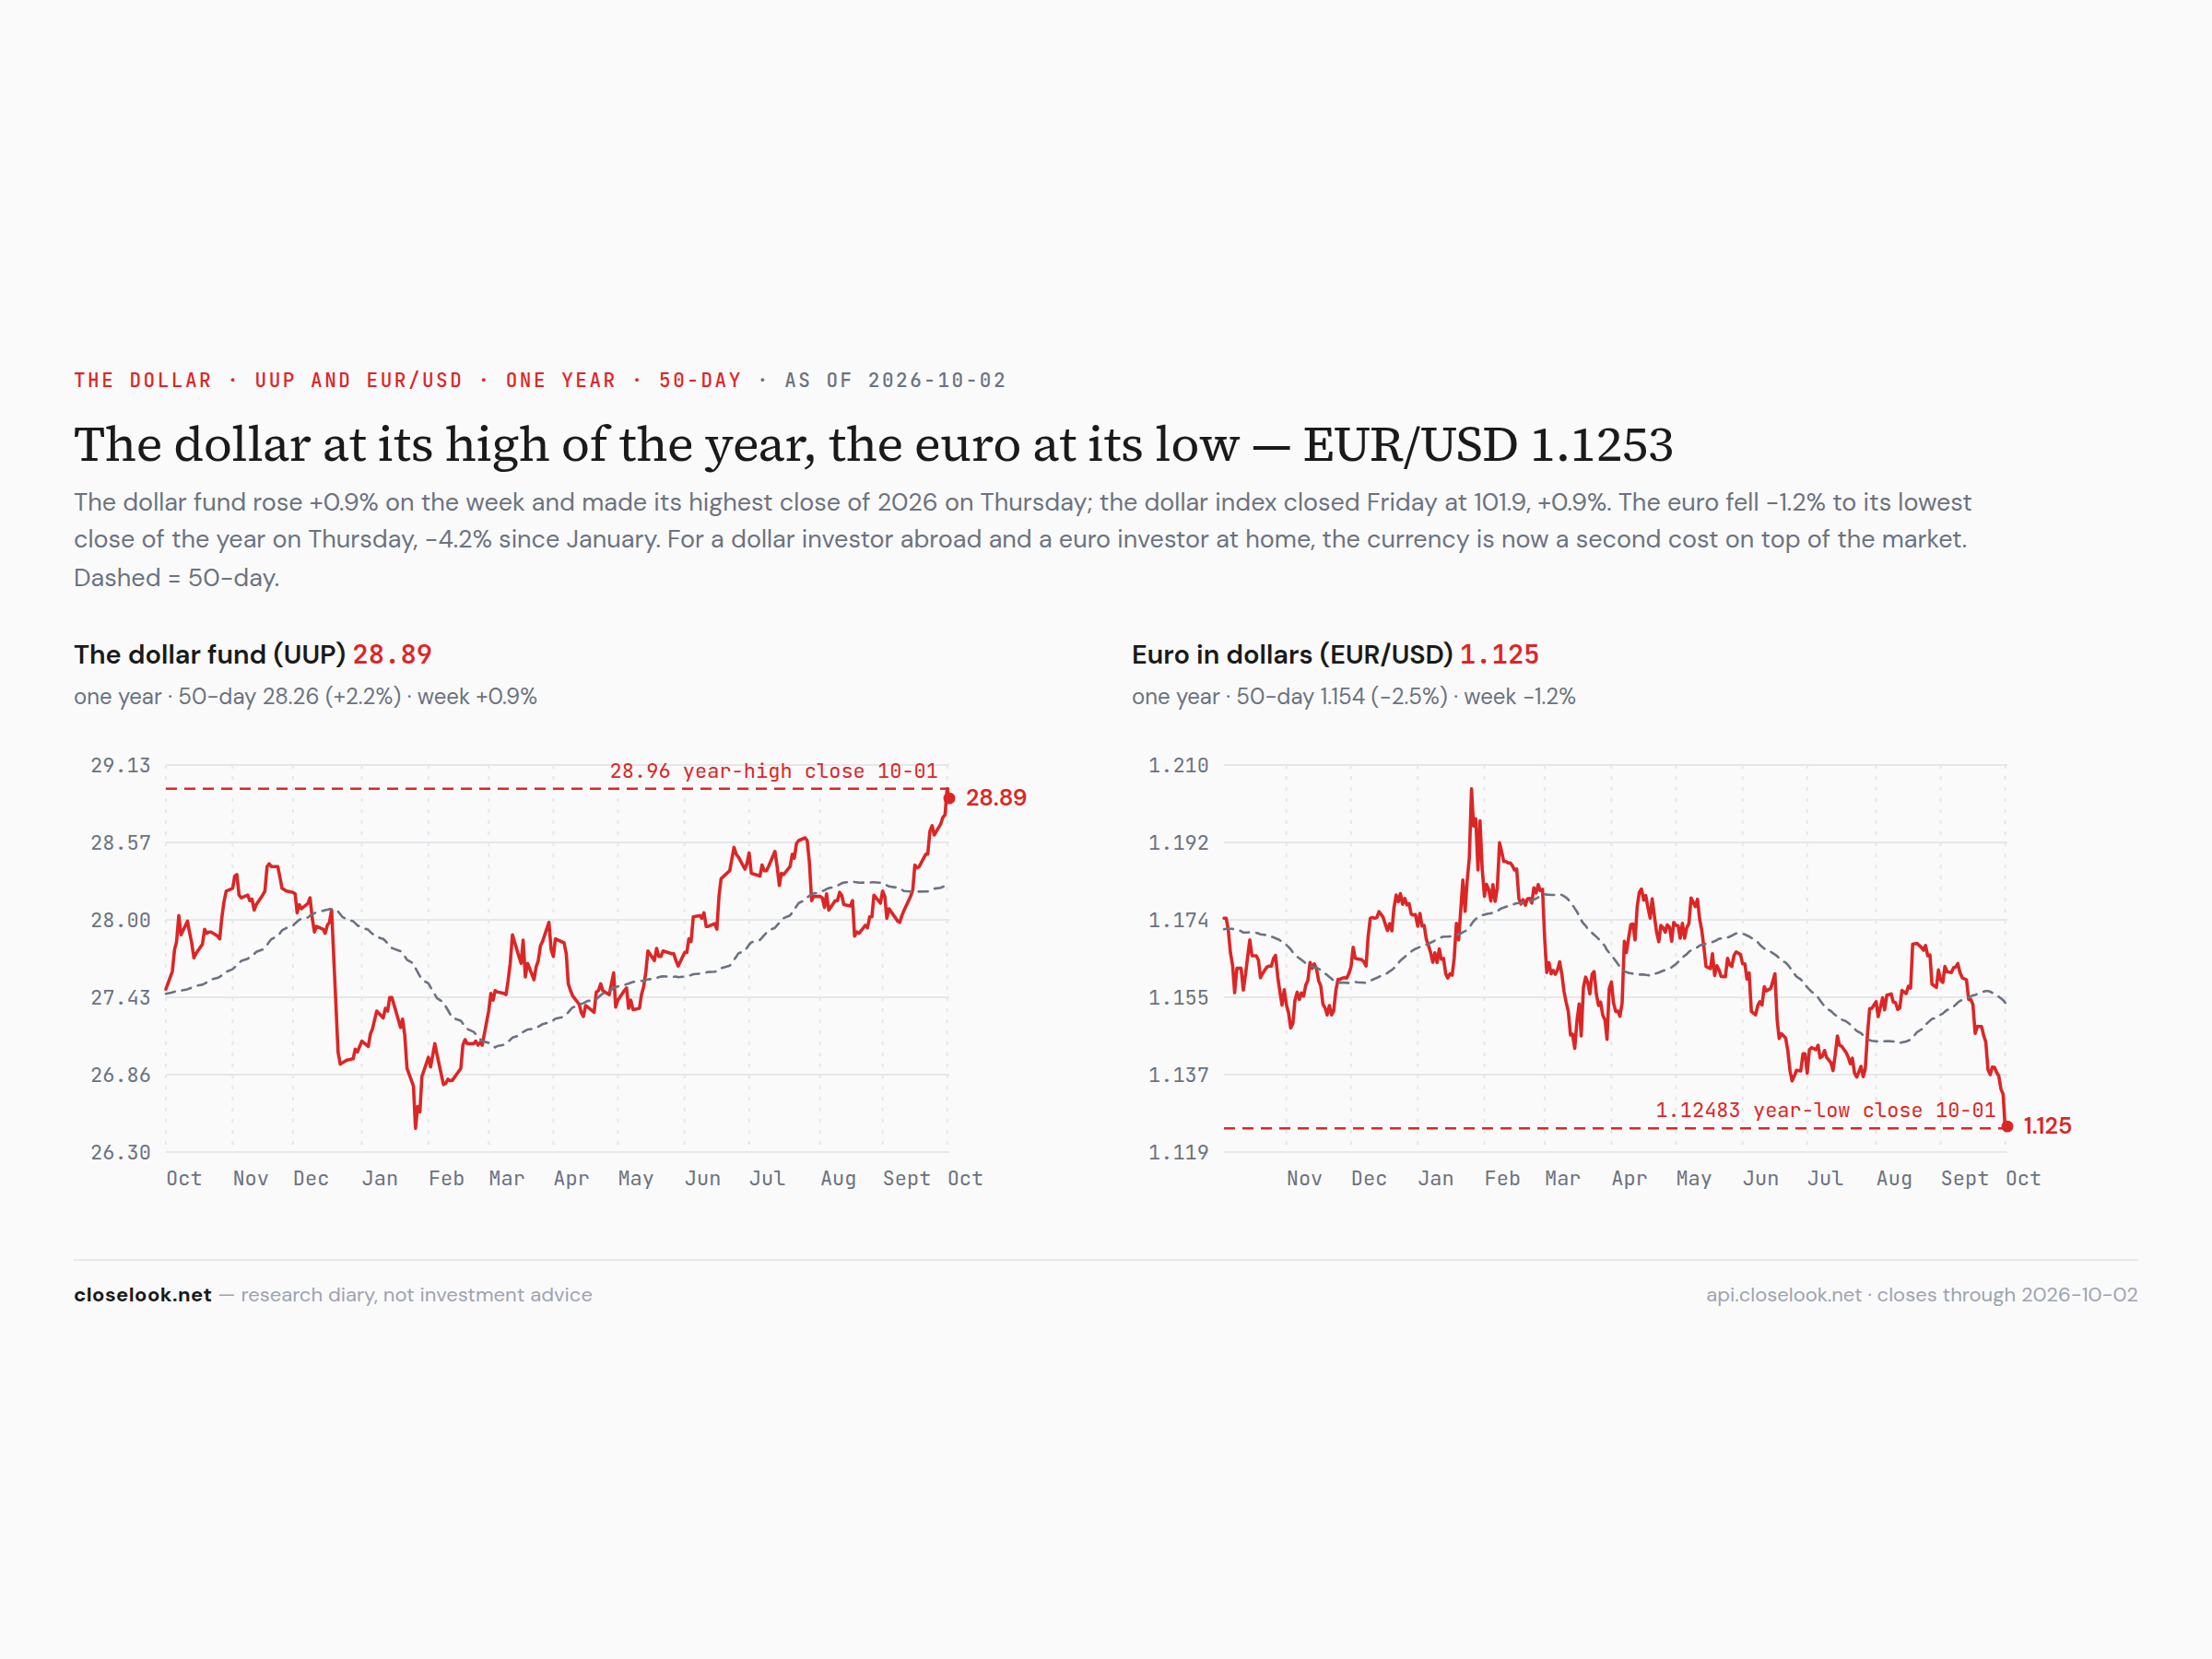
Why the dollar is strong — the same reason the yields are high. America's yields rise because its economy grows; Europe's rise because its sovereign credit is weaker and its growth is not there — Friday's Pulse set the two side by side, country by country. A rate rise for growth draws money in; a rate rise for credit pushes it out. The dollar is where that difference shows up first. This week it showed up in a jobs report that was weak — 29,000 jobs in September, with July and August cut by 60,000 — and a ten-year yield that ended the day higher anyway, at 5.28%, while the euro made its low. When weak American data cannot weaken the dollar, the market is telling you how it ranks the alternatives.
The regional board — five green of thirty-five. The top five: Brazil +3.72%, Korea +2.51%, Taiwan +1.35%, Japan +1.01%, EAFE growth +0.08%. The bottom: Austria −5.18%, Spain −4.72%, Argentina −4.60%, Poland −4.06%, France −3.69%, Hong Kong −3.10%, Mexico −3.07%. Last week twenty-two were green; this week five. The best-to-worst spread widened to 8.90 points from 7.38. A red board that widens is money leaving most places and concentrating in a few — and the few are the same chip corridor as last week, with Brazil the one commodity exception.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| EWZ | iShares MSCI Brazil | 38.19 | +3.72% | +0.26% | +10.92% | -0.42% | +20.21% |
| EWY | iShares MSCI South Korea | 191.88 | +2.51% | +7.28% | +6.52% | +56.17% | +97.37% |
| EWT | iShares MSCI Taiwan | 116.33 | +1.35% | +6.31% | +10.94% | +64.38% | +83.11% |
| EWJ | iShares MSCI Japan | 98.92 | +1.01% | +3.00% | +6.21% | +15.98% | +22.52% |
| EFG | iShares MSCI EAFE Growth | 121.08 | +0.08% | -1.45% | -2.06% | +7.31% | +6.29% |
| EWN | iShares MSCI Netherlands | 67.88 | -0.19% | -0.18% | +0.47% | +16.81% | +19.03% |
| EWA | iShares MSCI Australia | 28.32 | -0.39% | -5.69% | +0.82% | +0.78% | +8.13% |
| VT | Vanguard Total World Stock | 159.13 | -0.56% | -0.61% | +1.90% | +14.18% | +12.81% |
| IMTM | iShares MSCI Intl Momentum Fac | 53.05 | -0.64% | -0.82% | +1.01% | +8.71% | +10.59% |
| VEA | Vanguard FTSE Developed Market | 71.13 | -0.99% | -2.01% | +0.45% | +10.04% | +13.86% |
| VWO | Vanguard FTSE Emerging Markets | 59.56 | -1.00% | -1.99% | +0.88% | +10.67% | +10.79% |
| ENZL | iShares MSCI New Zealand | 44.98 | -1.01% | -6.10% | +0.09% | +6.21% | -0.64% |
| VEU | Vanguard FTSE All-World ex-US | 83.45 | -1.10% | -1.97% | +0.57% | +10.41% | +13.44% |
| VSS | Vanguard FTSE All-World ex-US | 155.65 | -1.11% | -2.18% | +0.35% | +6.11% | +8.60% |
| ASHR | Xtrackers Harvest CSI 300 Chin | 32.51 | -1.75% | -4.35% | -7.54% | -0.21% | -1.04% |
| ASEA | Global X - FTSE Southeast Asia | 20.95 | -1.97% | -3.50% | +6.08% | +7.82% | +14.30% |
| ENOR | iShares MSCI Norway | 35.3 | -2.00% | -4.75% | +10.31% | -4.23% | +22.65% |
| EFAV | iShares MSCI EAFE Min Vol Fact | 90.96 | -2.02% | -3.52% | +2.18% | -1.17% | +5.46% |
| FXI | iShares China Large-Cap | 33.19 | -2.27% | -6.61% | +4.01% | -6.66% | -13.32% |
| EWG | iShares MSCI Germany | 41.3 | -2.27% | -5.10% | -2.39% | +3.51% | -2.82% |
| EWL | iShares MSCI Switzerland | 59.23 | -2.36% | -5.82% | -7.42% | +0.47% | -1.22% |
| FEZ | EURO STOXX 50 | 67 | -2.40% | -4.50% | -2.88% | +7.29% | +4.05% |
| EWU | iShares MSCI United Kingdom | 46.18 | -2.41% | -4.23% | -2.08% | -0.11% | +5.00% |
| THD | iShares MSCI Thailand | 71.62 | -2.60% | -0.67% | +0.00% | +4.63% | +20.03% |
| EIDO | iShares MSCI Indonesia | 11.68 | -2.67% | -10.15% | +2.01% | -24.84% | -37.54% |
| EWM | iShares MSCI Malaysia | 27.06 | -2.77% | -3.67% | +0.33% | -4.52% | -1.10% |
| INDA | iShares MSCI India | 46.52 | -2.80% | -6.90% | -6.13% | -0.28% | -13.93% |
| EFV | iShares MSCI EAFE Value | 78.49 | -2.94% | -4.37% | +0.82% | +4.64% | +9.91% |
| EWW | iShares MSCI Mexico | 71.09 | -3.07% | -6.73% | -5.84% | -6.60% | +2.54% |
| EWH | iShares MSCI Hong Kong | 21.57 | -3.10% | -5.68% | +3.06% | -6.87% | +1.51% |
| EWQ | iShares MSCI France | 42.23 | -3.69% | -7.37% | -8.04% | -3.47% | -6.13% |
| EPOL | iShares MSCI Poland | 43.03 | -4.06% | -2.56% | +9.10% | +17.02% | +22.28% |
| ARGT | Global X - MSCI Argentina | 84.52 | -4.60% | -13.67% | -7.58% | -9.98% | -7.54% |
| EWP | iShares MSCI Spain | 58.31 | -4.72% | -5.85% | -2.26% | +6.29% | +8.16% |
| EWO | iShares MSCI Austria | 41.76 | -5.18% | -5.11% | -2.06% | +16.81% | +17.73% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The cross-asset backdrop — the dollar and the Nasdaq, nothing else. Four green of twelve: the dollar fund +0.94%, the Nasdaq top-30 fund +0.90%, the Nasdaq 100 +0.68%, the bitcoin fund +0.34%. The red eight: silver −5.85%, gold −3.37%, the long bond −2.32%, the belly −1.06%, copper miners −0.95%, oil −0.65%, the US top-20 fund −0.37%, the S&P −0.22%. Oil slipped as Washington offered barrels from its strategic reserve on Wednesday. In one line: the market bought the currency of the country that grows and the stocks of the companies that grow fastest inside it, and sold everything that stores value — metal, duration, even the top-20 megacap basket.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| UUP | Invesco DB US Dollar Index Bul | 28.89 | +0.94% | +2.56% | +1.94% | +3.70% | +6.88% |
| QTOP | iShares Nasdaq Top 30 Stocks | 39.78 | +0.90% | +7.75% | +6.95% | +30.78% | +24.48% |
| QQQ | Invesco QQQ | 749.58 | +0.68% | +5.69% | +5.19% | +28.14% | +22.02% |
| IBIT | iShares Bitcoin | 47.73 | +0.34% | +9.00% | +36.88% | +25.70% | -3.87% |
| SPY | S&P 500 | 769.64 | -0.22% | +0.59% | +3.34% | +17.35% | +12.86% |
| TOPT | iShares Top 20 U.S. Stocks | 35.21 | -0.37% | +4.26% | +7.74% | +22.05% | +12.74% |
| USO | United States Oil LP | 147.37 | -0.65% | +4.41% | +41.73% | +6.85% | +113.09% |
| COPX | Global X - Copper Miners | 85.91 | -0.95% | -4.44% | +12.08% | +11.77% | +19.67% |
| IEF | iShares 7-10 Year Treasury Bon | 89.05 | -1.06% | -3.40% | -5.39% | -6.52% | -7.39% |
| TLT | iShares 20+ Year Treasury Bond | 77.48 | -2.32% | -5.45% | -9.39% | -10.73% | -11.11% |
| GLD | Gold Shares | 380.14 | -3.37% | -5.62% | +0.53% | -11.47% | -4.08% |
| SLV | iShares Silver | 54.74 | -5.85% | -7.33% | -0.51% | -16.80% | -15.03% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The US sectors — three of eleven green. Technology +1.80%, energy +1.26%, utilities +0.81%. The bottom: health care −2.65%, financials −2.46%, communications −2.34%, materials −1.89%, staples −1.86%, real estate −1.80%. Communications fell with Meta's week after its agent rally; financials fell as the long end rose again. The equal-weight S&P fell 0.65% and small caps 0.16%. The index was held up by one sector, and that sector made a record.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| XLK | Technology | 199.81 | +1.80% | +8.83% | +10.64% | +46.93% | +38.79% |
| XLE | Energy | 62.82 | +1.26% | -3.50% | +18.04% | +6.03% | +40.51% |
| XLU | Utilities | 39.83 | +0.81% | -6.66% | -12.96% | -14.05% | -6.70% |
| XLI | Industrial | 169.95 | -0.28% | -1.64% | -7.59% | +3.77% | +9.56% |
| XLY | Consumer Discretionary | 110.04 | -0.47% | -4.20% | -6.05% | +1.75% | -7.85% |
| XLRE | Real Estate | 40.81 | -1.80% | -6.68% | -8.66% | -1.92% | +1.14% |
| XLP | Consumer Staples | 80.53 | -1.86% | -5.85% | -5.25% | -1.66% | +3.67% |
| XLB | Materials | 48.86 | -1.89% | -7.72% | -6.06% | -3.07% | +7.74% |
| XLC | Communication Services | 110.32 | -2.34% | -1.87% | +0.66% | -1.24% | -6.29% |
| XLF | Financial | 53.49 | -2.46% | -7.23% | -3.83% | +8.00% | -2.34% |
| XLV | Health Care | 166.18 | -2.65% | -3.91% | +1.49% | +13.19% | +7.35% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The tech ETFs — fifteen of twenty-one green. The chip majors +3.96%, cybersecurity +3.71%, the WisdomTree AI fund +3.19%, the fabless vehicle +2.82%, the equal-weight semis +2.68%, software +2.28%. The red six: digital transformation −6.37%, fintech −4.02%, uranium −2.87%, data centers −2.05%, defense tech −2.00%, ARK −1.04%. The memory vehicle DRAM was flat (−0.21%) after Micron's record quarter on Wednesday — the numbers were superb and the stocks did not move, a market that had already paid for them. Software rose with the chips for a second week: both halves of the stack bid at once.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| SMH | VanEck Semiconductor | 630.6 | +3.96% | +14.55% | +6.47% | +60.74% | +75.10% |
| CIBR | First Nasdaq Cybersecurity | 104.7 | +3.71% | +11.93% | +15.47% | +63.11% | +46.54% |
| WTAI | WisdomTree Artificial Intellig | 45.35 | +3.19% | +13.83% | +6.53% | +56.81% | +55.63% |
| SMHX | VanEck Fabless Semiconductor | 63.22 | +2.82% | +15.18% | +7.79% | +65.88% | +66.24% |
| XSD | S&P Semiconductor | 555.21 | +2.68% | +16.37% | -0.12% | +64.94% | +72.64% |
| IGV | iShares Expanded Tech-Software | 108.43 | +2.28% | +4.84% | +15.88% | +34.96% | +2.59% |
| GRID | First NASDAQ Clean Edge Smart | 182.91 | +1.86% | +4.20% | -0.68% | +10.25% | +19.53% |
| BOTZ | Global X - Robotics & Artifici | 36.03 | +1.78% | +2.39% | -3.64% | +7.87% | -0.55% |
| QTUM | Defiance Quantum | 156.06 | +1.52% | +7.84% | +0.68% | +41.92% | +42.31% |
| CLOU | Global X - Cloud Computing | 28.81 | +1.48% | +4.99% | +24.07% | +44.85% | +27.37% |
| SNSR | Global X - Internet of Things | 50.28 | +1.41% | +7.45% | +3.84% | +33.73% | +36.04% |
| ESPO | VanEck Video Gaming and eSport | 97.55 | +1.28% | +1.39% | +6.11% | +8.05% | -5.85% |
| AIQ | Global X - Artificial Intellig | 66.23 | +0.39% | +4.99% | +7.08% | +40.11% | +30.22% |
| LIT | Global X - Lithium & Battery T | 69.28 | +0.38% | -6.71% | -9.47% | -6.59% | +6.81% |
| FDN | First Dow Jones Internet Index | 291.75 | +0.05% | +1.52% | +9.25% | +22.05% | +8.38% |
| ARKK | ARK Innovation | 89.83 | -1.04% | +7.72% | +10.56% | +31.02% | +16.78% |
| SHLD | Global X - Defense Tech | 60.23 | -2.00% | -4.56% | -5.83% | -18.56% | -7.04% |
| DTCR | Global X - Data Center & Digit | 27.27 | -2.05% | -0.62% | -4.18% | +10.85% | +29.24% |
| NLR | VanEck Uranium and Nuclear | 102.74 | -2.87% | -12.21% | -10.61% | -23.14% | -17.28% |
| FINX | Global X - FinTech | 24.34 | -4.02% | -9.19% | -4.81% | +5.96% | -17.30% |
| DAPP | VanEck Digital Transformation | 19.11 | -6.37% | +1.49% | +3.41% | +27.48% | +15.61% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
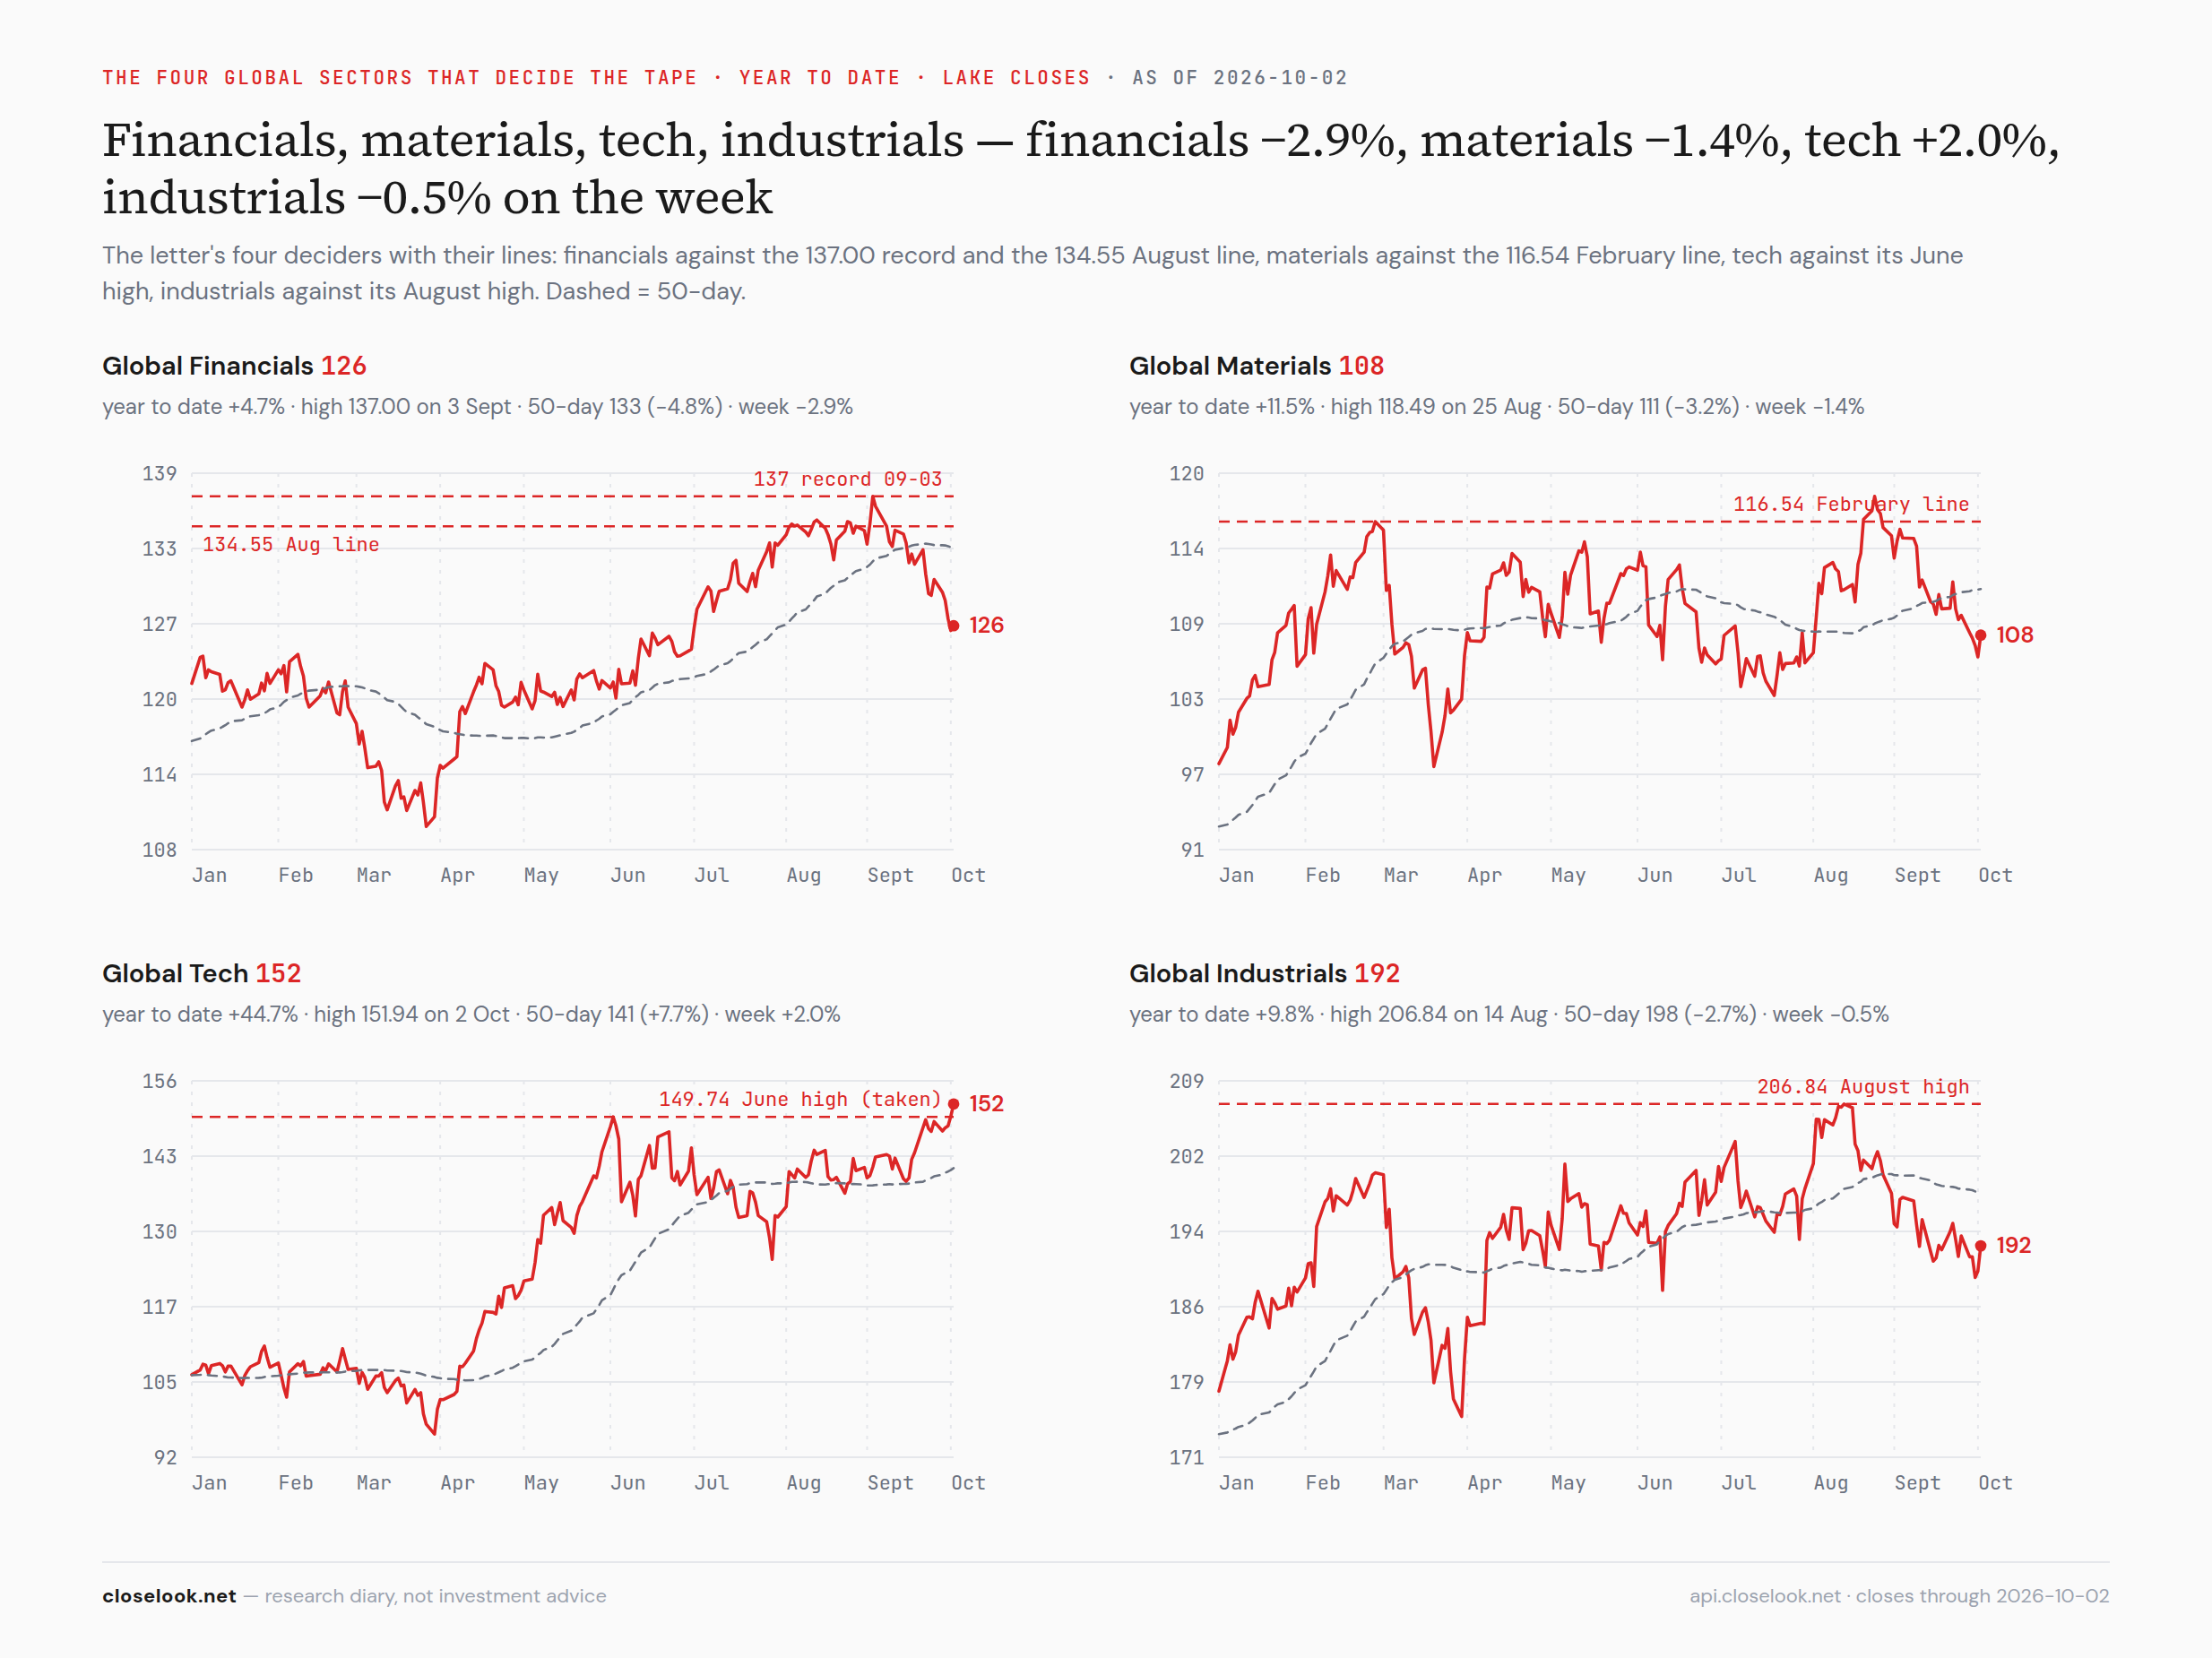
The global sectors — tech at a record, the rest red. Three of eleven green: technology +2.00% to 151.94 — a record close, through the 149.74 June high — energy +0.78%, utilities +0.16%. The bottom: health care −2.91%, financials −2.90% to 126.43, staples −2.21%, communications −2.12%, REITs −1.61%, materials −1.40% to 107.80. Financials spent a fourth week under the 134.55 August line, materials a sixth under the February line. One global sector at a record, the cyclical and defensive benches both lower: that is concentration, not breadth.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| IXN | iShares Global Tech | 151.94 | +2.00% | +8.74% | +11.31% | +49.50% | +44.70% |
| IXC | iShares Global Energy | 57.89 | +0.78% | -2.21% | +17.54% | +2.50% | +38.06% |
| JXI | iShares Global Utilities | 77.46 | +0.16% | -4.23% | -9.41% | -11.52% | -1.51% |
| EXI | iShares Global Industrials | 192.47 | -0.52% | -0.99% | -3.97% | +4.38% | +9.77% |
| VT | Vanguard Total World Stock | 159.13 | -0.56% | -0.61% | +1.90% | +14.18% | +12.81% |
| RXI | iShares Global Consumer Discre | 185.43 | -1.01% | -5.29% | -4.97% | -0.38% | -9.66% |
| MXI | iShares Global Materials | 107.8 | -1.40% | -6.29% | +0.02% | +0.41% | +11.55% |
| REET | iShares Global REIT | 25.64 | -1.61% | -6.18% | -8.36% | +0.27% | +2.77% |
| IXP | iShares Global Comm Services | 117.83 | -2.12% | +0.42% | +2.78% | +2.46% | -2.80% |
| KXI | iShares Global Consumer Staple | 65.15 | -2.21% | -4.97% | -5.69% | -3.19% | +0.77% |
| IXG | iShares Global Financials | 126.43 | -2.90% | -6.17% | -1.05% | +10.14% | +4.67% |
| IXJ | iShares Global Healthcare | 100.86 | -2.91% | -4.58% | -0.67% | +7.17% | +3.55% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
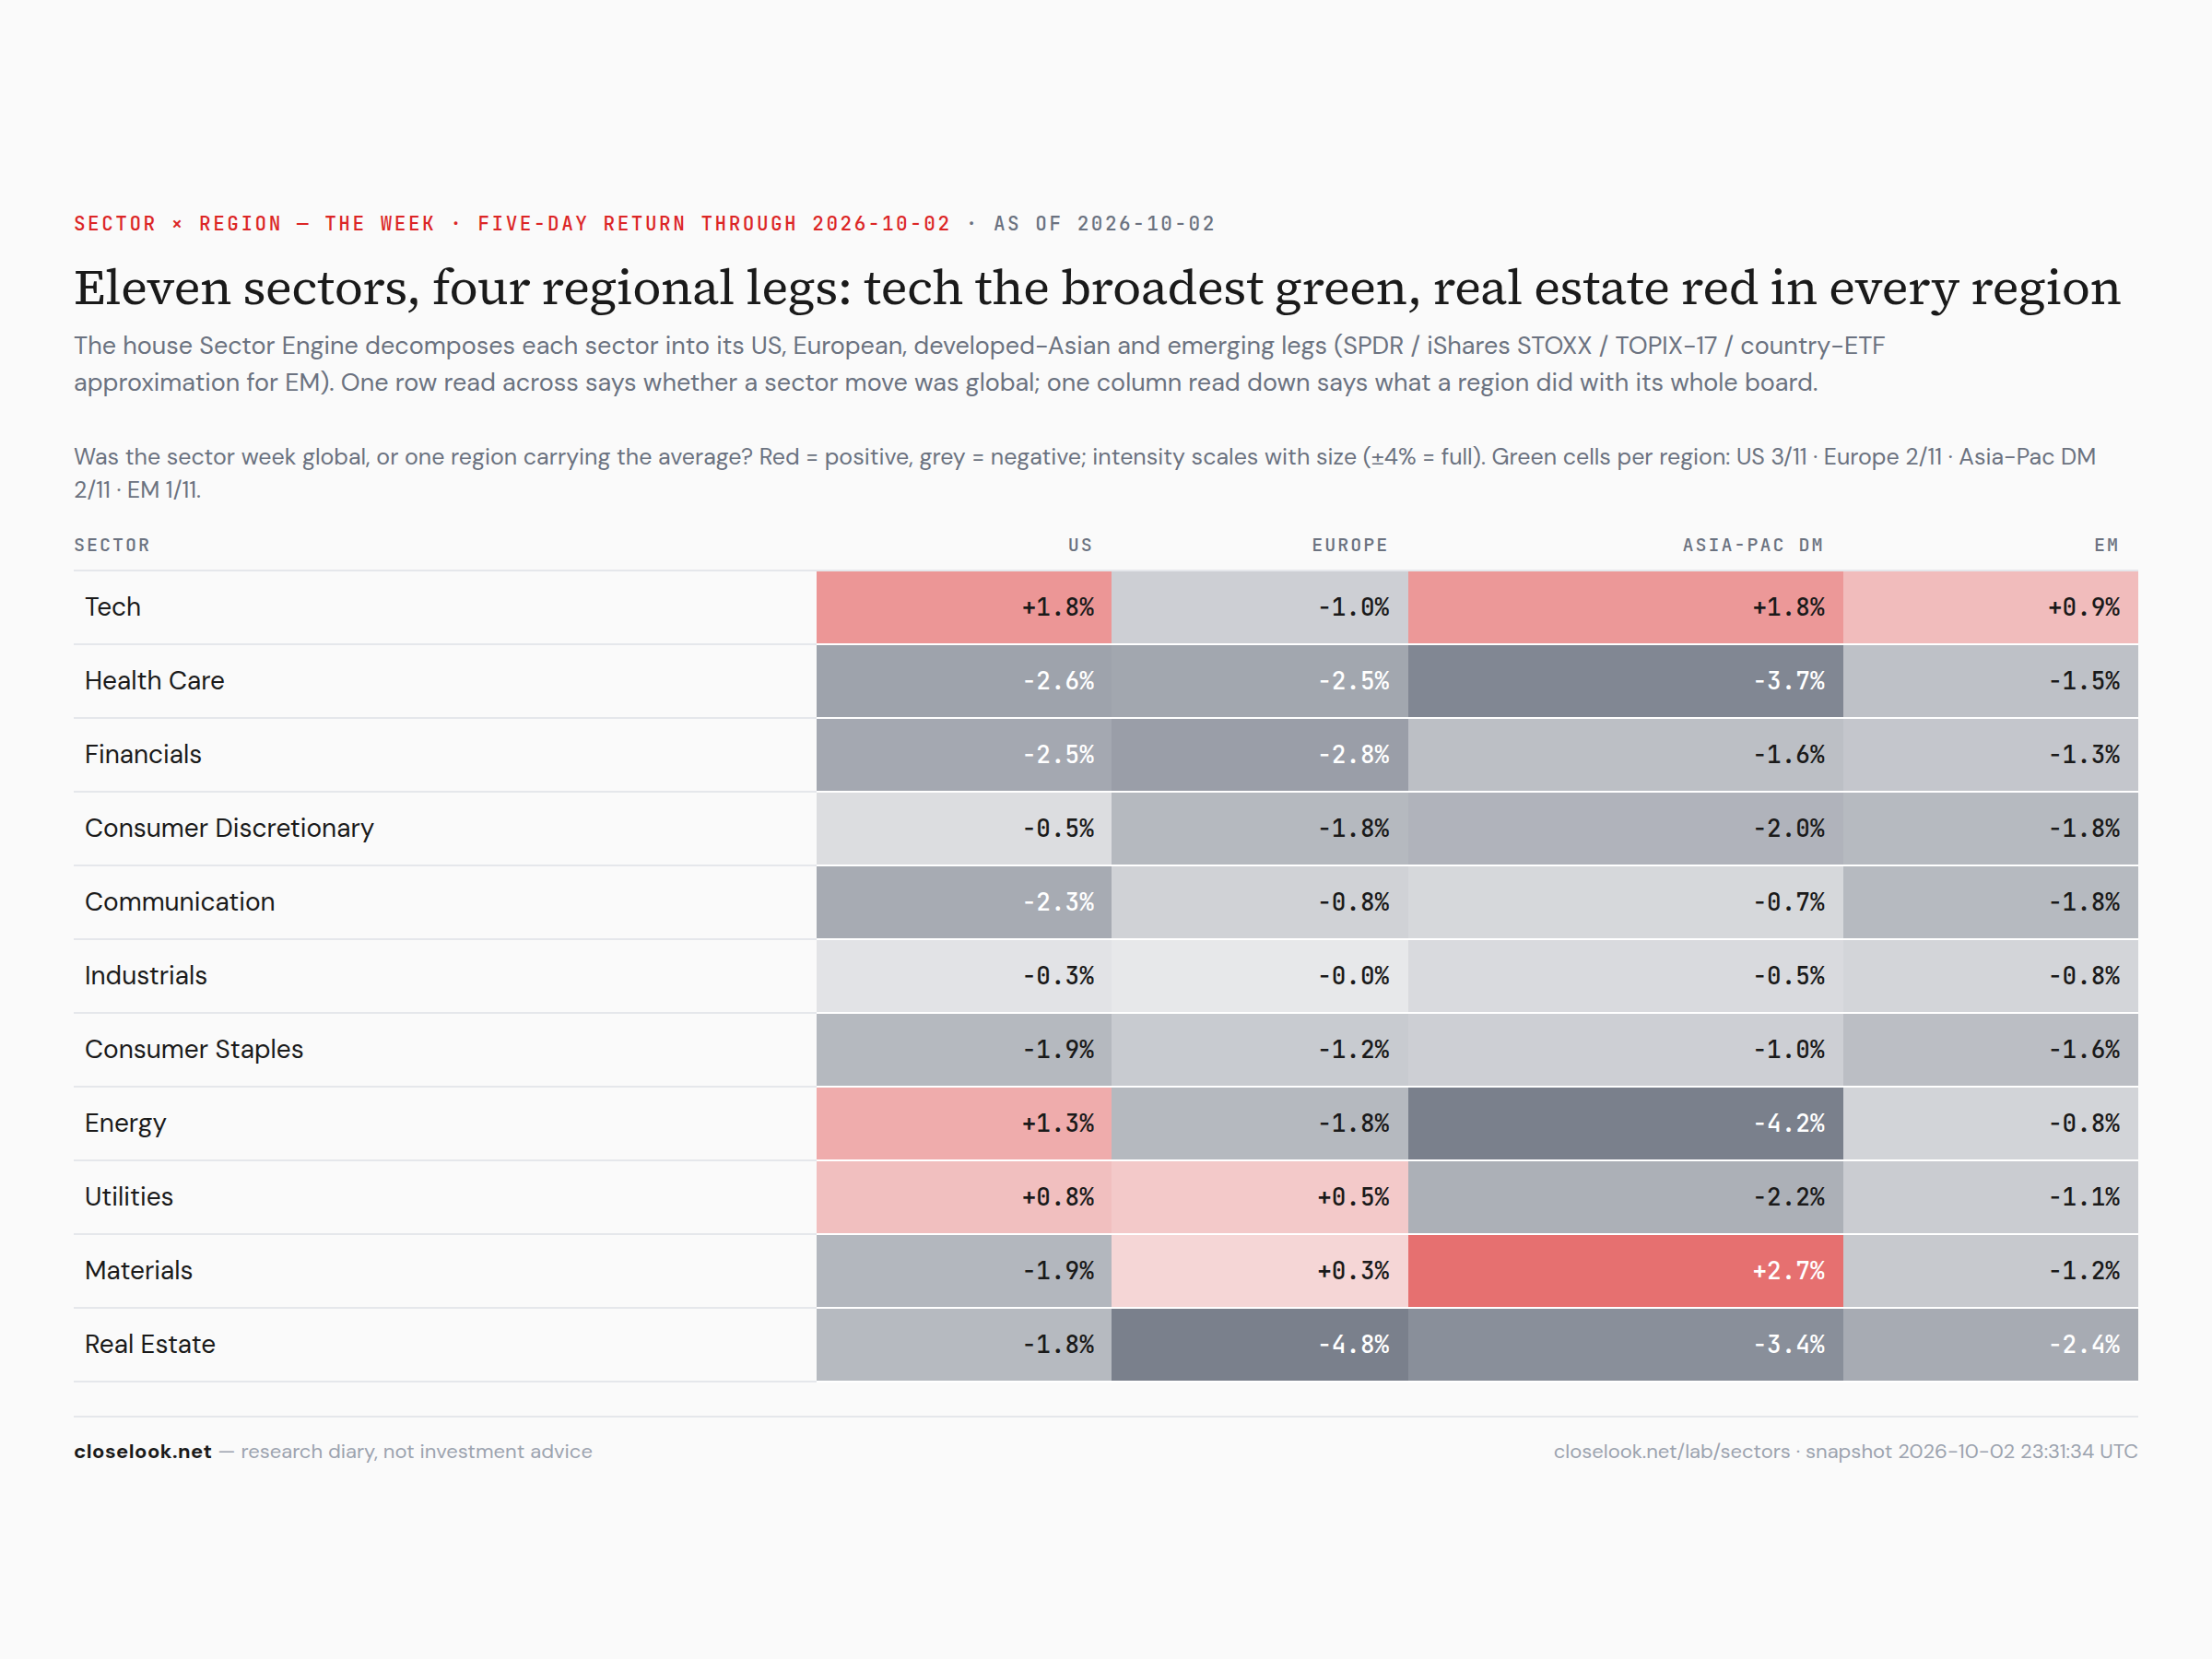
Was the sector week global, or one region carrying it? The house Sector Engine decomposes each sector into four regional legs. Technology rose in three of the four: the US +1.8%, developed Asia +1.8%, emerging markets +0.9% — and fell in Europe, −1.0%. Real estate fell in every region, Europe worst at −4.8%; health care fell in all four. The US-minus-Europe spread was positive in eight sectors of eleven, technology +2.8 points, real estate +2.9, energy +3.1. Last week tech was green in every region. This week Europe's leg broke away — the same week its sovereign spreads widened.
The Global Compass
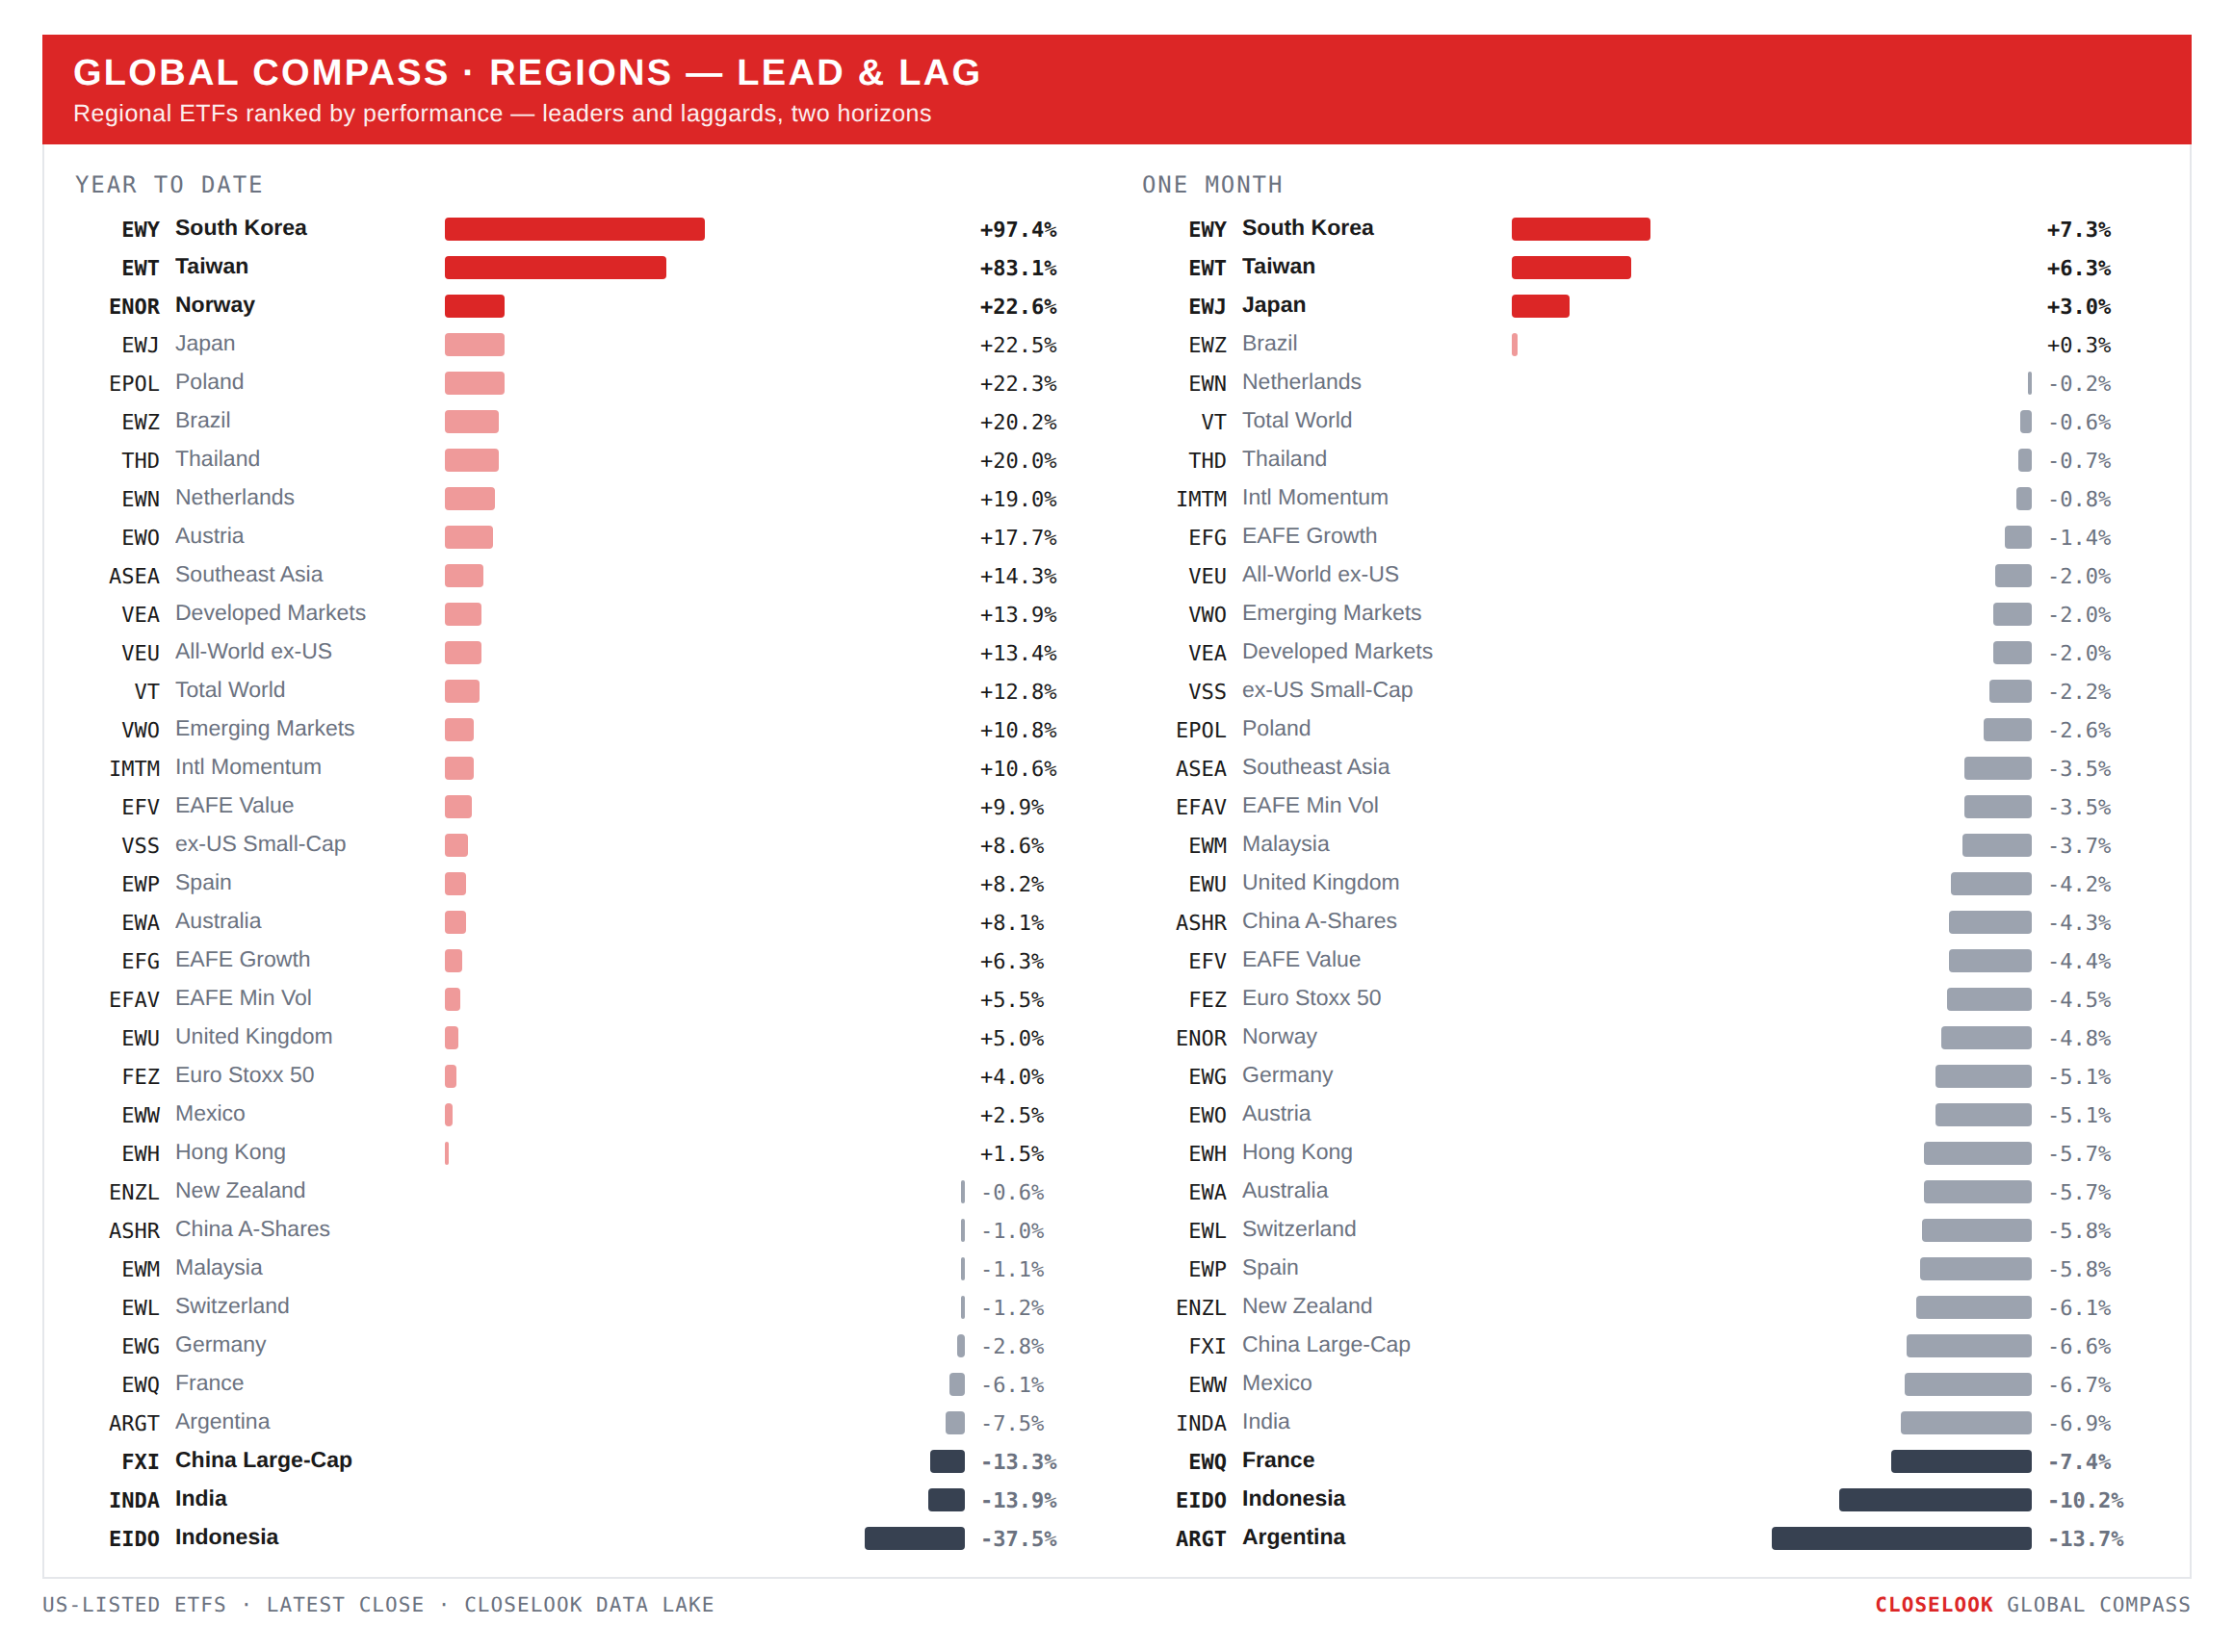
Regions: developed and emerging tied; the corridor beat both. VEA −0.99% against VWO −1.00% — a dead heat on the broad wrappers, both red, with the chip exporters at the top and Mexico, Hong Kong, India and Indonesia at the bottom. China's large caps fell 2.27% and its A-shares 1.75% into Golden Week, which shut the mainland from Thursday.
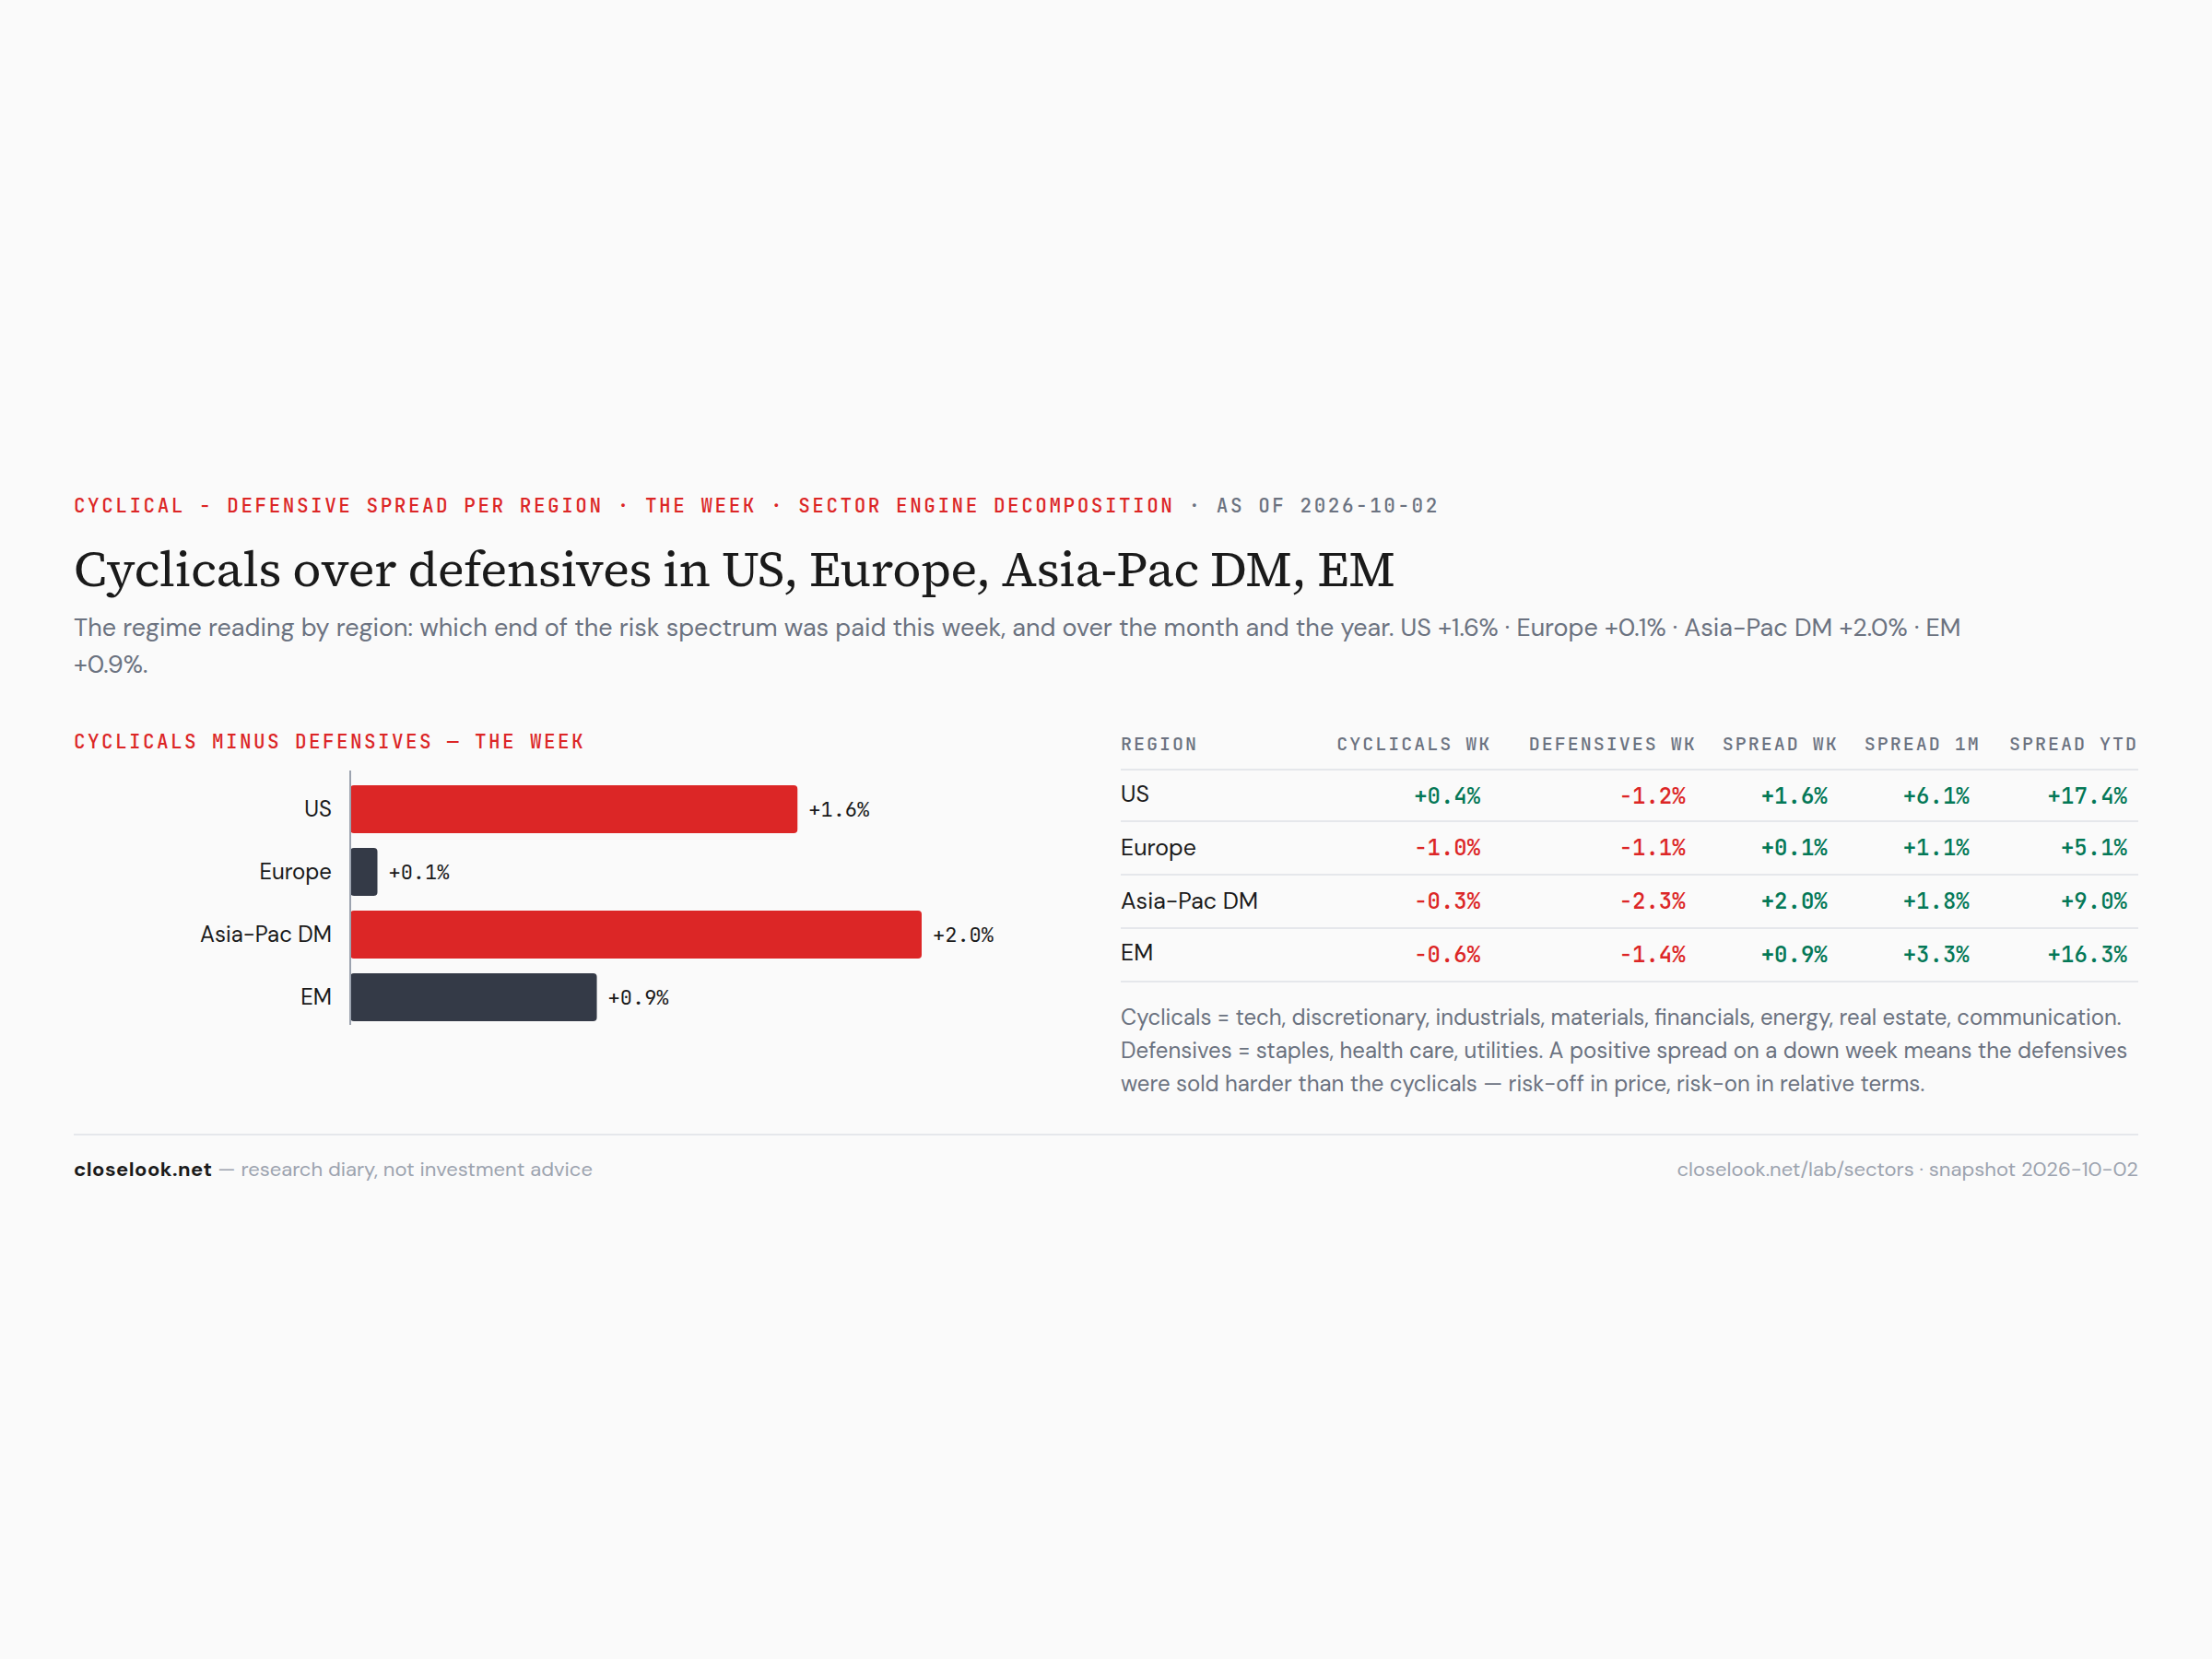
Sectors: cyclicals over defensives everywhere except Europe. The engine's cyclical-minus-defensive spread was +1.6 points in the US, +2.0 in developed Asia, +0.9 in emerging markets — and +0.1 in Europe, where cyclicals and defensives fell together. On the year the US spread is +17.4 points and Europe's +5.1. Europe did not rotate this week; it de-rated across the board.
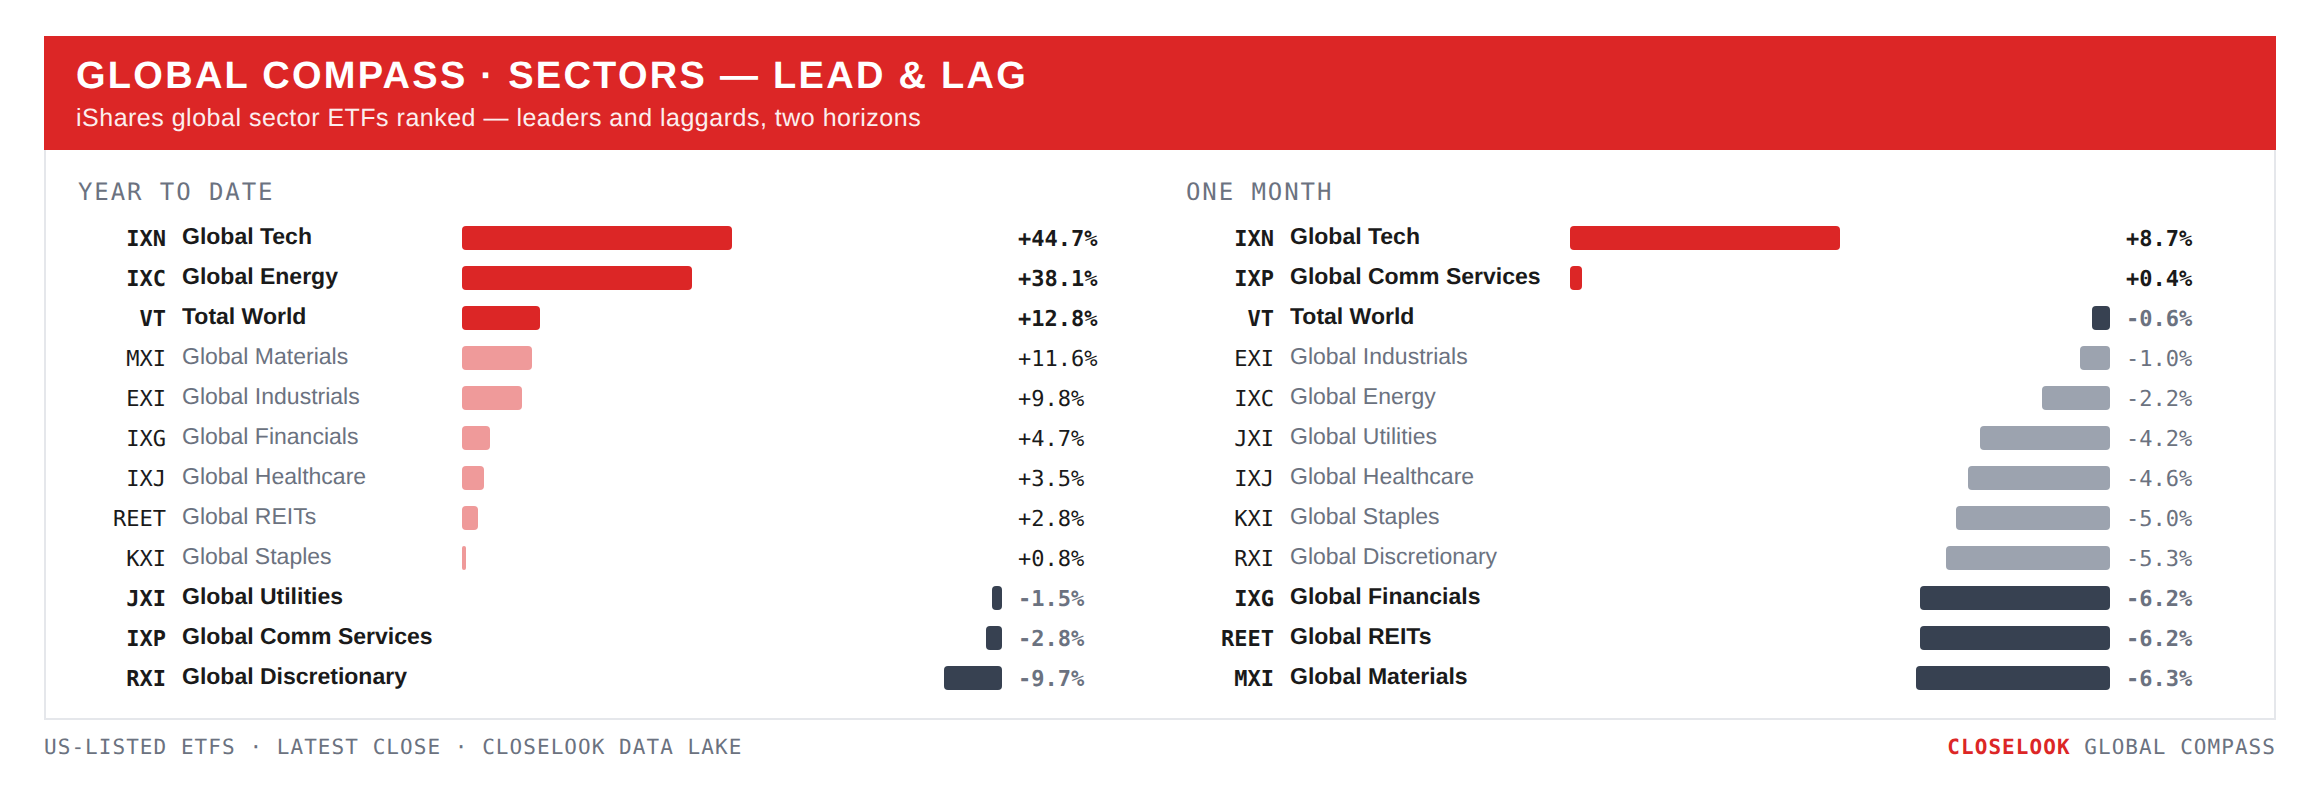
Sectors: the leaders' bench, at the new distances. Technology 151.94, a record, after closing the 0.5% gap in two sessions. Industrials 192.47, 6.9% under August. Financials 126.43, 7.7% under its September 3 record, four weeks under its line. Materials 107.80, 9.0% under its August 25 record, six weeks under the February line. Last week the bench split; this week the split widened: one sector at the top, the commodity and credit pair drifting further down.
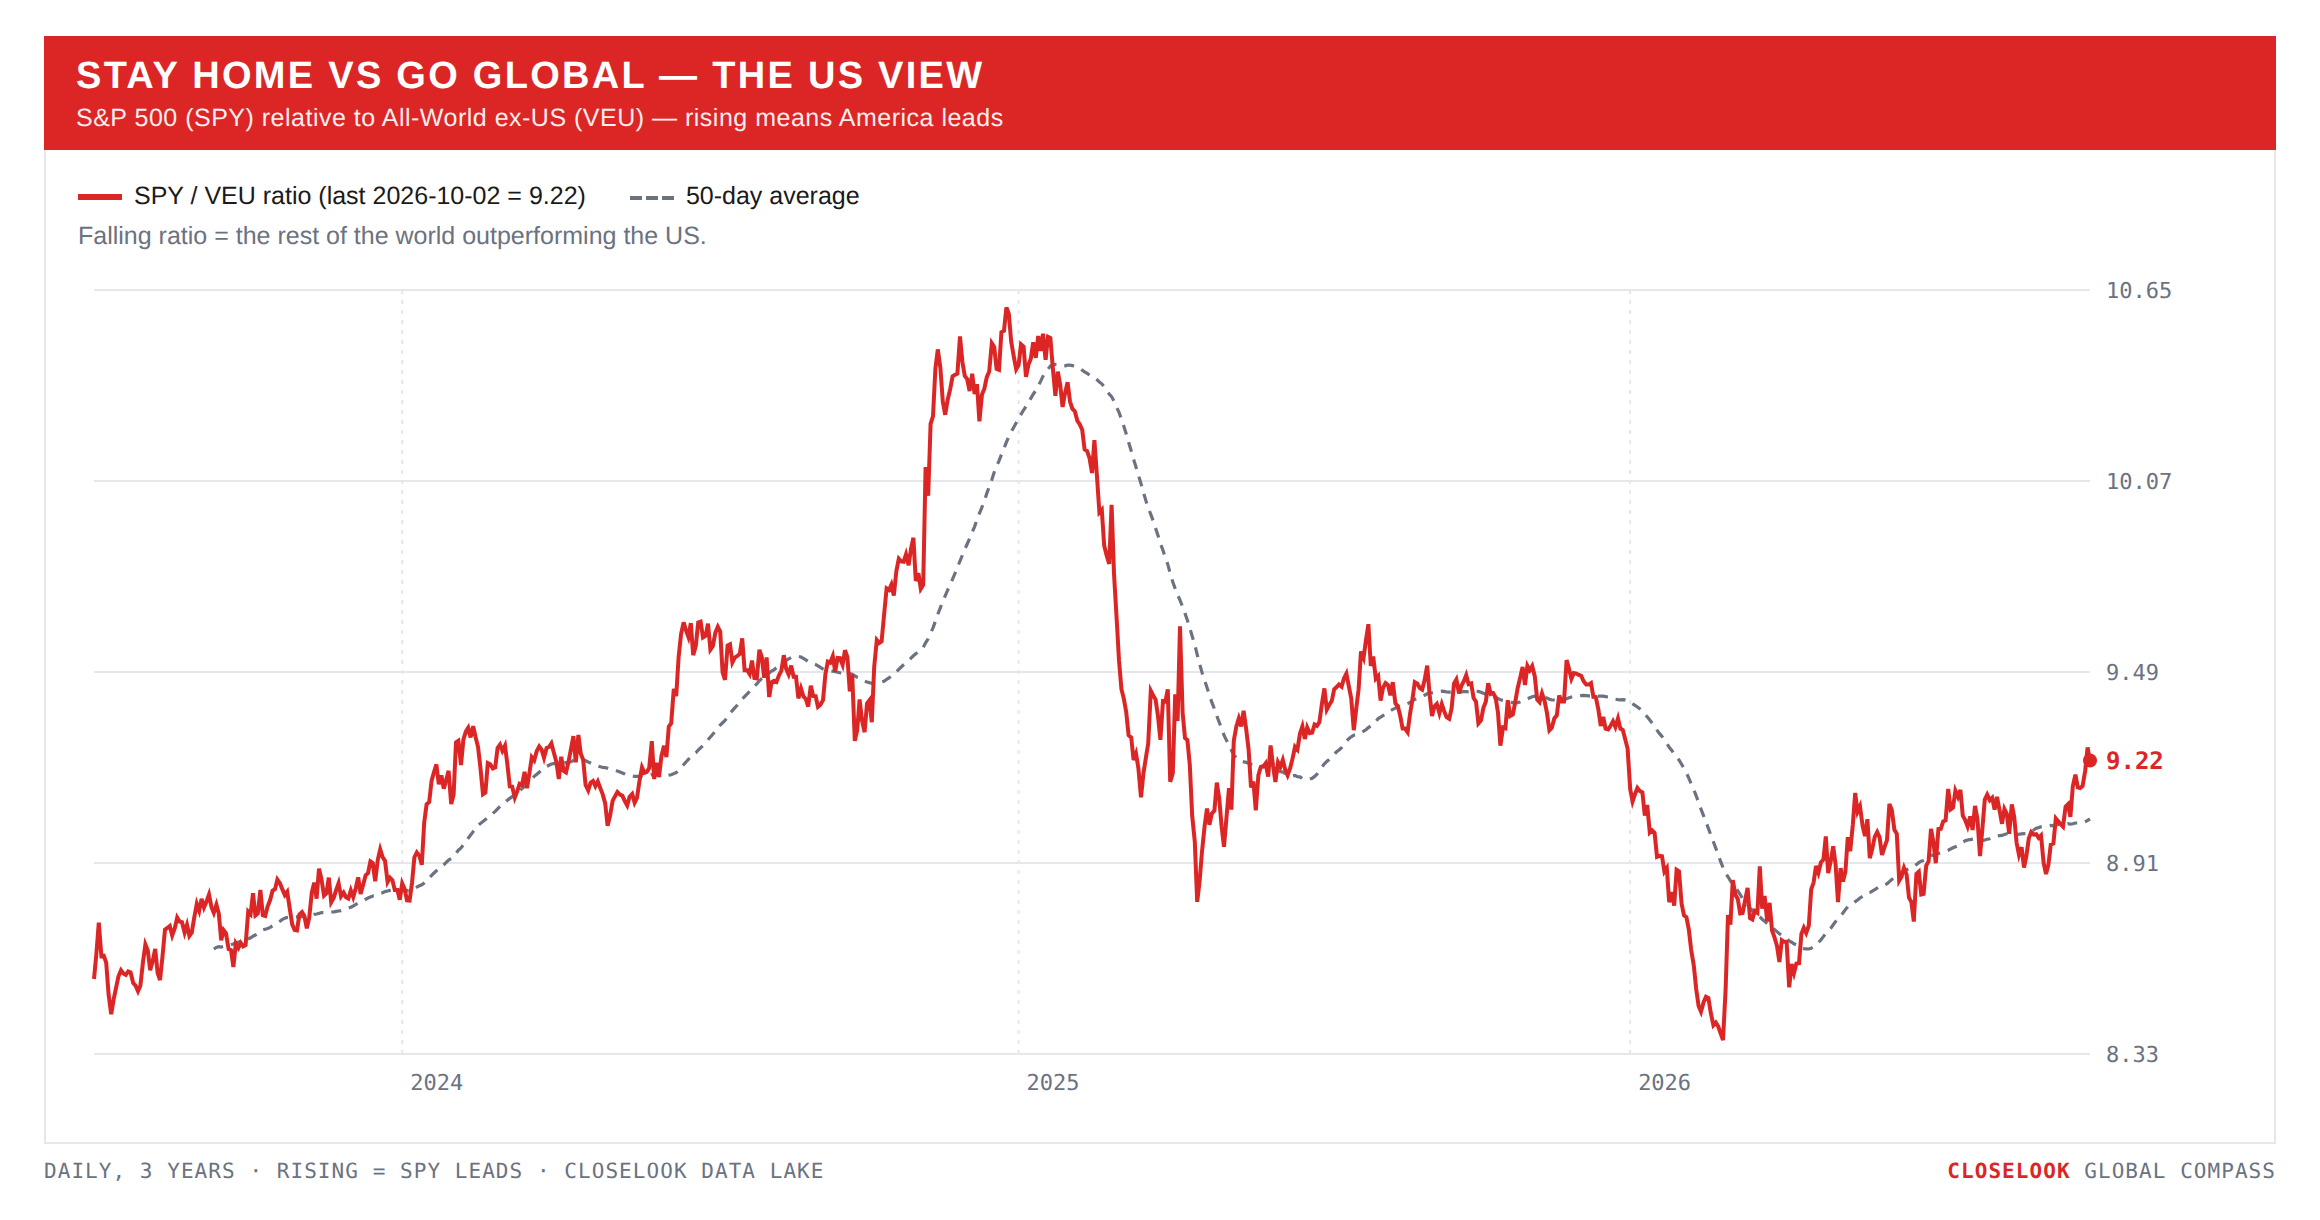
Stay home vs go global — the US view. America won a fourth week: SPY −0.22%, VT −0.56%, VEU −1.10%. The year still reads ex-US first, by a hair: +13.4% against +12.9% against +12.8%. In four weeks the lead has gone from 4.5 points to 0.6. On the current pace the year's order flips within a fortnight, and the line on the chart below says the same thing more quietly: the SPY/VEU ratio has turned up from its September low.
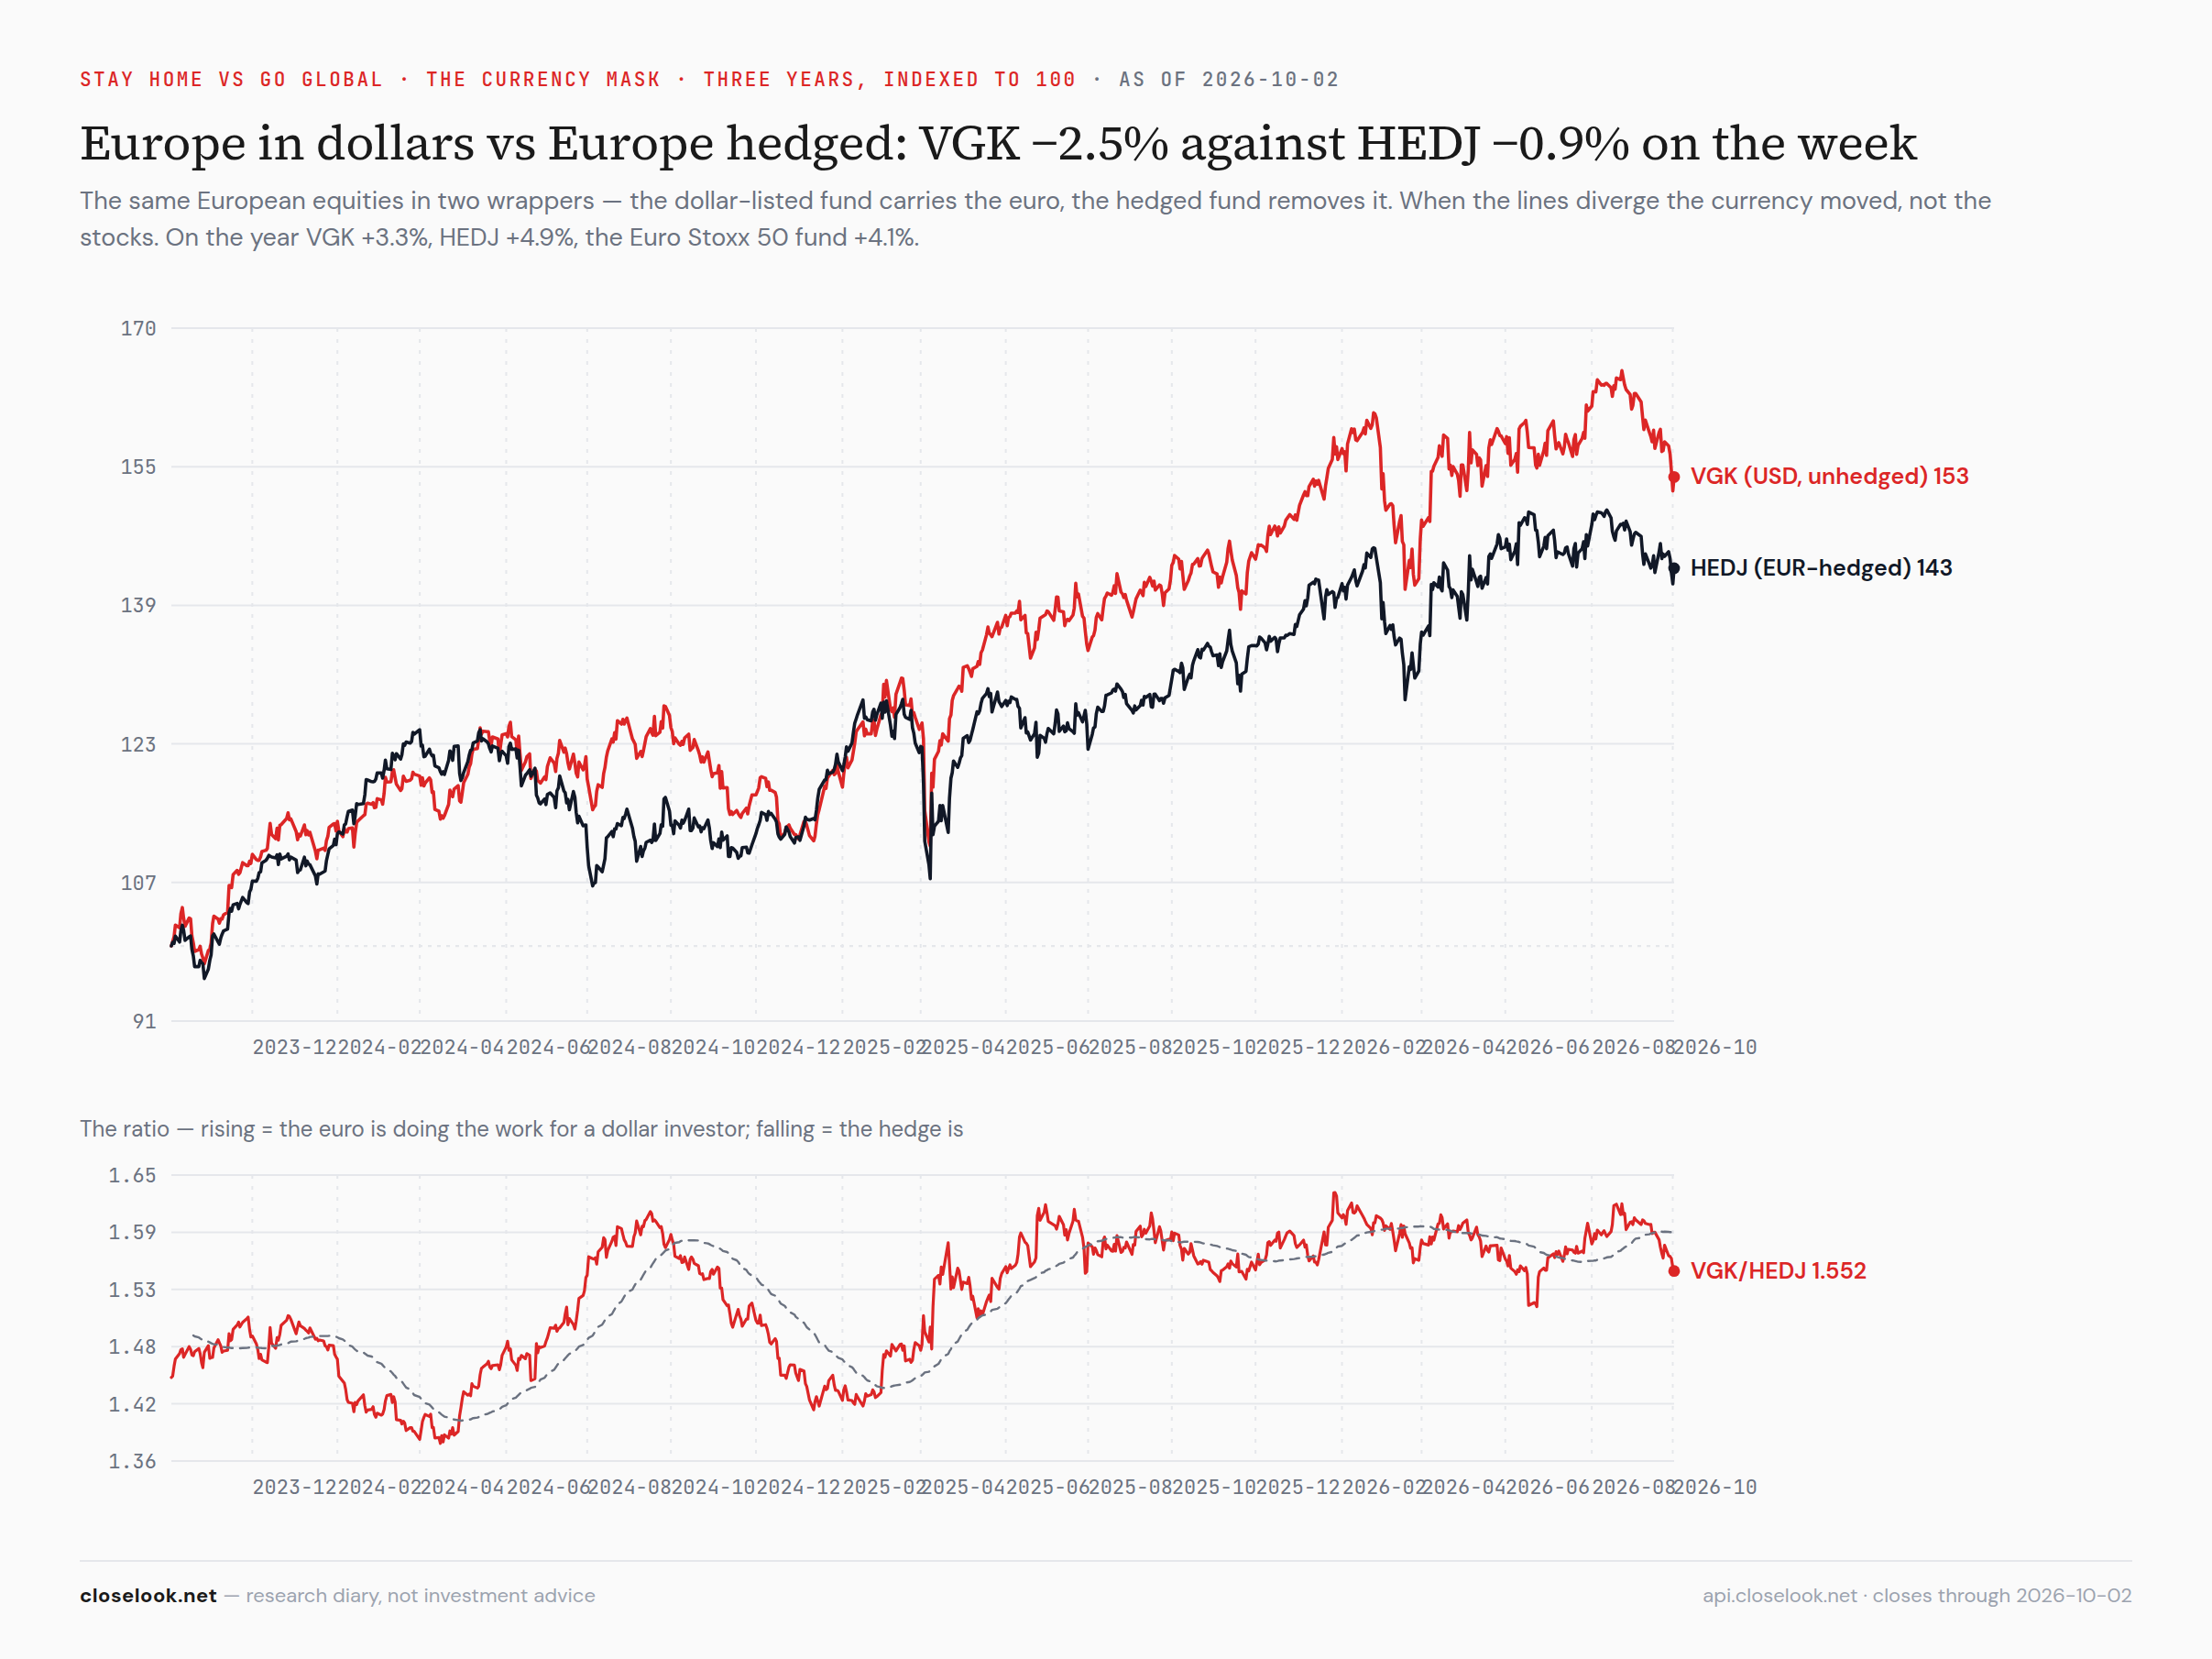
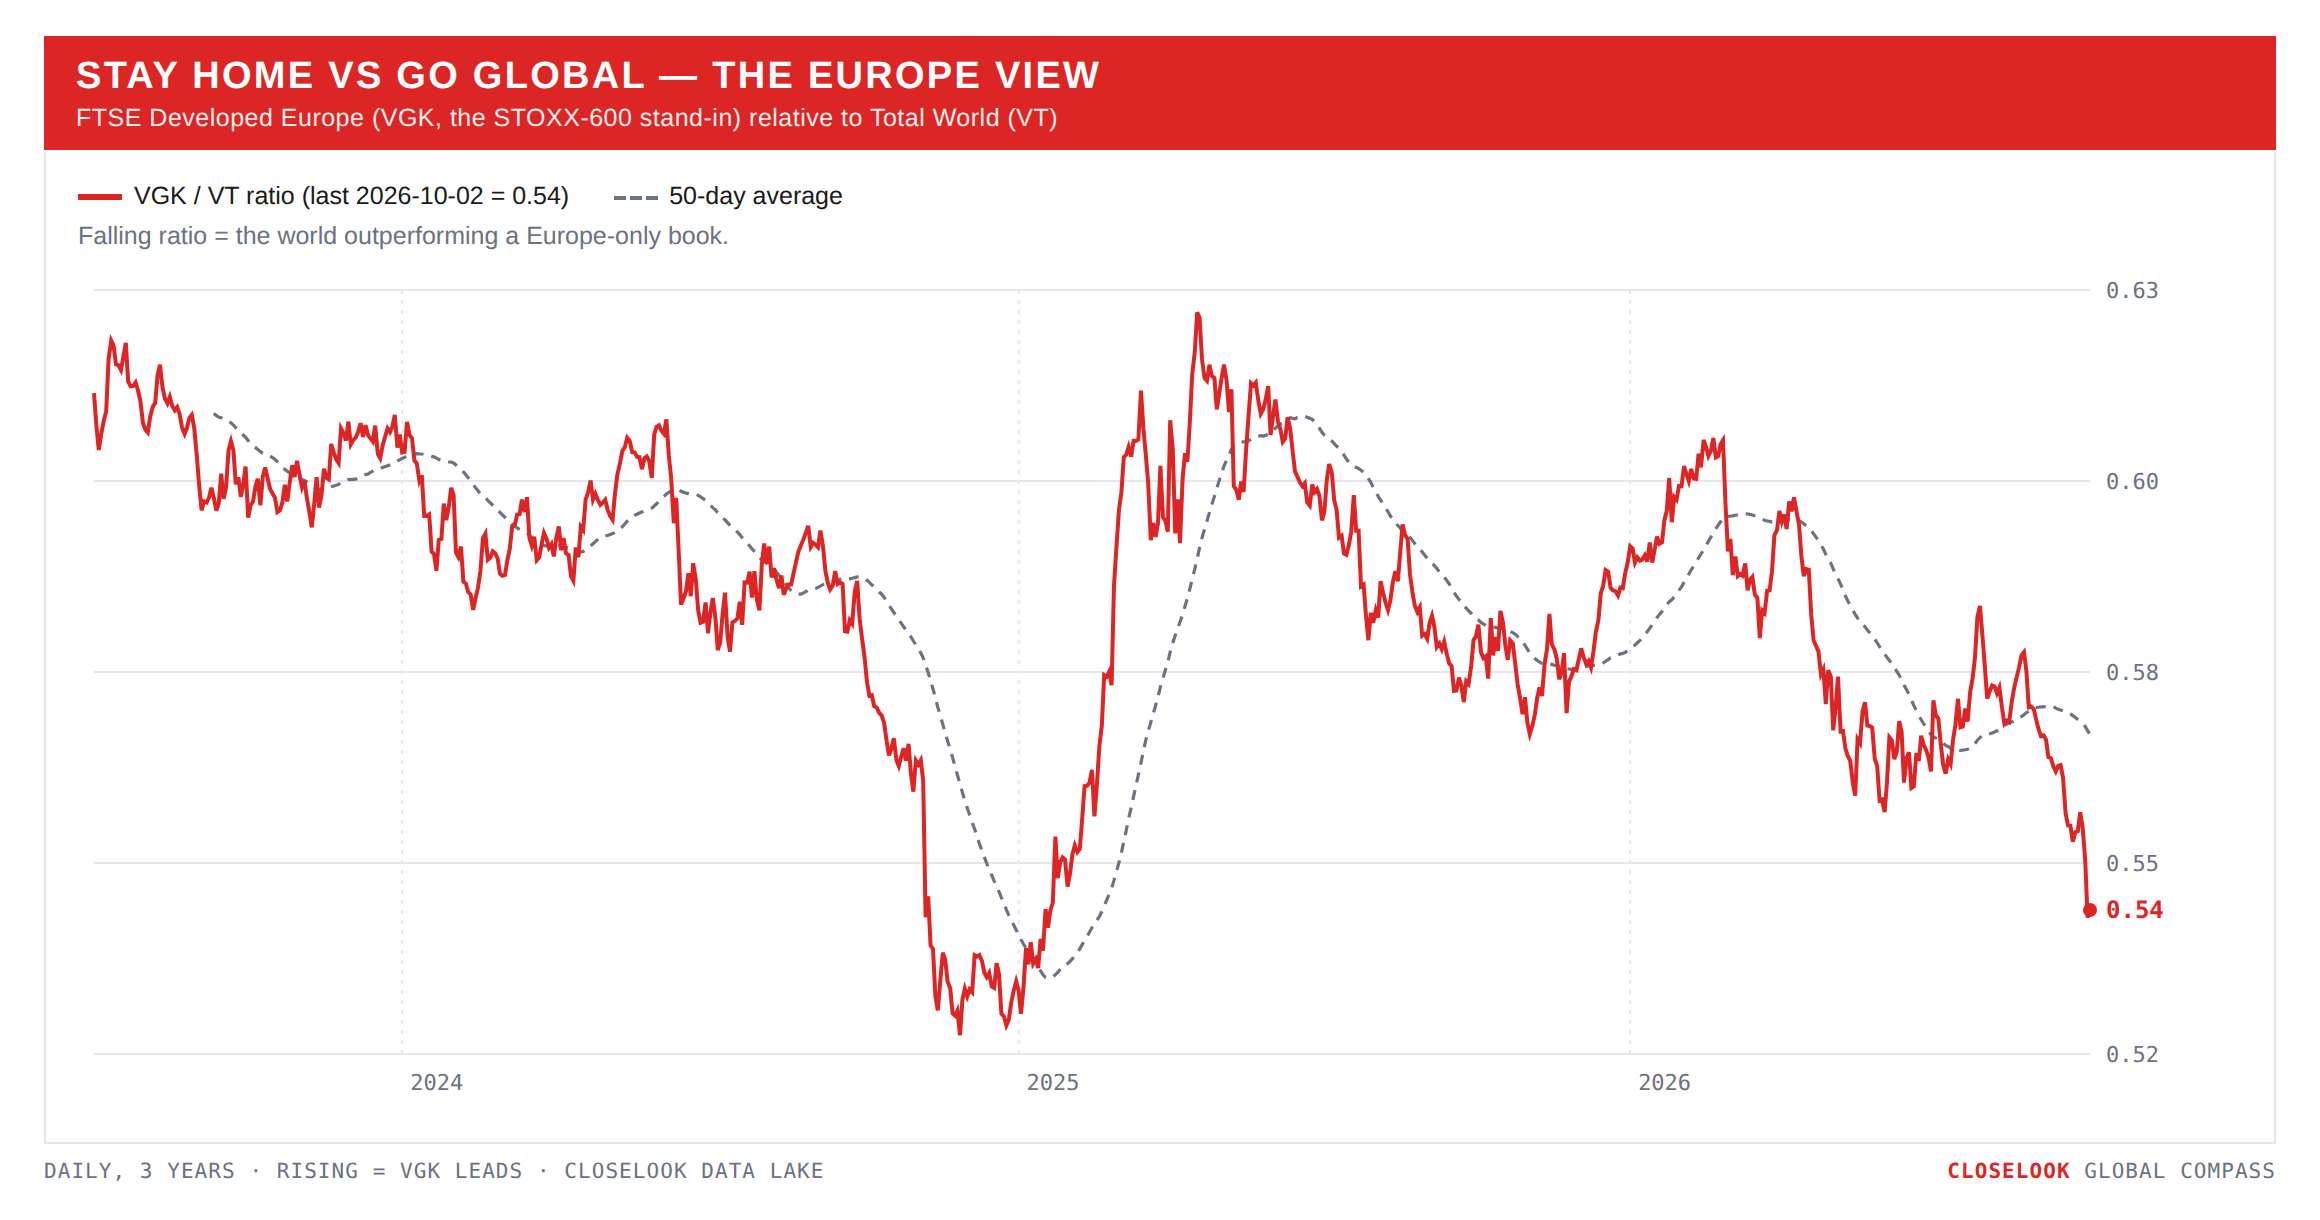
Stay home vs go global — the Europe view: the currency became the cost. The euro-hedged Europe fund fell 0.94%; the dollar-listed one fell 2.54% — 1.6 points of the loss were the euro. In local terms: the STOXX 600 −1.28%, the Euro Stoxx 50 −1.02%, the DAX −0.70% to 25,231, the CAC −1.96% to 7,920, Spain's IBEX −3.12%, the FTSE 100 −2.18%, Switzerland's SMI −1.90%. For seven weeks this letter has called the gap between the two funds a mask that flips. This week it did not flip. It cost.
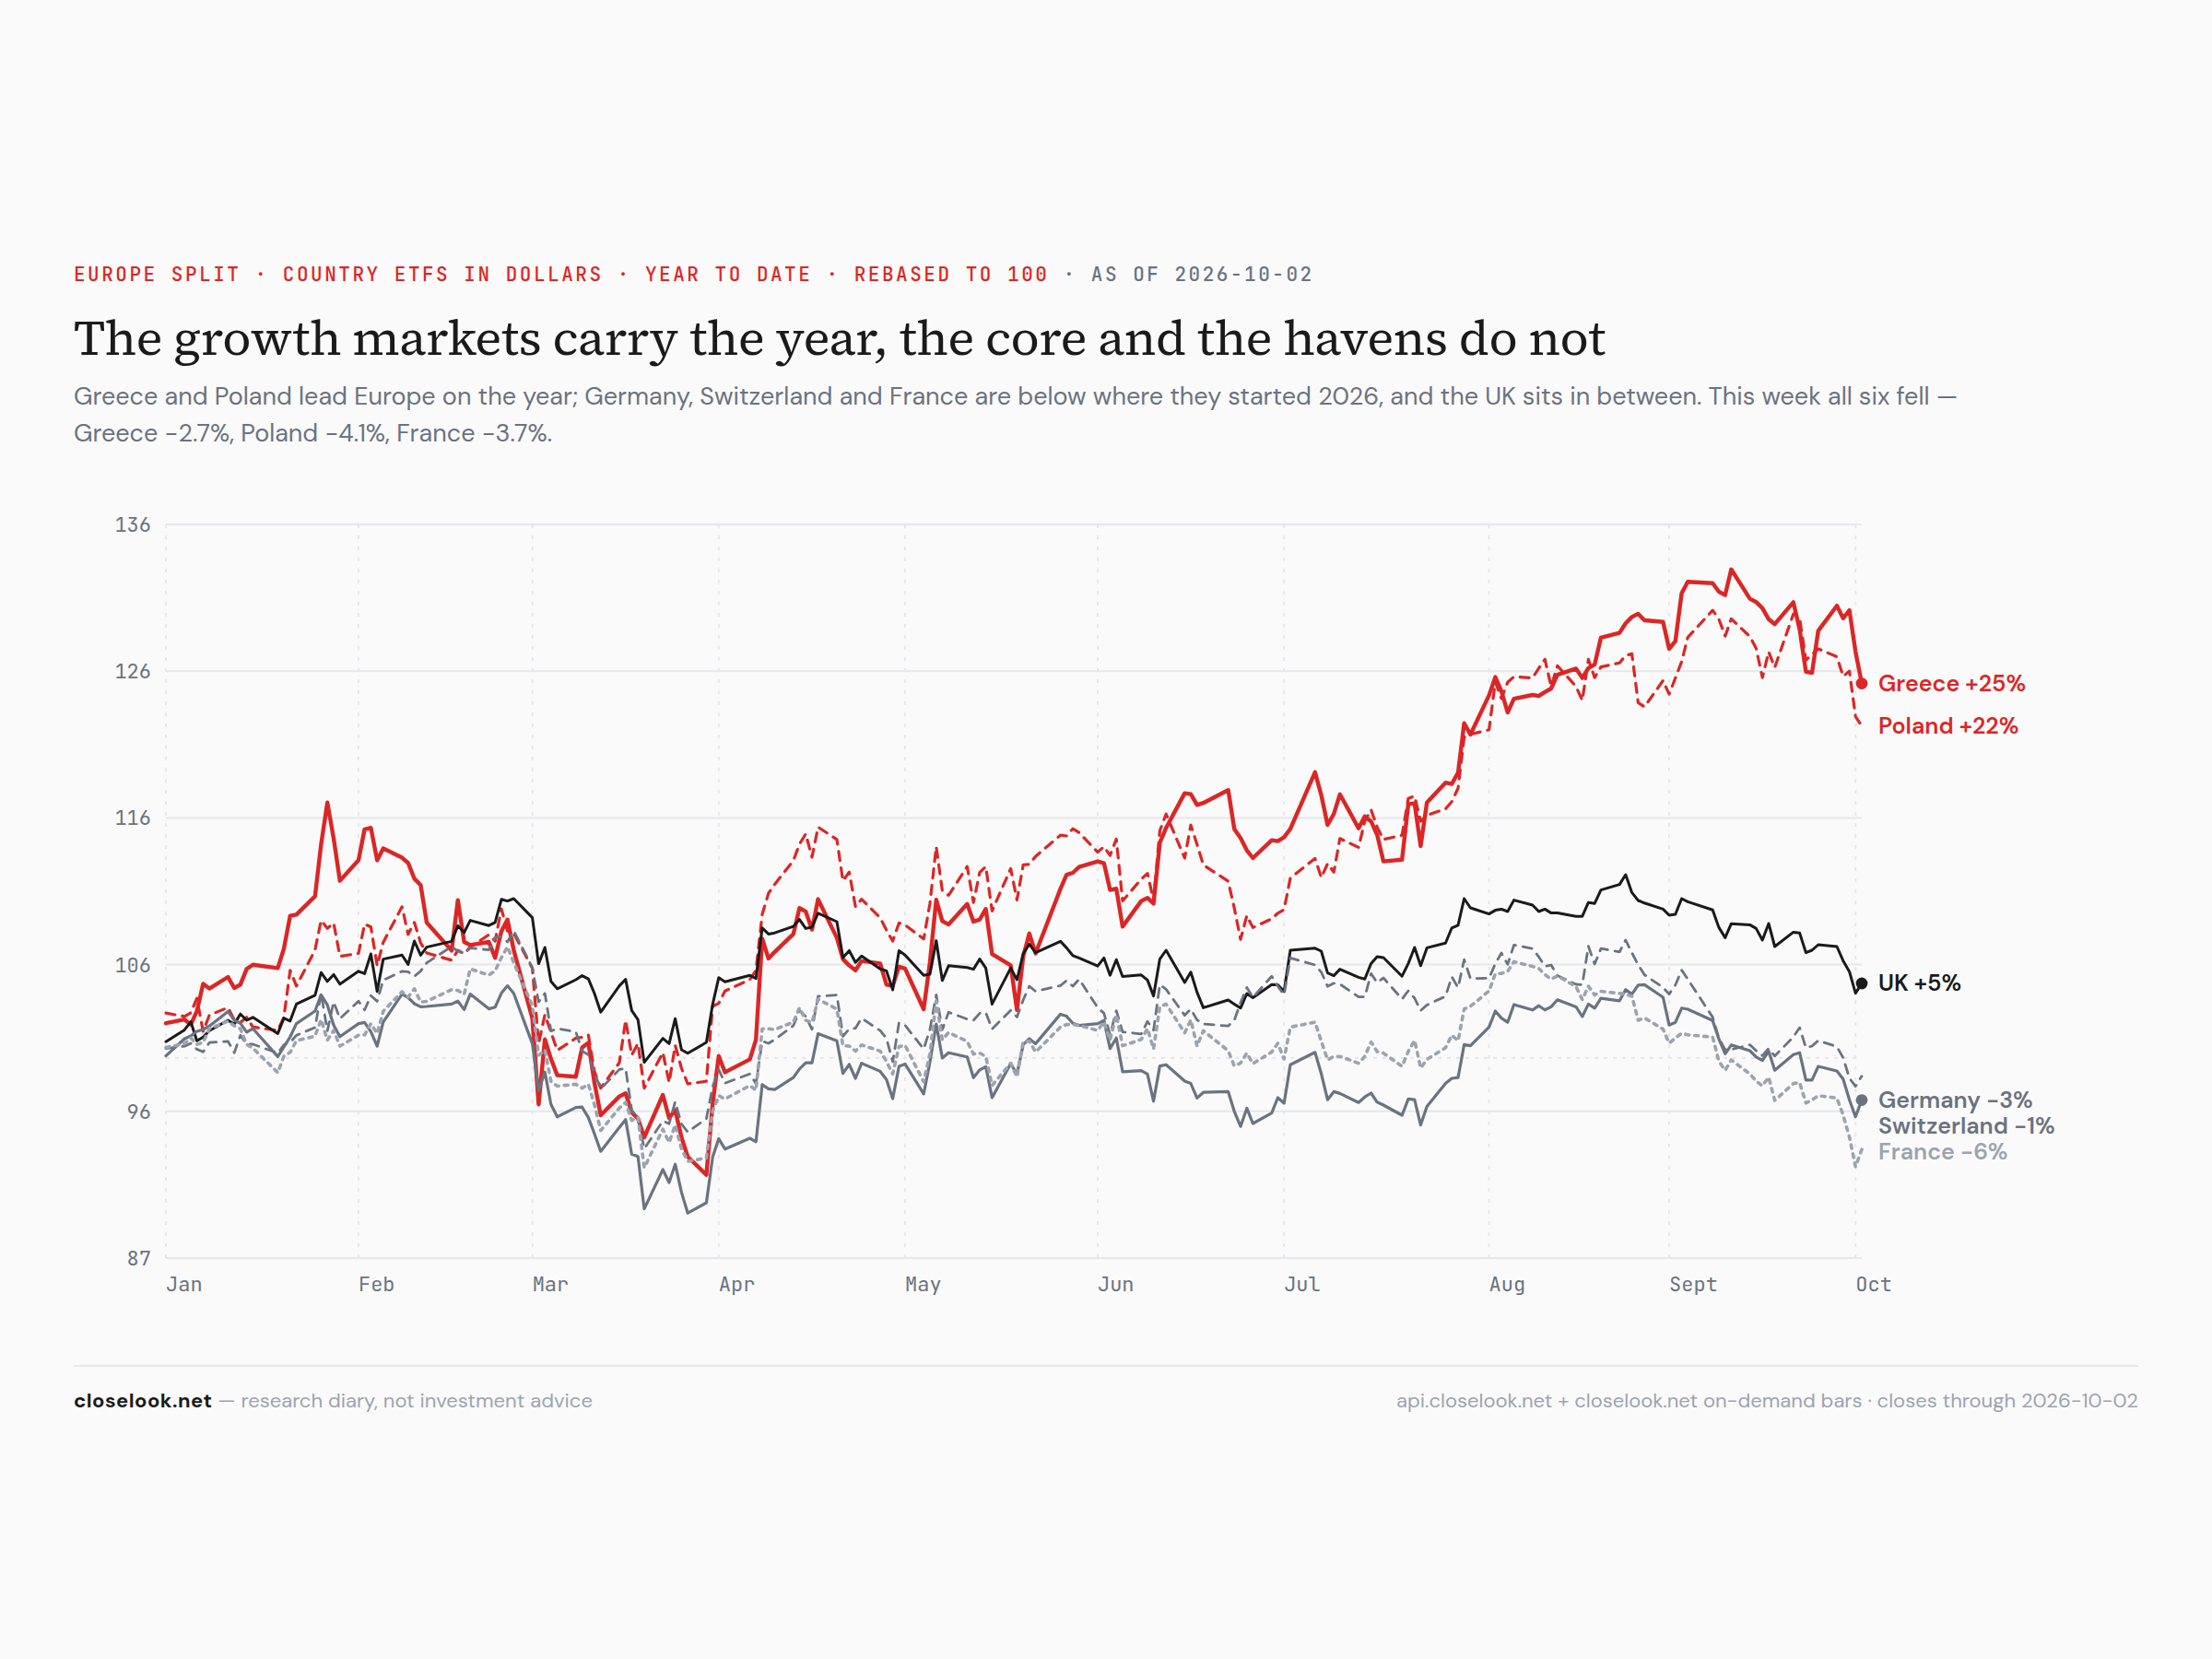
Europe split — the growth markets and everyone else. The year in Europe is not one market either. Greece +25% and Poland +22% in dollars; Britain +5%; the Netherlands +19% and Austria +18% on the ASML and chip-equipment leg; Switzerland −1%, Germany −3%, France −6%. The two markets with their own growth — Poland's economy, Greece's repaired finances, now cheaper to borrow for than France — carry the year. The core and the havens do not. This week was the exception: Greece fell 2.75% and Poland 4.06%, both more than the core. When money leaves a region, it leaves the best-performing corners too — they are where the gains are to take. The thesis is a year's thesis; the week tested it.
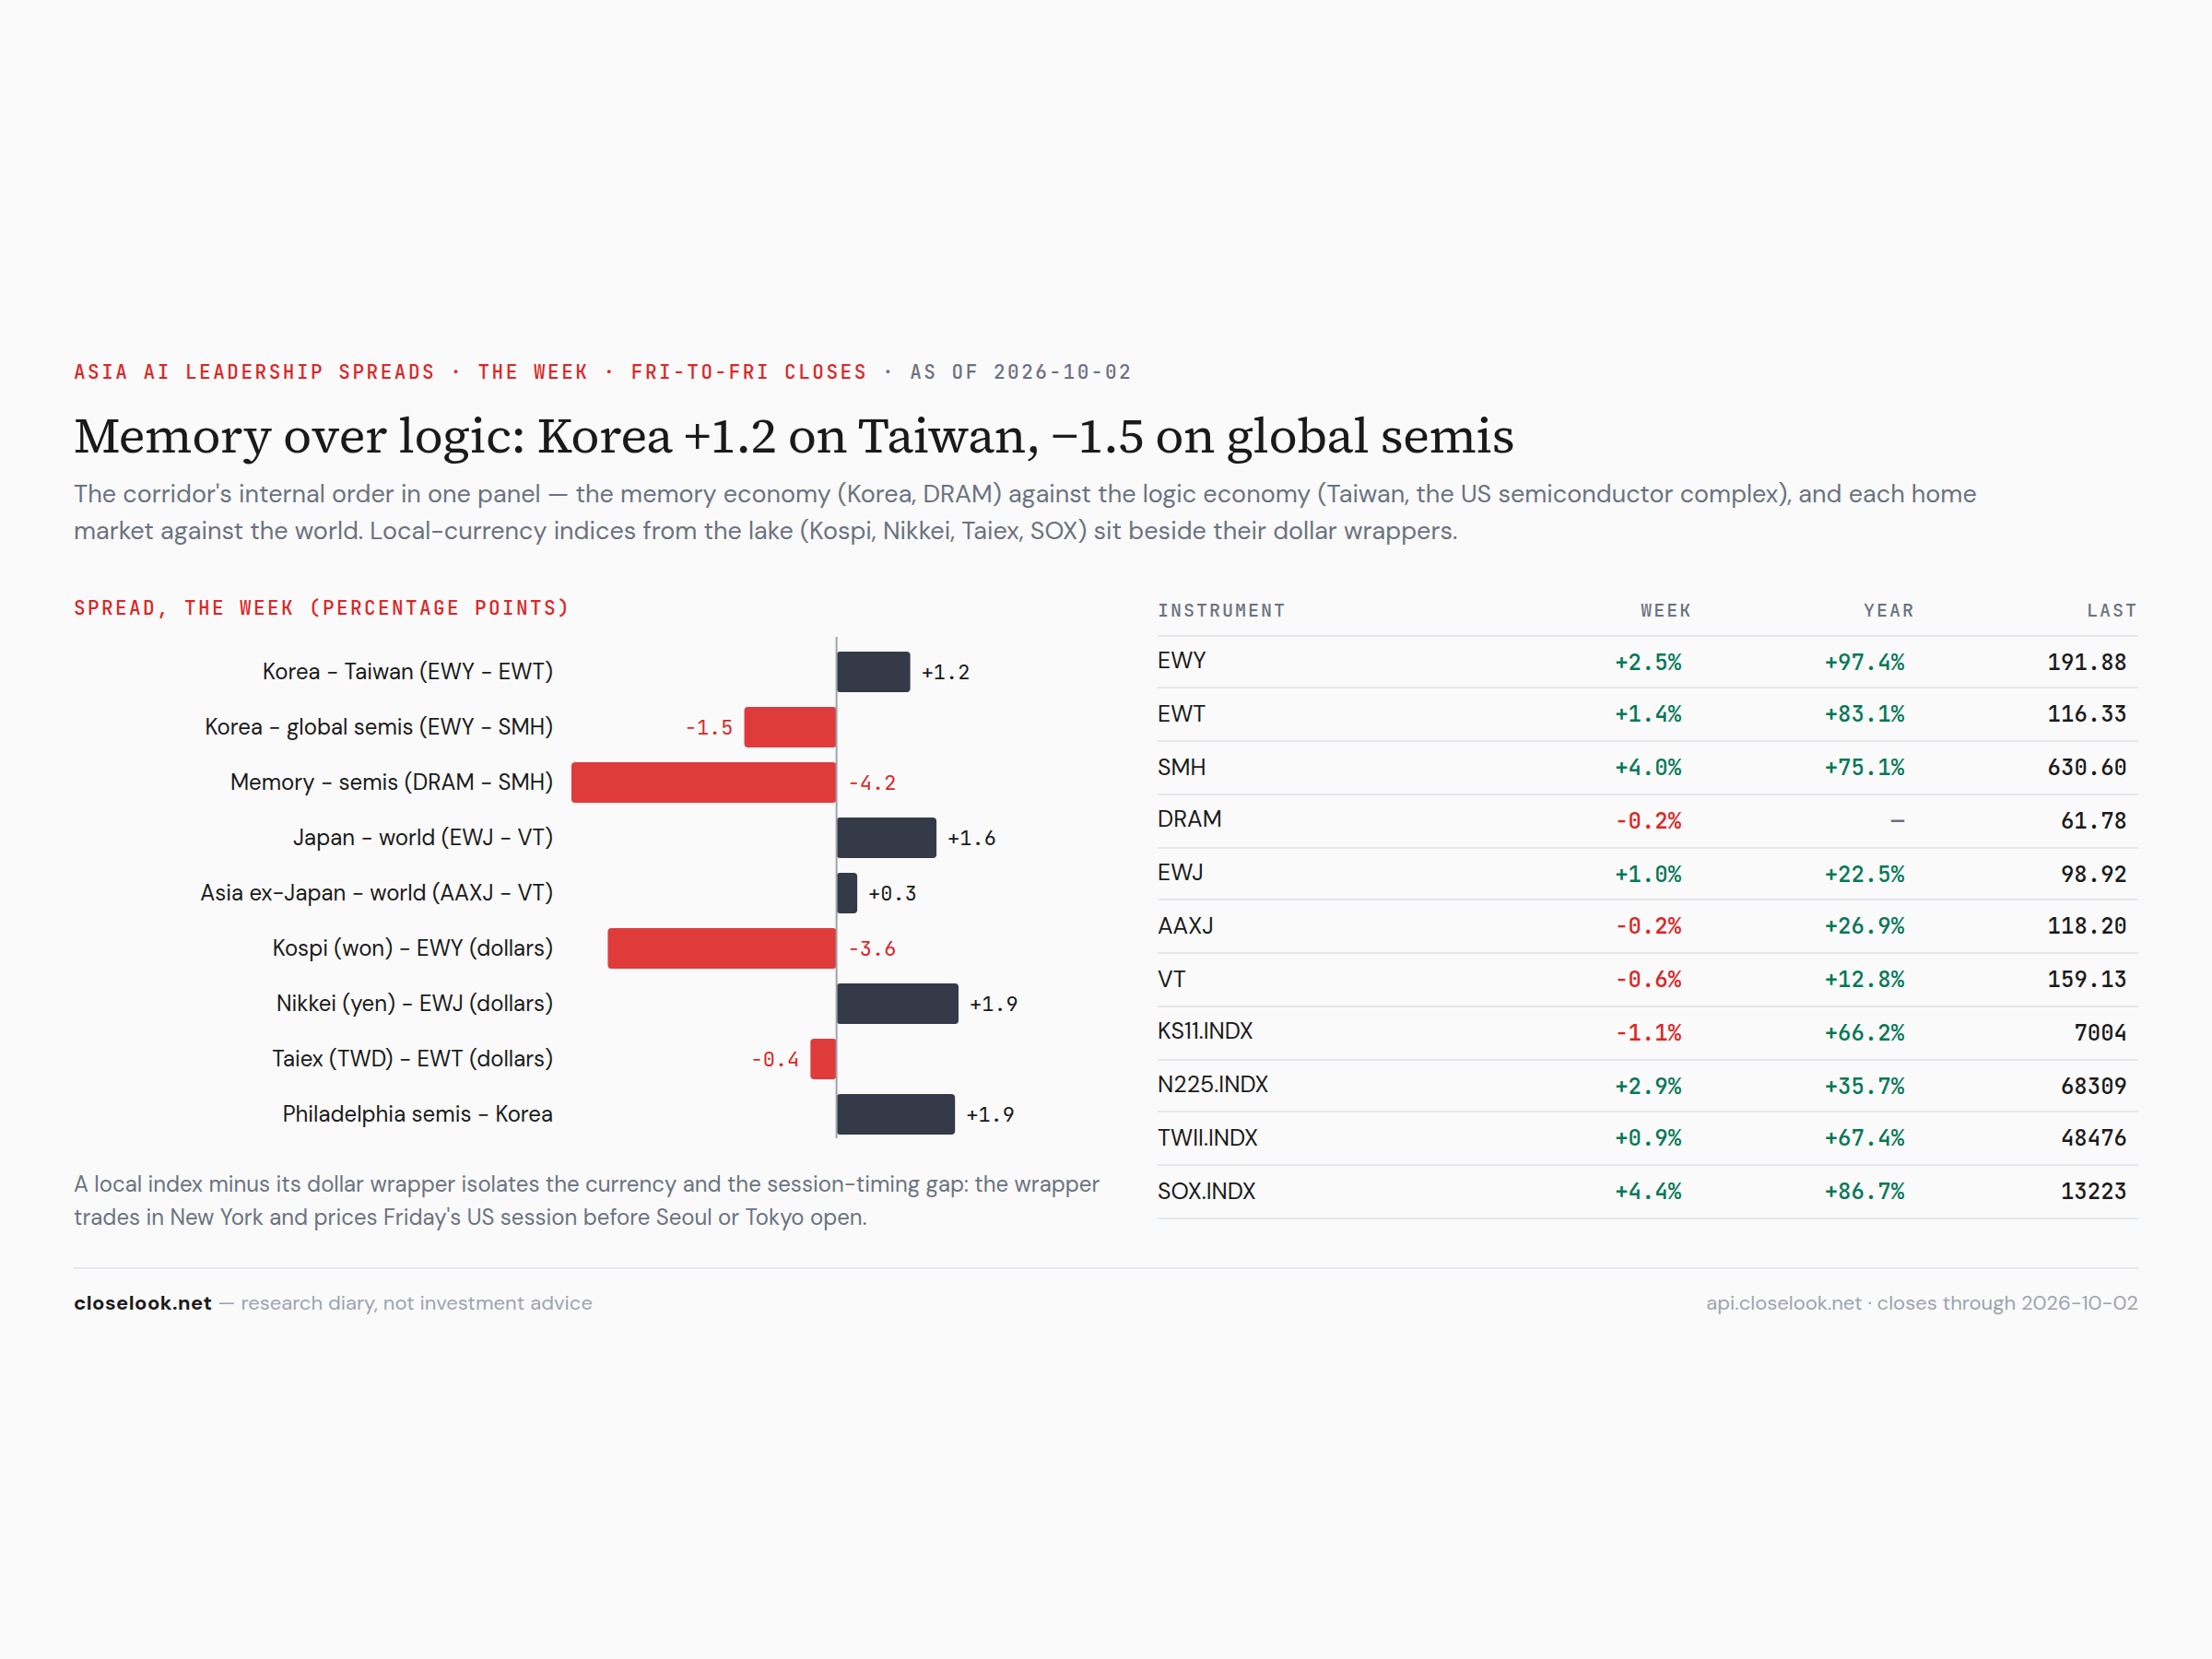
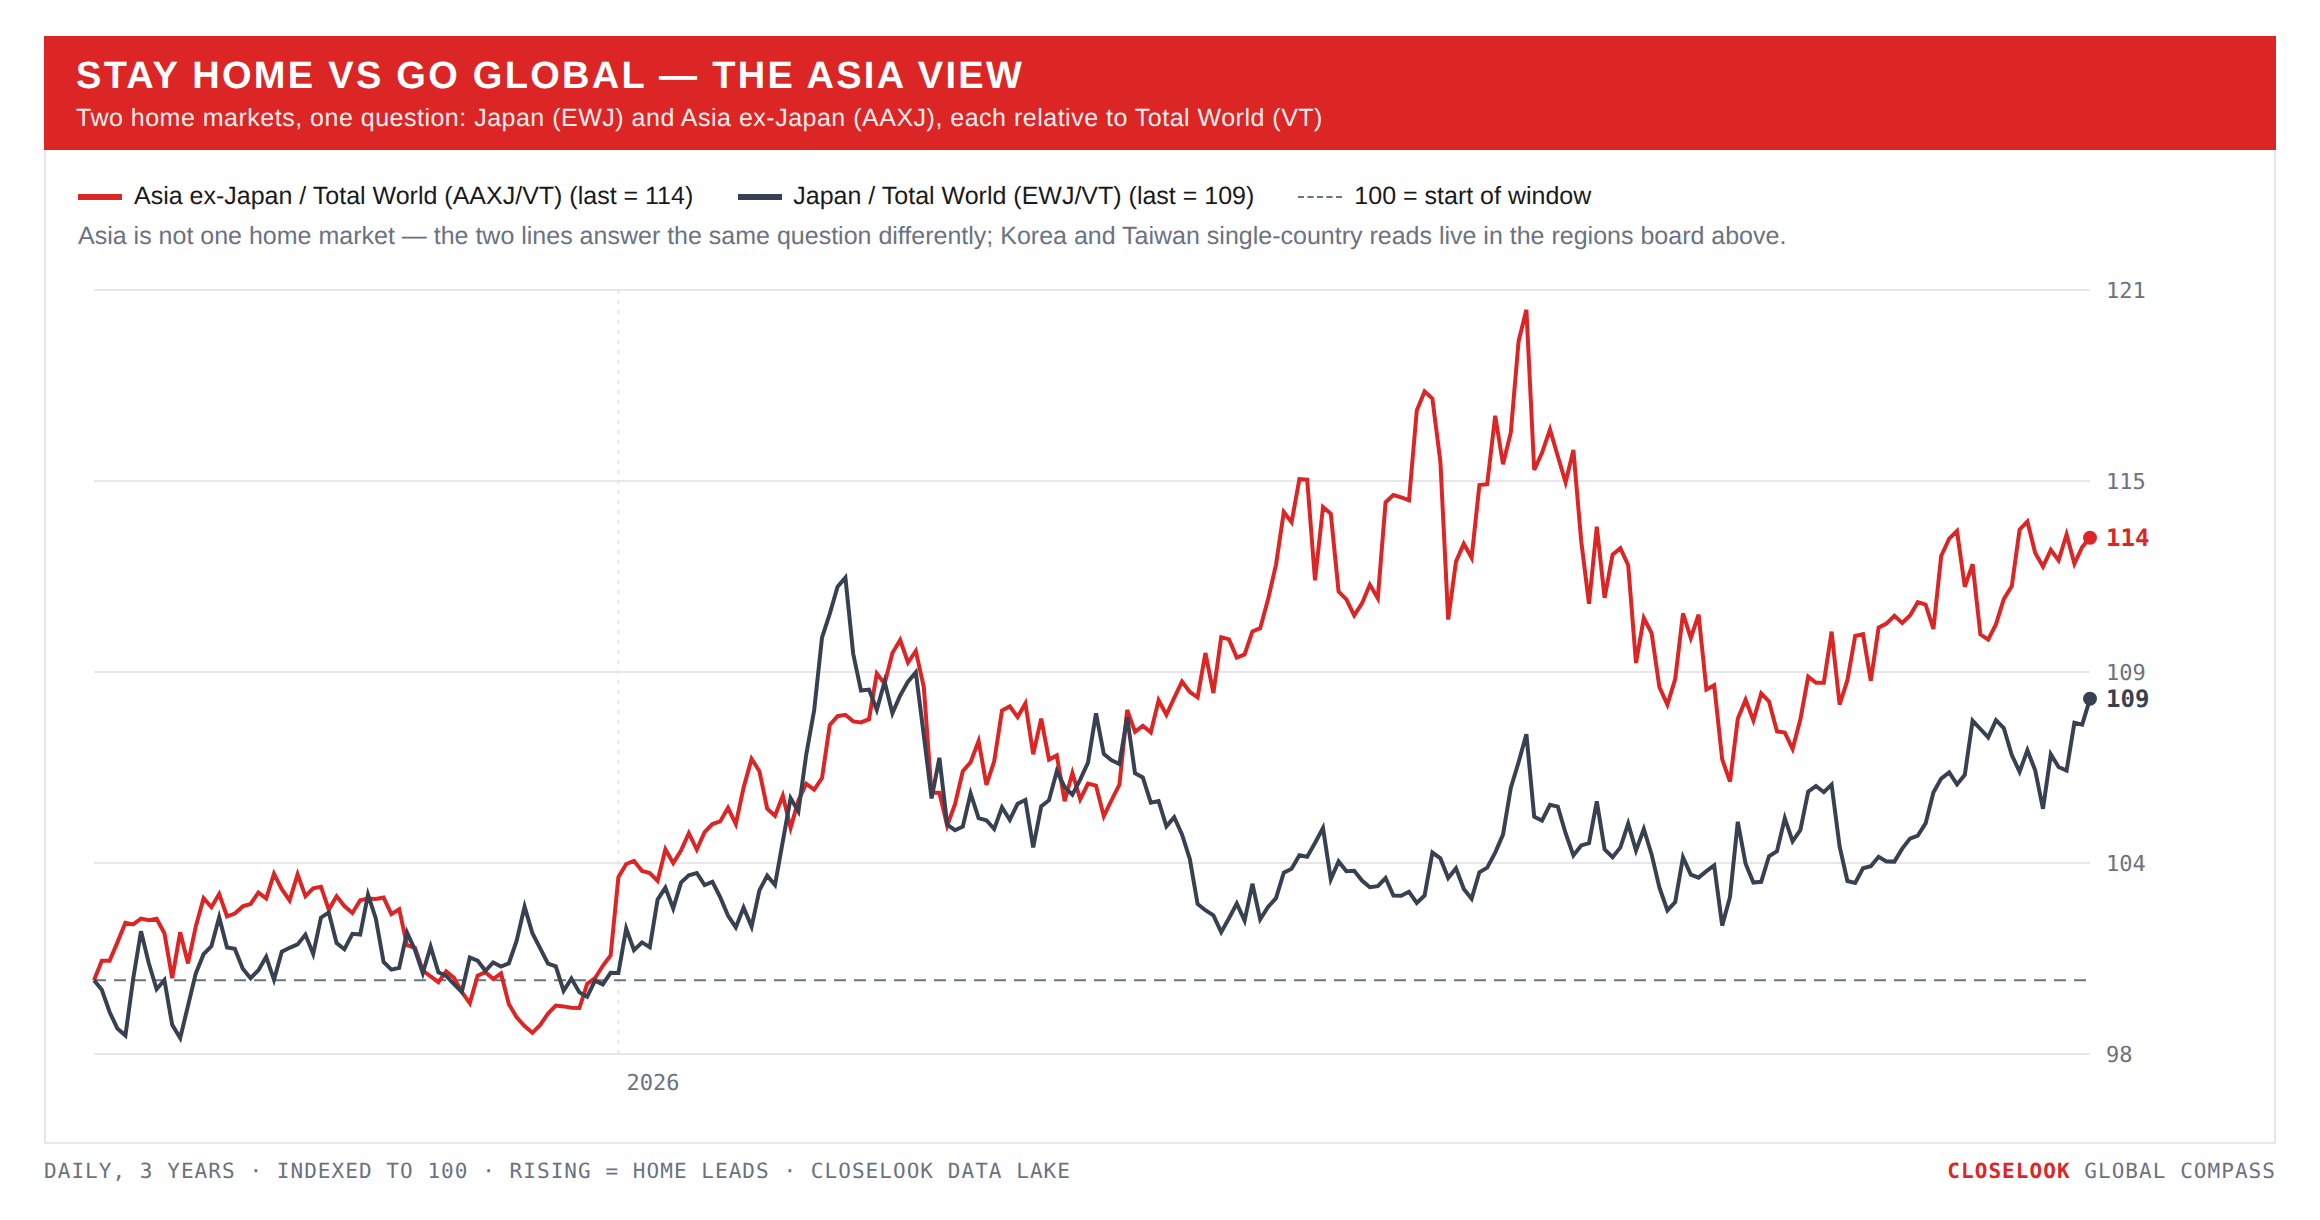
Stay home vs go global — the Asia view: the AI markets ahead, the rest behind. Taiwan: EWT +1.35% to a record close, the Taiex +0.94% to a record 48,476. Korea: EWY +2.51% to 191.88; the Kospi closed Monday 2.7% lower as it reopened after the Chuseok holiday — owed two strong New York sessions it had missed — and the tech-heavy Kosdaq rose 5.8% on the week. Japan split down the middle: the Nikkei, heavy in chip-equipment names, +2.93% to 68,309 on Micron's record quarter (+3.3% on Thursday alone), while the broad TOPIX fell 0.91%. That is "parts of Japan" in two numbers: the AI part up three percent, the rest of Japan down one. India: −2.80%, the Nifty −2.78%, the Sensex at 71,910 on Thursday, its lowest close in a year. Hong Kong −2.19% before its holiday. The yen closed at 157.83.
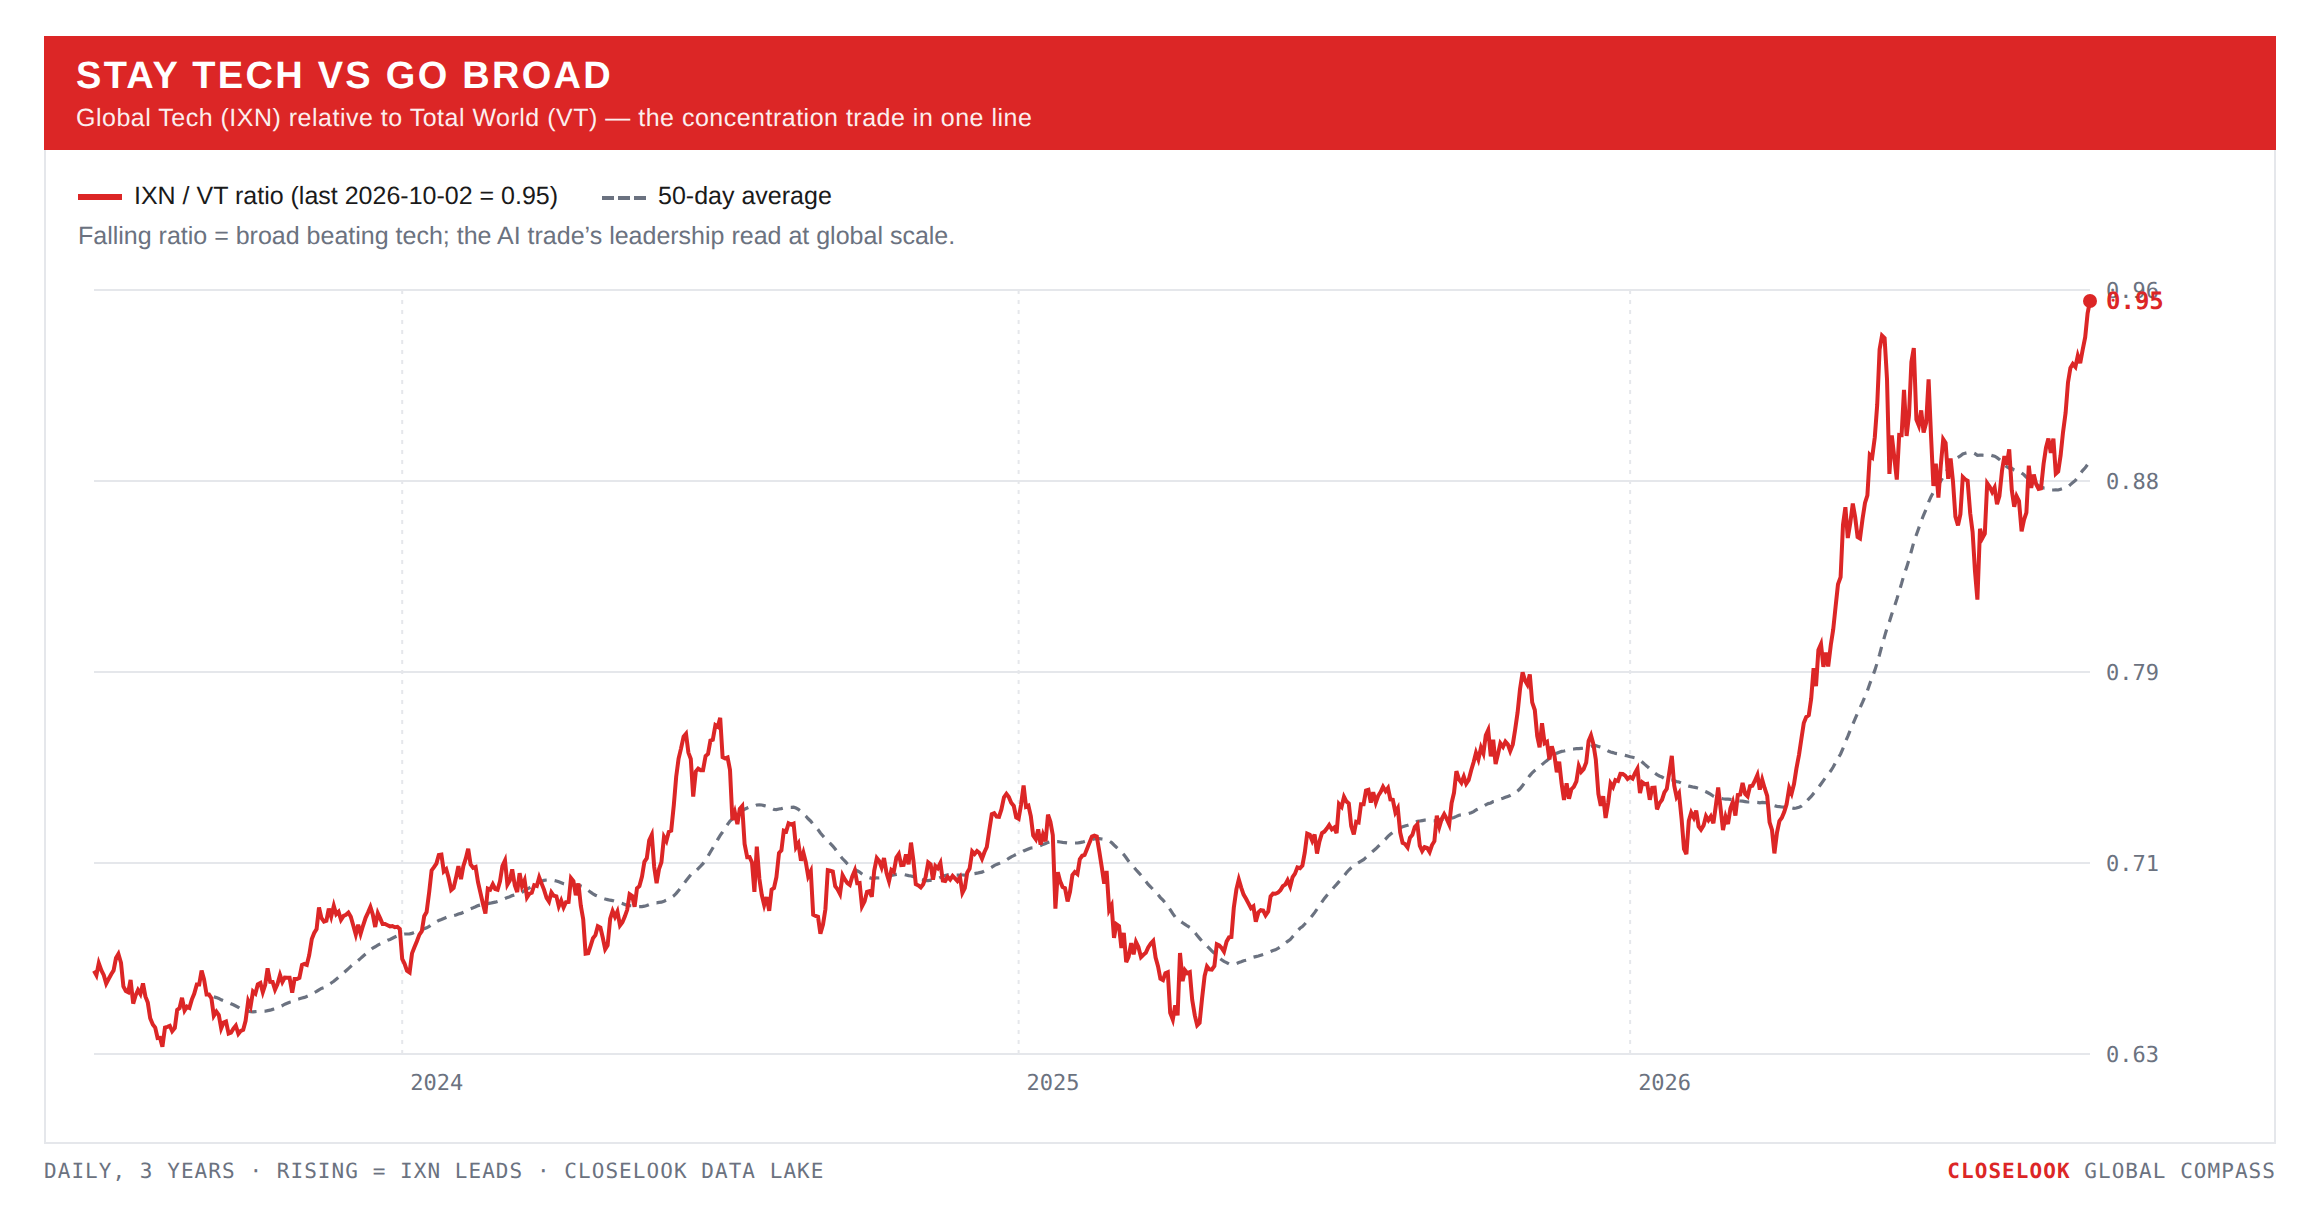
Stay tech vs go broad. Tech led again, at home and abroad. The Nasdaq 100 +1.01% against the S&P's −0.27% and the equal-weight S&P's −0.65%; global tech +2.00% against the world's −0.56%. Technology was the best US sector and the best global sector for a second week, and this week both made records. The ratio of global tech to the world index is at its high of the year.
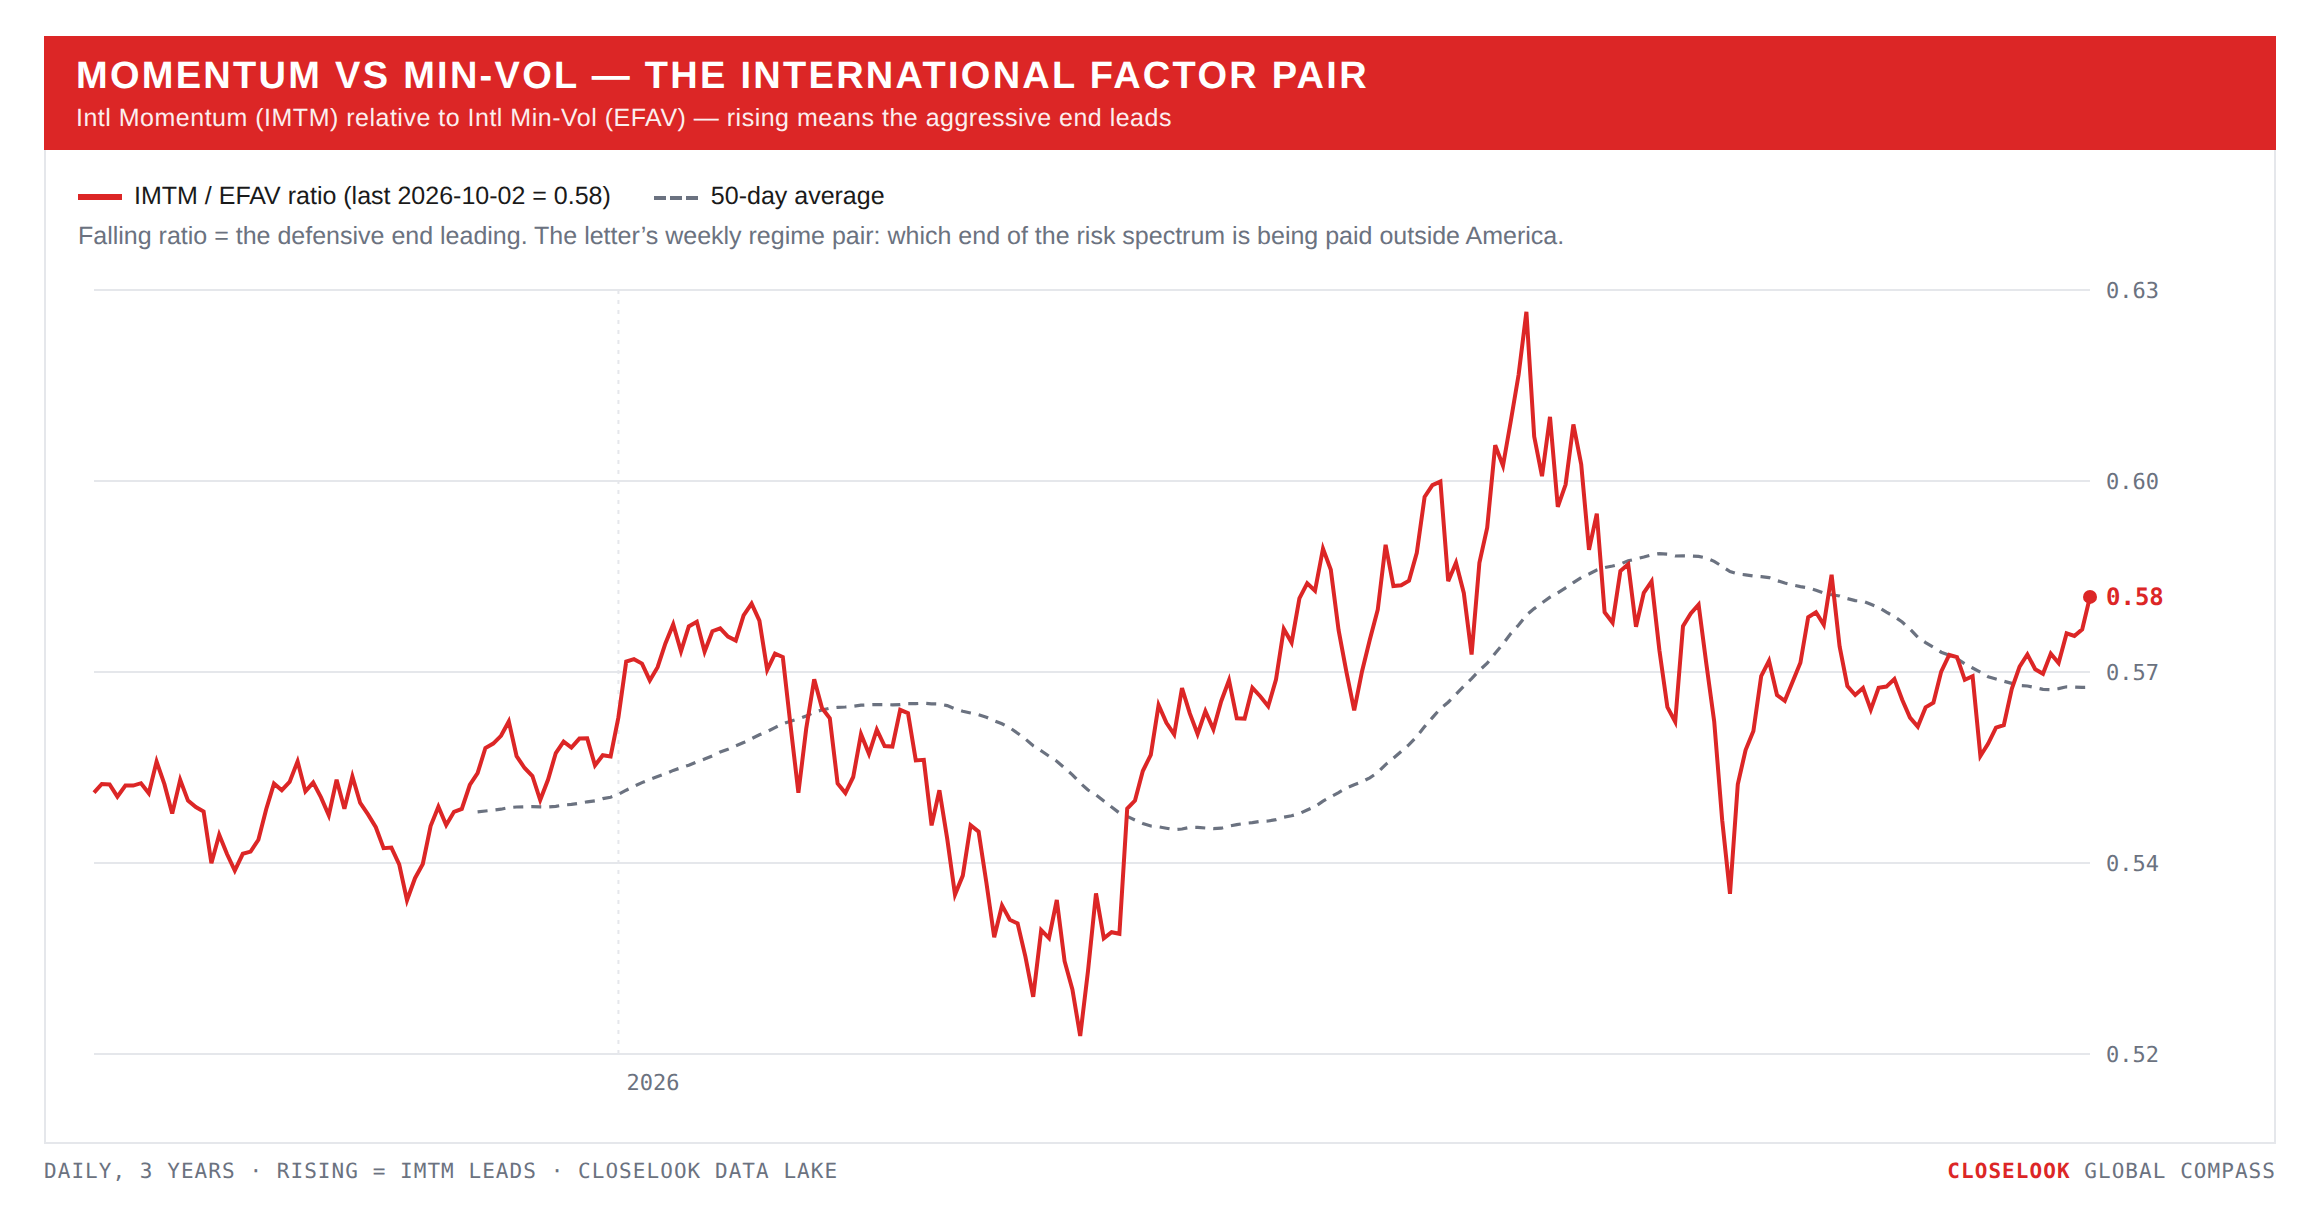
Momentum vs defensive — both down, min-vol more. International momentum fell 0.64% to 53.05; international min-vol 2.02% to 90.96; global min-vol −0.64%. On the year momentum leads +10.6% against +5.5%. The low-volatility funds are full of the utilities, staples and banks that sold off with the long end; that is why the defensive factor was not defensive this week.
One more pair: growth over value, a third week. EAFE growth +0.08% against value −2.94%. On the year value still leads, +9.9% against +6.3%, but the gap has closed from 7.1 points a week ago to 3.6. Value outside America is European banks, energy and materials; this week all three fell.
The Closelook letters — where this one sits. The house thesis, compressed: the stock market is a growing system at the aggregate level in which most constituents slowly fade while a small group massively outperforms — and that group changes dynamically; it never stays static. Own the aggregate, know the current winner group, watch for the rotation. Right now the winner group is the AI stack, and this week the map showed where it lives: in America's technology and Asia's chip corridor, not in Europe's core or in India. This letter reads the map (regions, currencies, rates); Sunday's US letter reads the tape and its levels; Sunday evening's Hypergrowth letter reads the names.
2 · The State
The mechanism, named: the AI trade concentrated, and the dollar went with it. Put the week in order. Monday: Seoul reopened after Chuseok 2.3% lower, Samsung and SK Hynix down about 4% two days before Micron; in New York Meta started a business unit to sell its AI stack to companies and hired MongoDB's chief executive to run it — MongoDB −18% — while Nvidia rose 2.7% in a red market and gold fell 3.8%. Tuesday: the thirty-year yield touched 5.60%, the long-bond fund broke 78; Washington opened the mortgage market to FICO's rival score, Fair Isaac −29%. Wednesday: core inflation came in soft — 0.2% for August, 3.0% on the year against 3.3% expected — and the long-bond fund still closed lower; oil fell as the strategic reserve was offered; Micron reported a record quarter after the close, and the quarterly reset of our equal-weight indices ran on the last day of the quarter. Thursday: Tokyo +3.3% on Micron, Accenture +18% on record bookings, the euro and the dollar fund at their extremes of the year, India at its low. Friday: 29,000 jobs and 60,000 of revisions, a rally at the open, a ten-year yield higher by the close, the Nasdaq 100 at a record.
Soft inflation and a weak jobs report did not lower the long end. That is the week's bond fact, and it says the yield is not only about the Fed's next move. It is about how much the market wants to be paid to lend for thirty years to governments that borrow more every year — America included, but America with the growth to show for it.
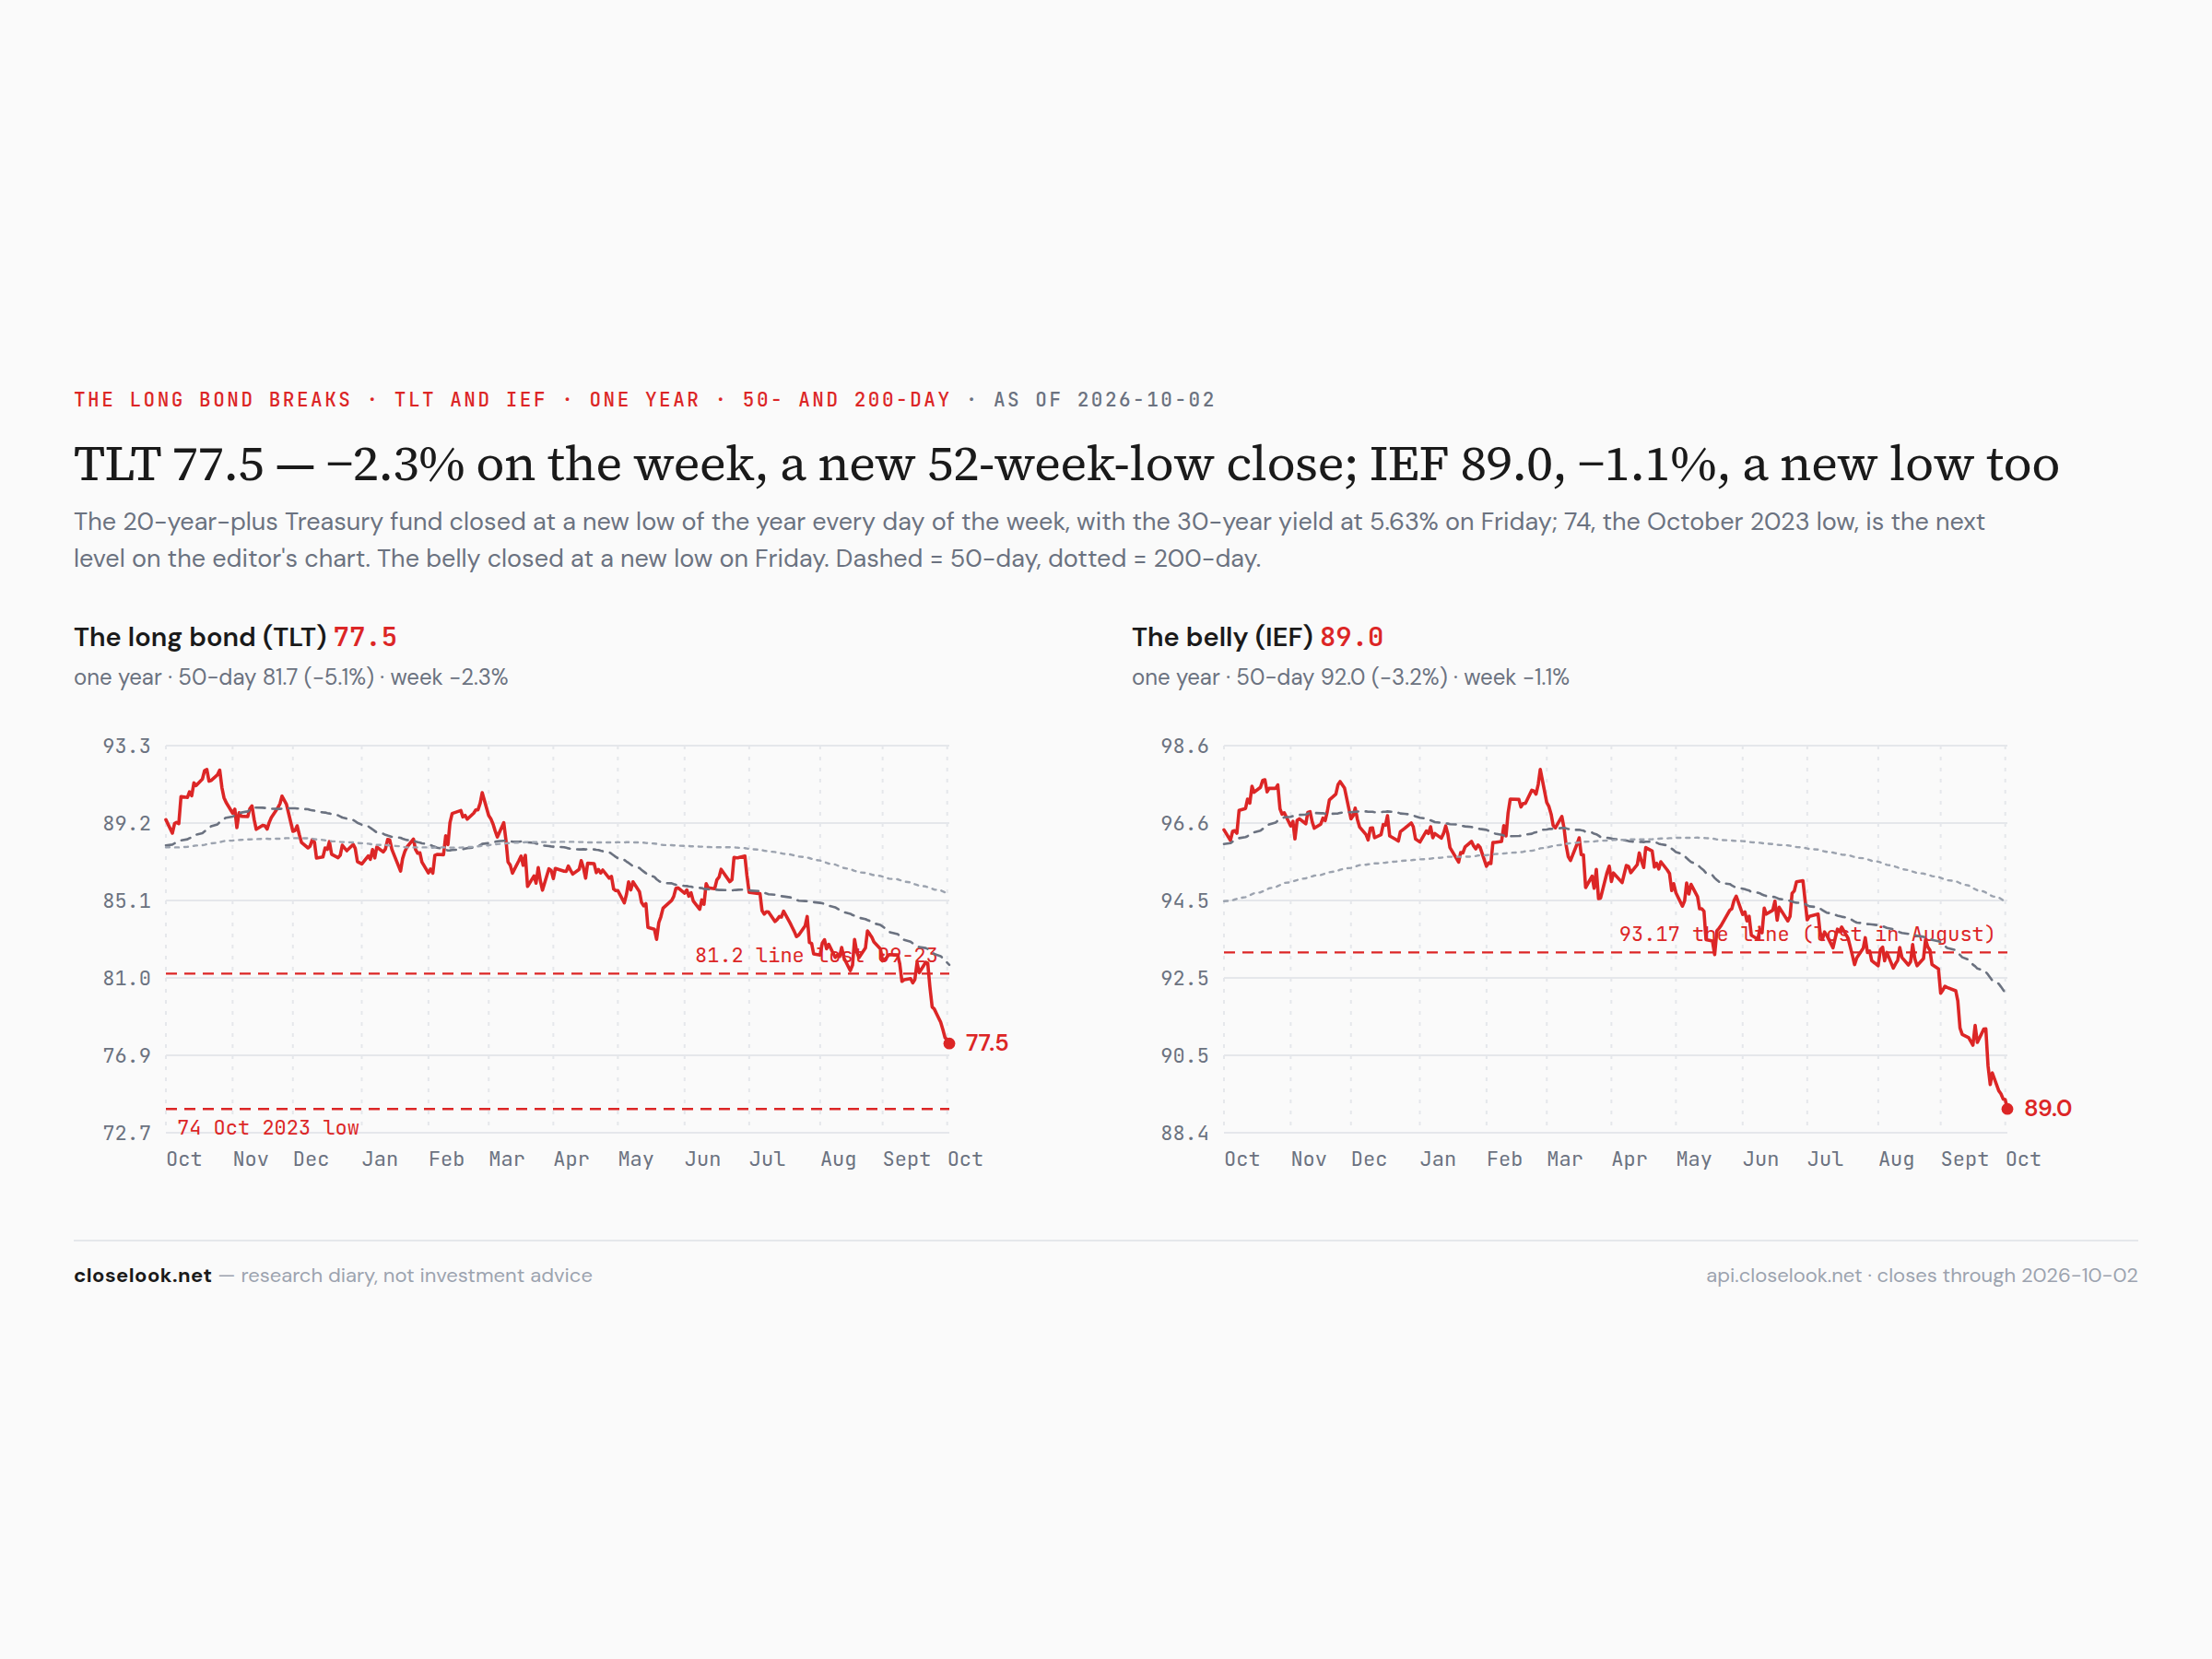
The long bond — a new low every day. TLT: 78.62 Monday, 78.23, 77.78, 77.71, 77.48 — five sessions, five new fifty-two-week-low closes, −2.32% on the week, 4.5% above 74, the October 2023 low the editor's chart names as the next level. IEF closed at 89.05, a new low on Friday, an eighth week under the 93.17 line. Even the short end gave way: the one-to-three-year Treasury fund closed at its low of the year. The thirty-year yield closed at 5.61% and the ten-year at 5.28%, +50 basis points in twenty-one sessions.
The rate rise is global — one sentence for each reason. Friday's Pulse laid it out country by country; here the map. The house sovereign pressure index closed at 0.59, from 0.61; the equal-weight ten-year across the board's sovereigns is 4.38%, +33 basis points in twenty-one sessions. America: 5.28% on the ten-year, the reason growth. Britain: 5.37% and 5.89% on the thirty-year, the reason a budget the market doubts. Japan: 3.11%, the reason a central bank leaving zero. Germany: 3.47%, lower on the week. France: 4.87%, Italy 4.61%, the reason credit. The level is shared; the reason is not.
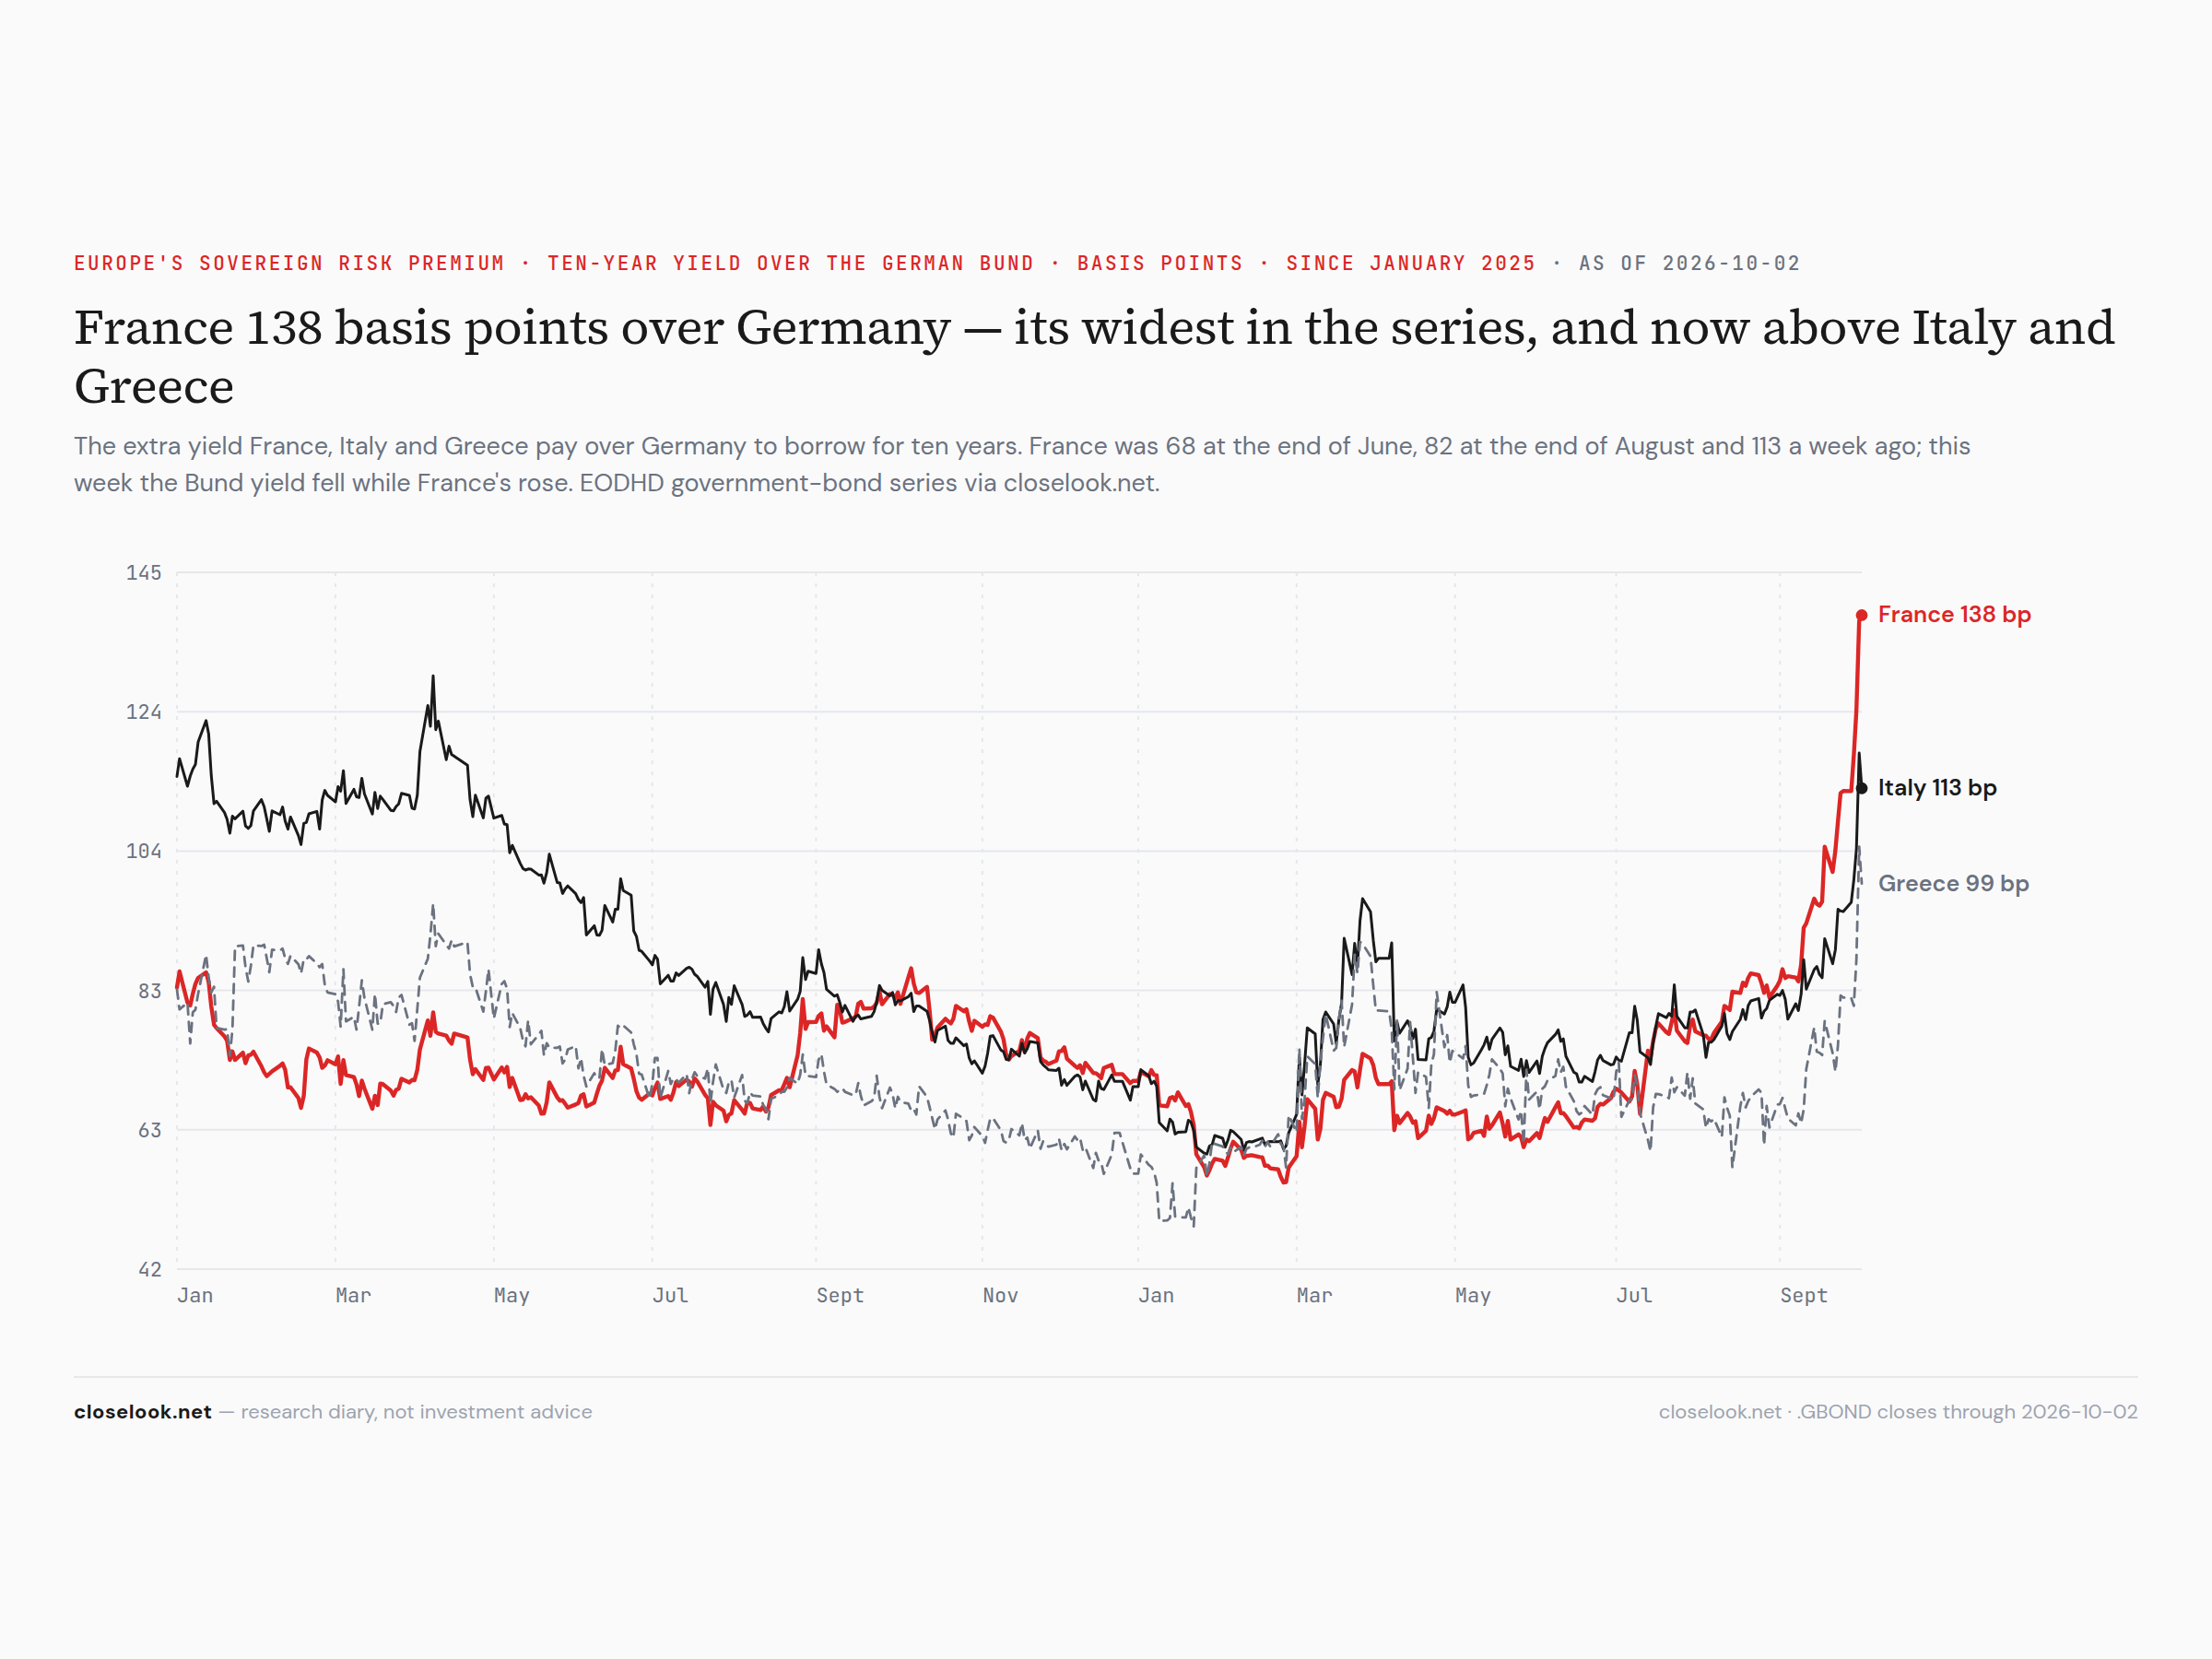
France — the spread jumped again. On the house series the French ten-year now pays 138 basis points over the Bund, from 113 a week ago, 82 at the end of August and 68 at the end of June. This week the Bund yield fell to 3.47% while France's rose to 4.87%: money moved inside the euro area, from Paris to Frankfurt — the first week of the episode that looks like a flight to quality rather than a general sell-off. France now pays 25 basis points more than Italy to borrow for ten years, and on the chart about 40 more than Greece. The French fund is down 6.1% on the year, the CAC 9.2% under its August high. Last week this letter said the next funding crisis is more likely to start in Europe, and in Paris first. This week's move is the kind that thesis predicts. (Editor's note: a 25-point weekly move on the vendor series deserves a second source before it is quoted elsewhere.)
The consequence — avoid Europe, with two exceptions. This letter's positioning, stated plainly: this diary stays away from mainland Europe's core, and from France in particular — and this week it adds Switzerland and Britain to the list. Switzerland was the safe haven in last week's letter; this week its fund fell 2.36% and is −1.2% on the year, a haven that does not hold value in a week like this is not one. Britain's fund fell 2.41% with a thirty-year gilt at 5.89%. The exceptions are the growth markets: Greece and Poland, +25% and +22% on the year, with their own growth and their own repaired finances — even after a week in which both fell harder than the core. The Global ETFs book still holds a Swiss fund and a Polish one; it traded nothing this week, and the Swiss line is now the one that does not fit the letter's map (§5). This is a diary's positioning, not advice.
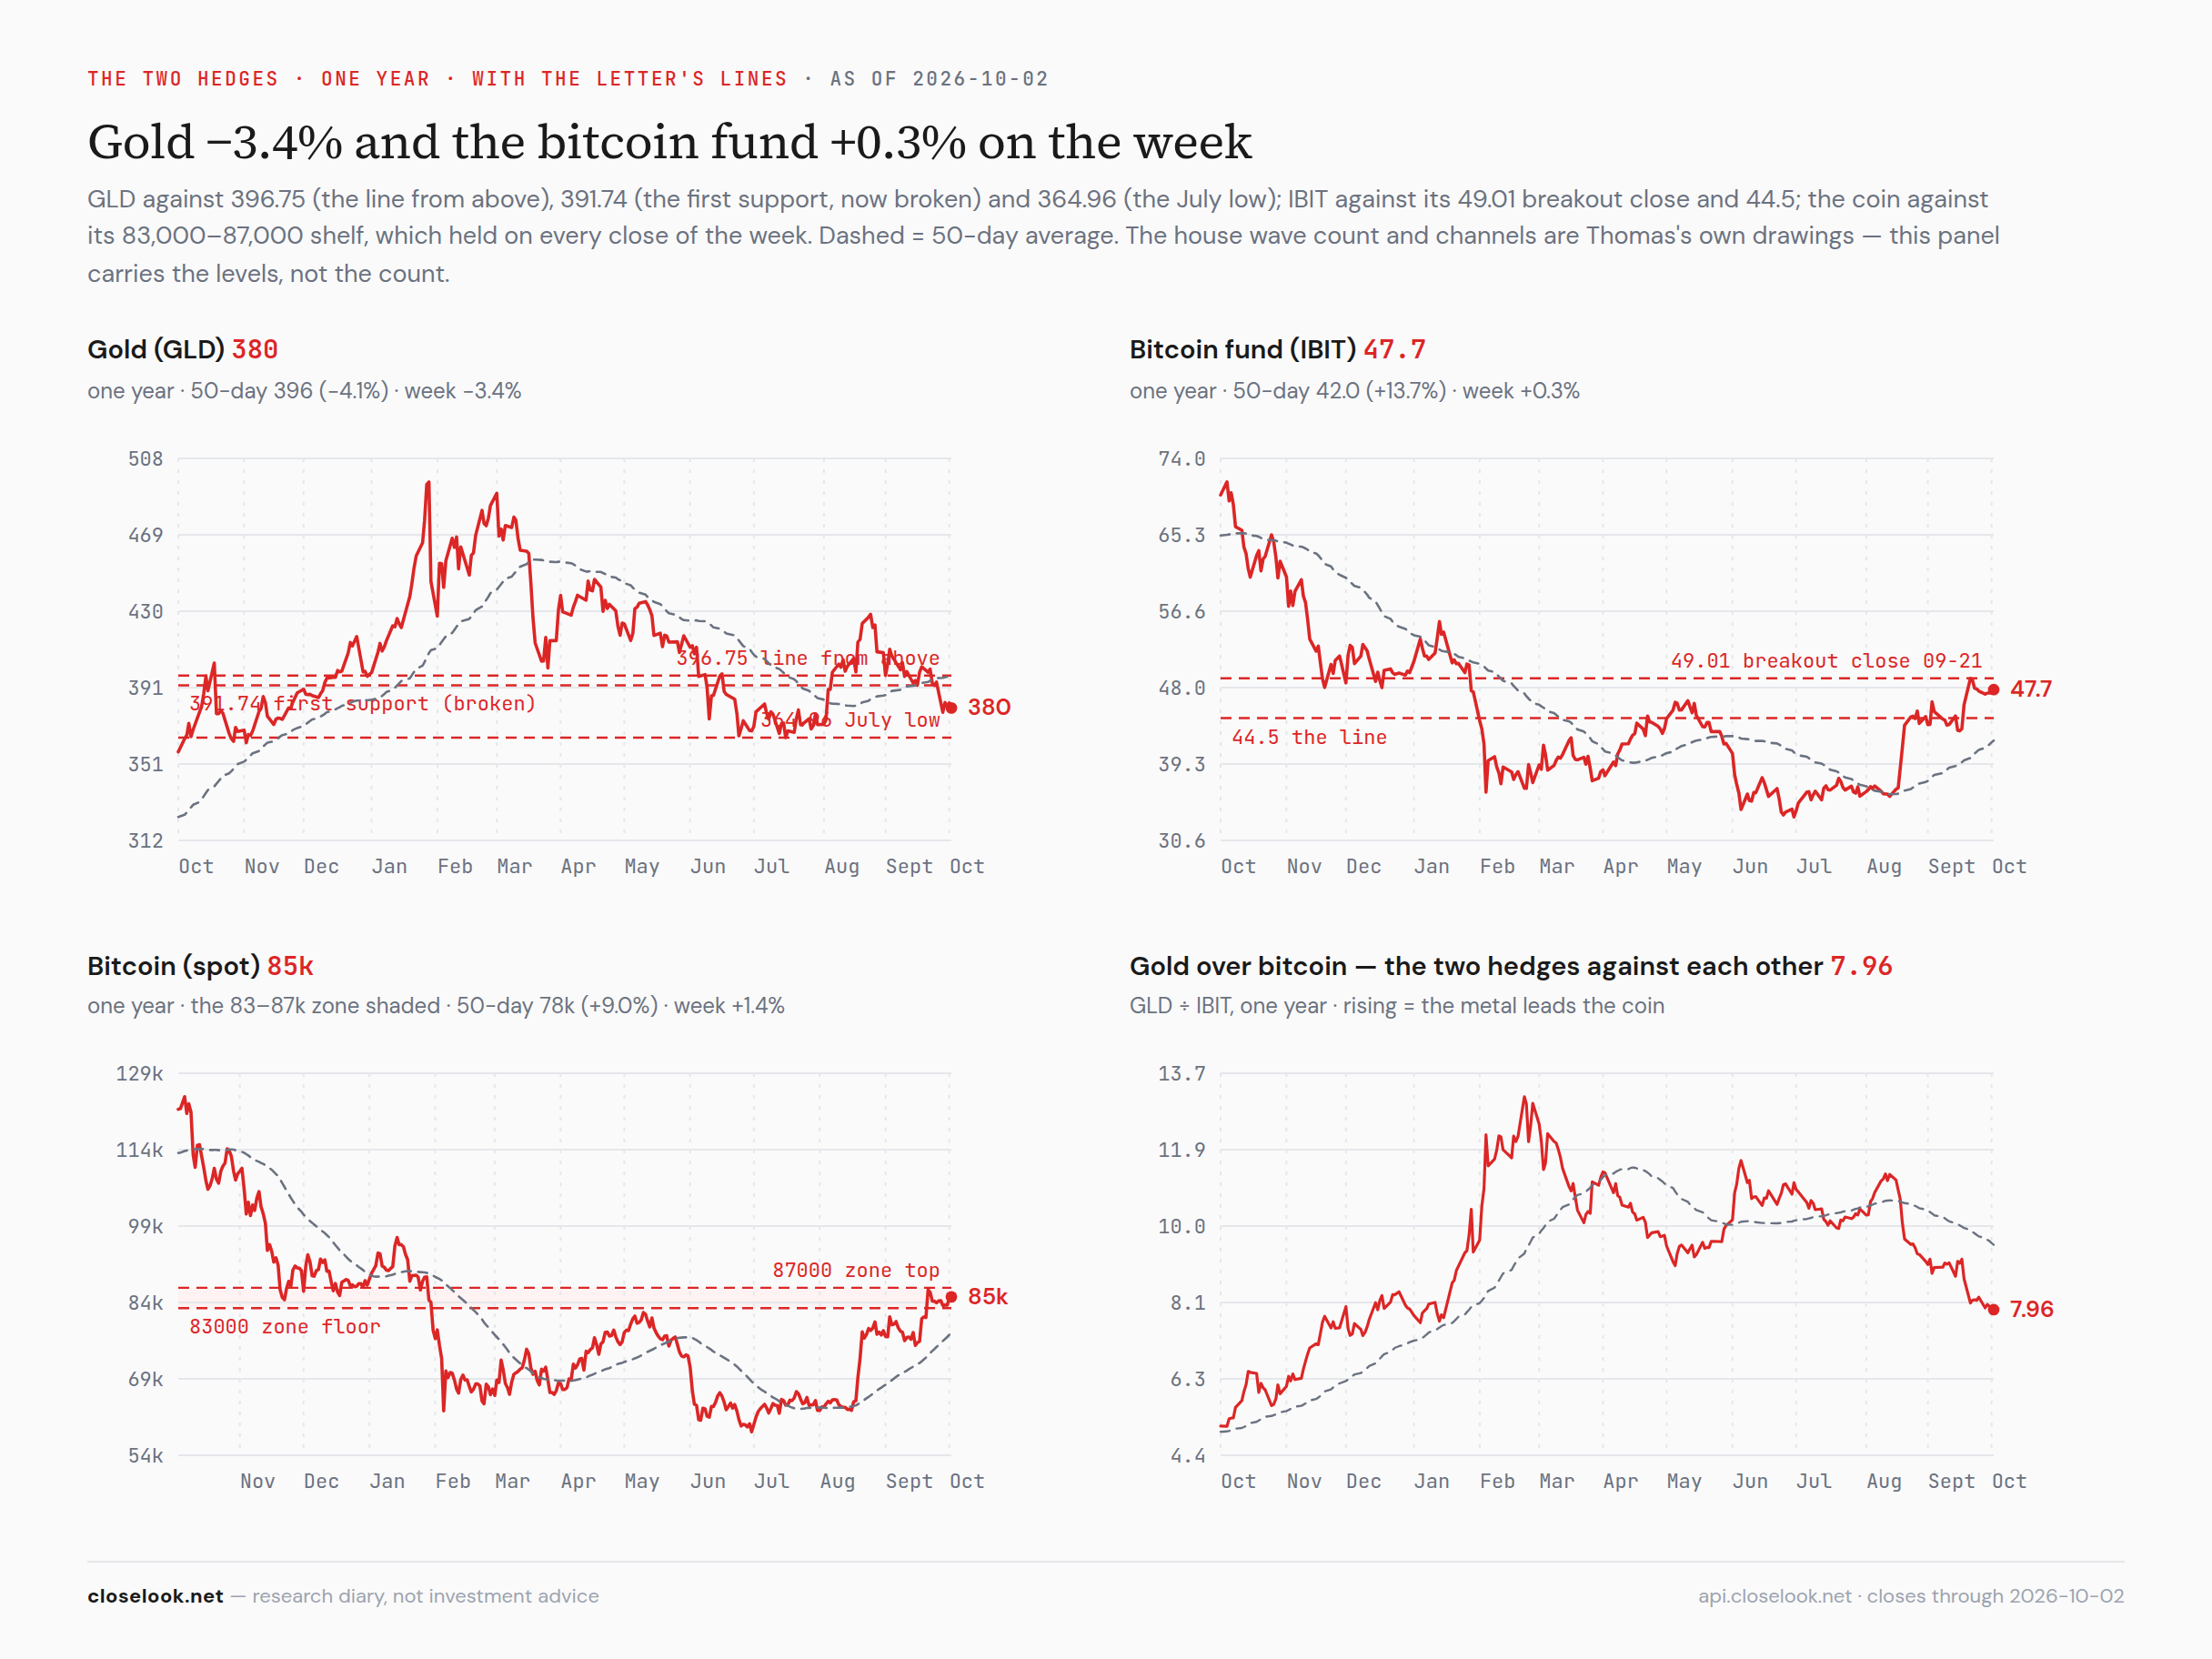
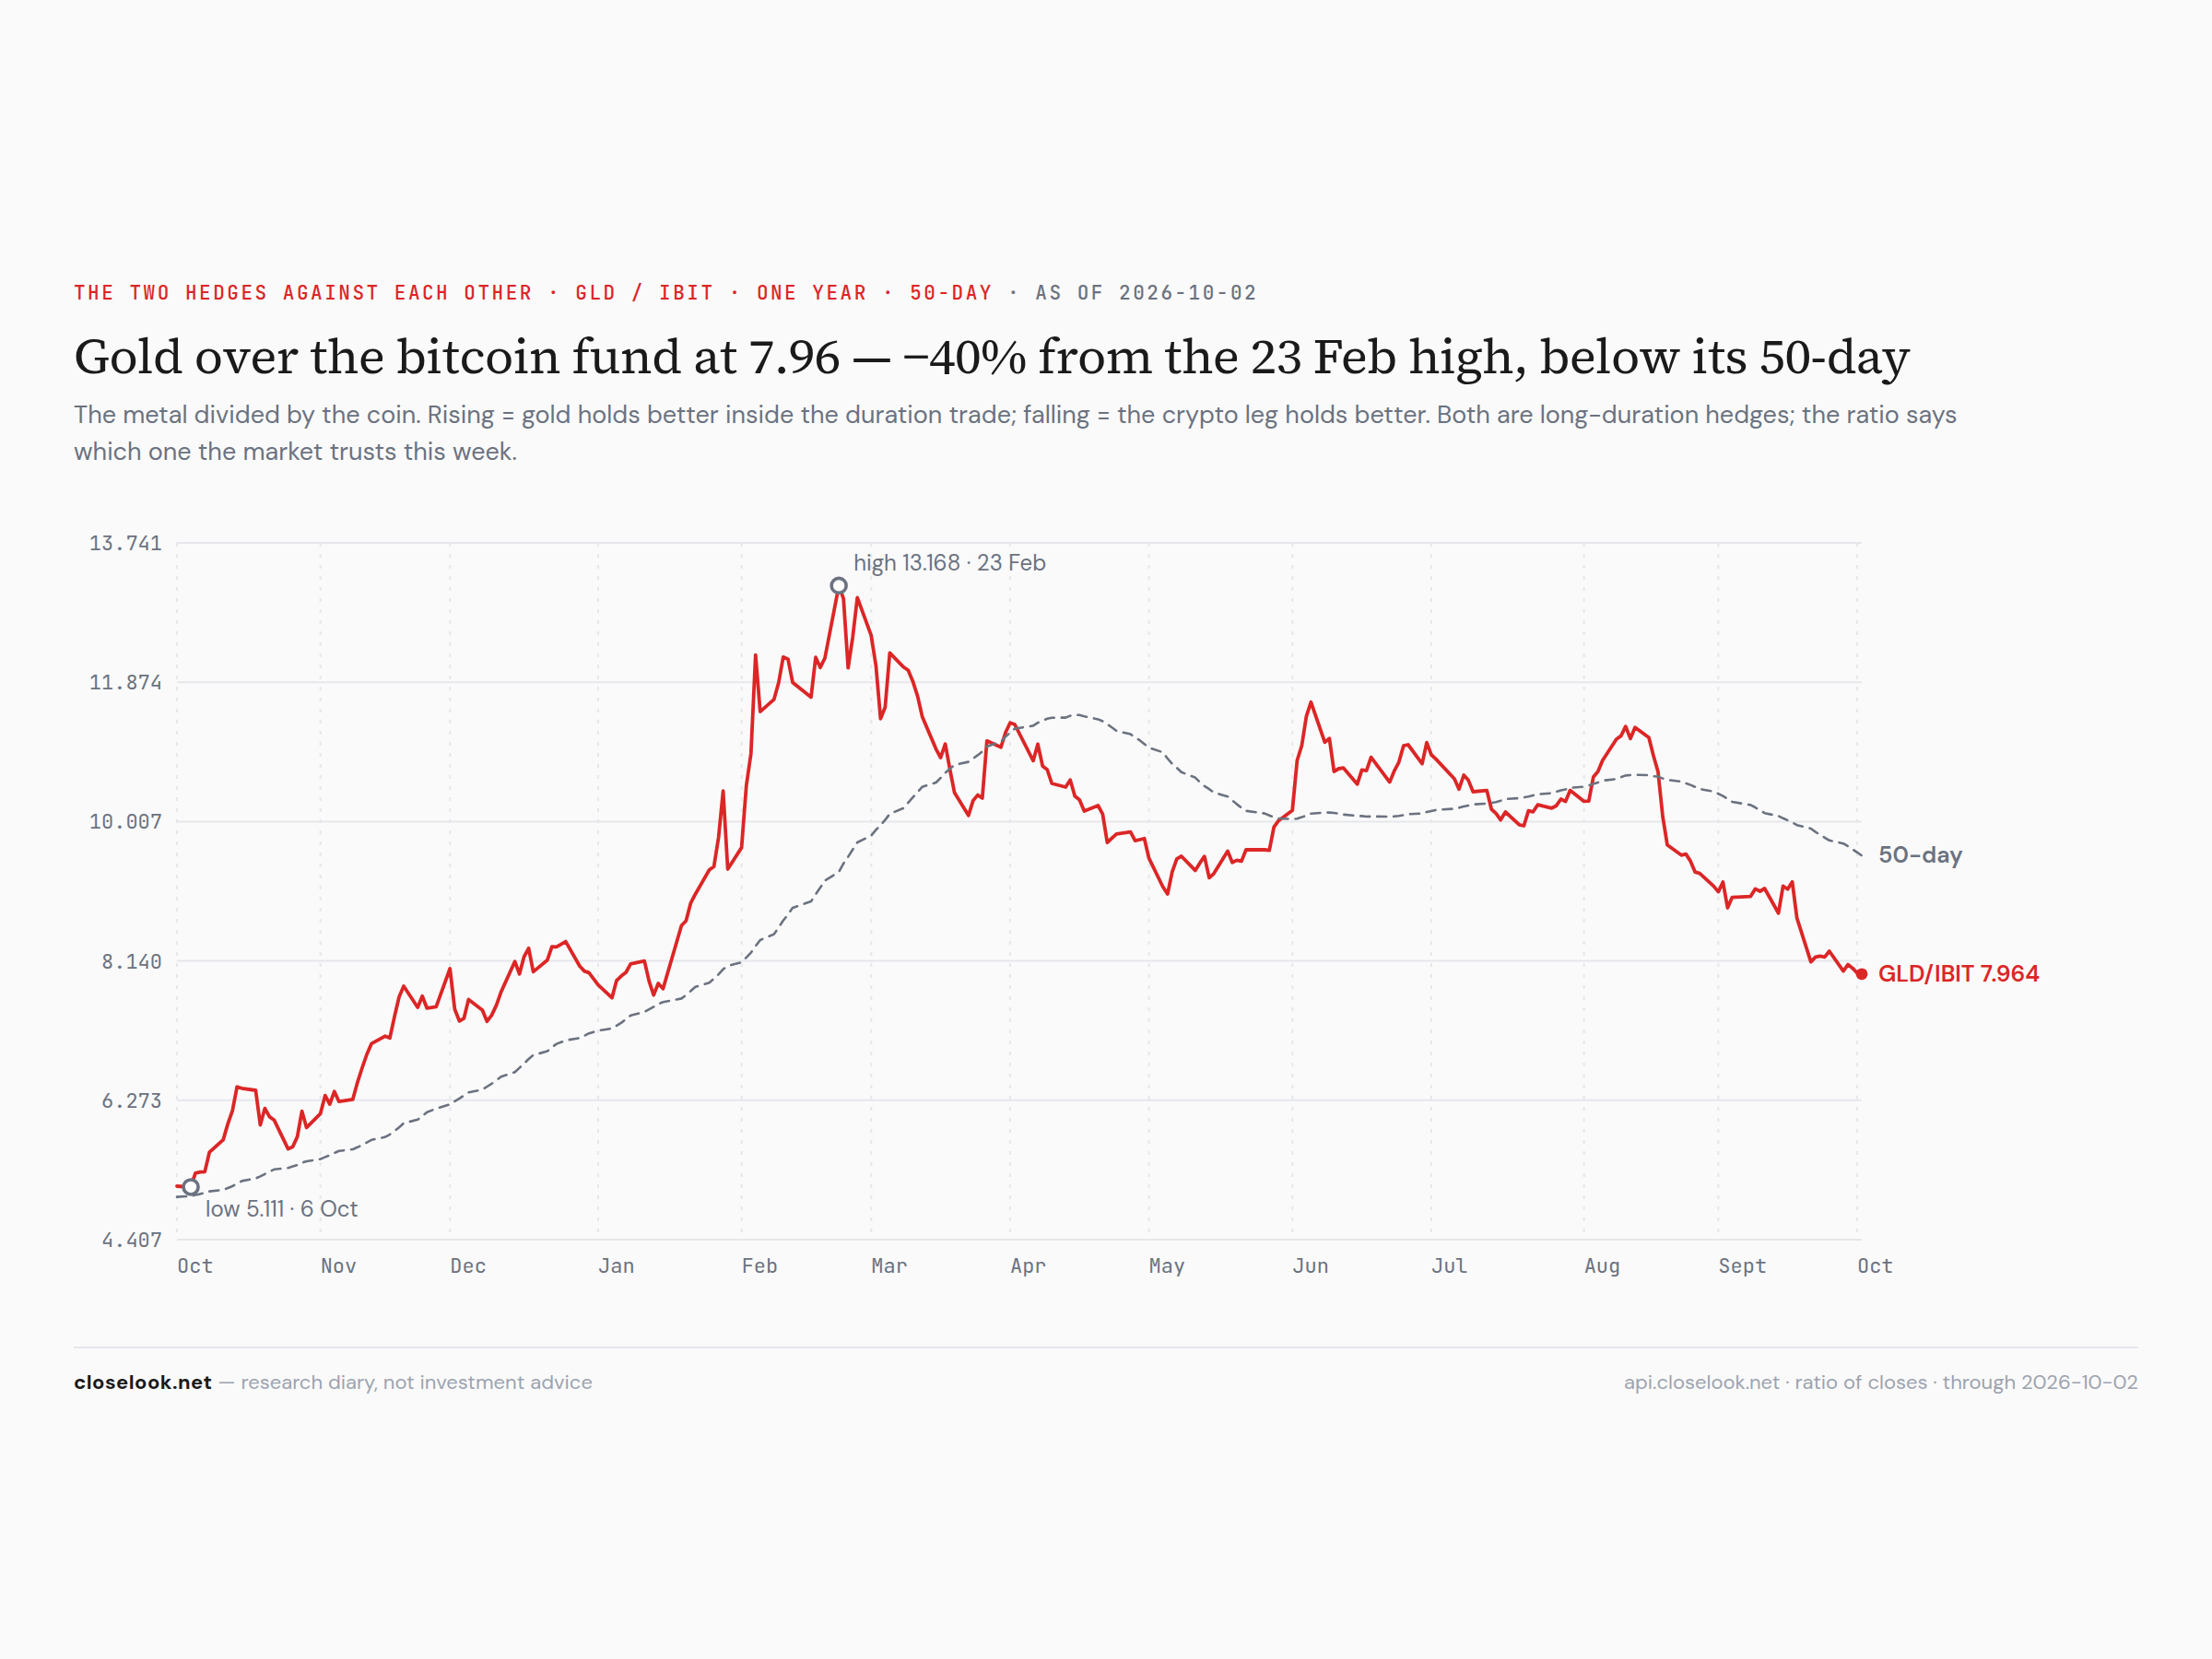
The hard assets — the coin held its shelf, the metal lost its floor. Bitcoin closed Friday at 85,206, +1.39%, with its lowest close of the week at 83,503 on Monday — above the 83,000 floor on every close. The week's range was 82,571 to 85,600: a consolidation on the old zone's ceiling, which is what a breakout that is going to hold usually does next. The fund closed 47.73, +0.34%. Gold did the opposite again: GLD −3.37% to 380.14, every close of the week under the 391.74 first support it broke last Thursday — Monday 377.91 after a 3.8% day — and now 4.0% above the July low of 364.96 and 23% under its January record. Silver fell 5.85%. A dollar at the high of the year and real yields at the high of the cycle are the textbook headwinds for both. The coin absorbed them; the metal did not.
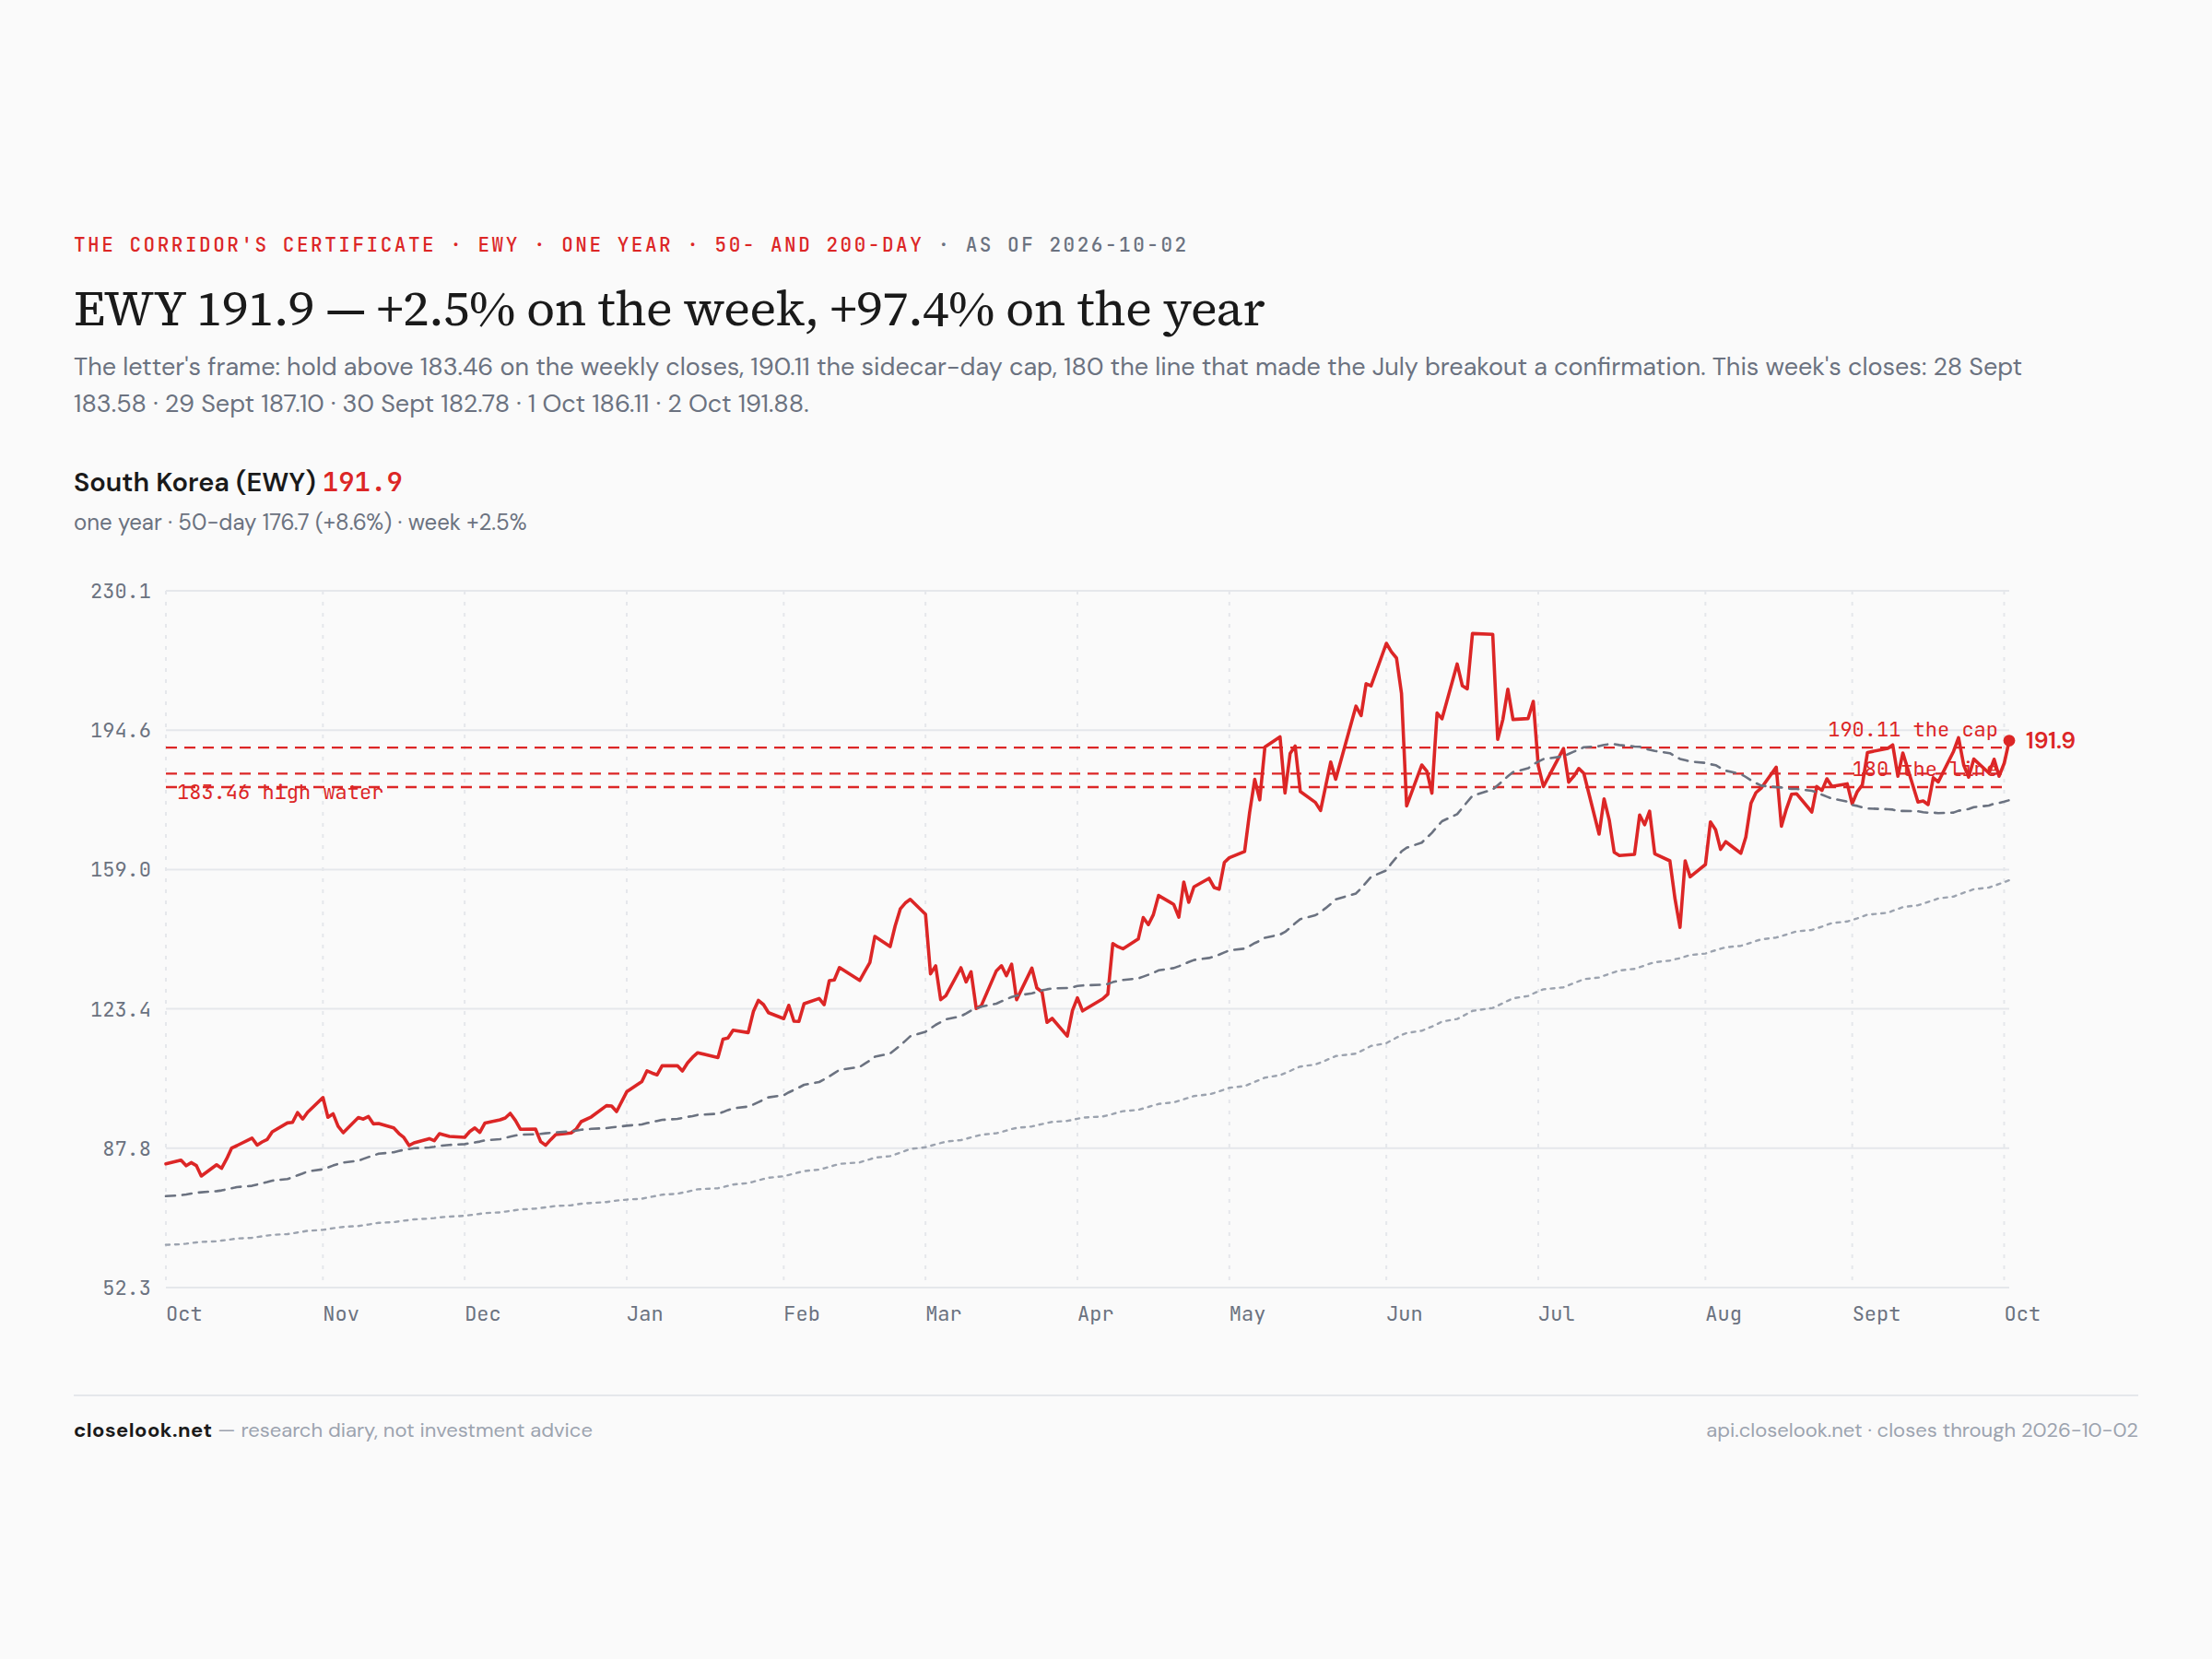
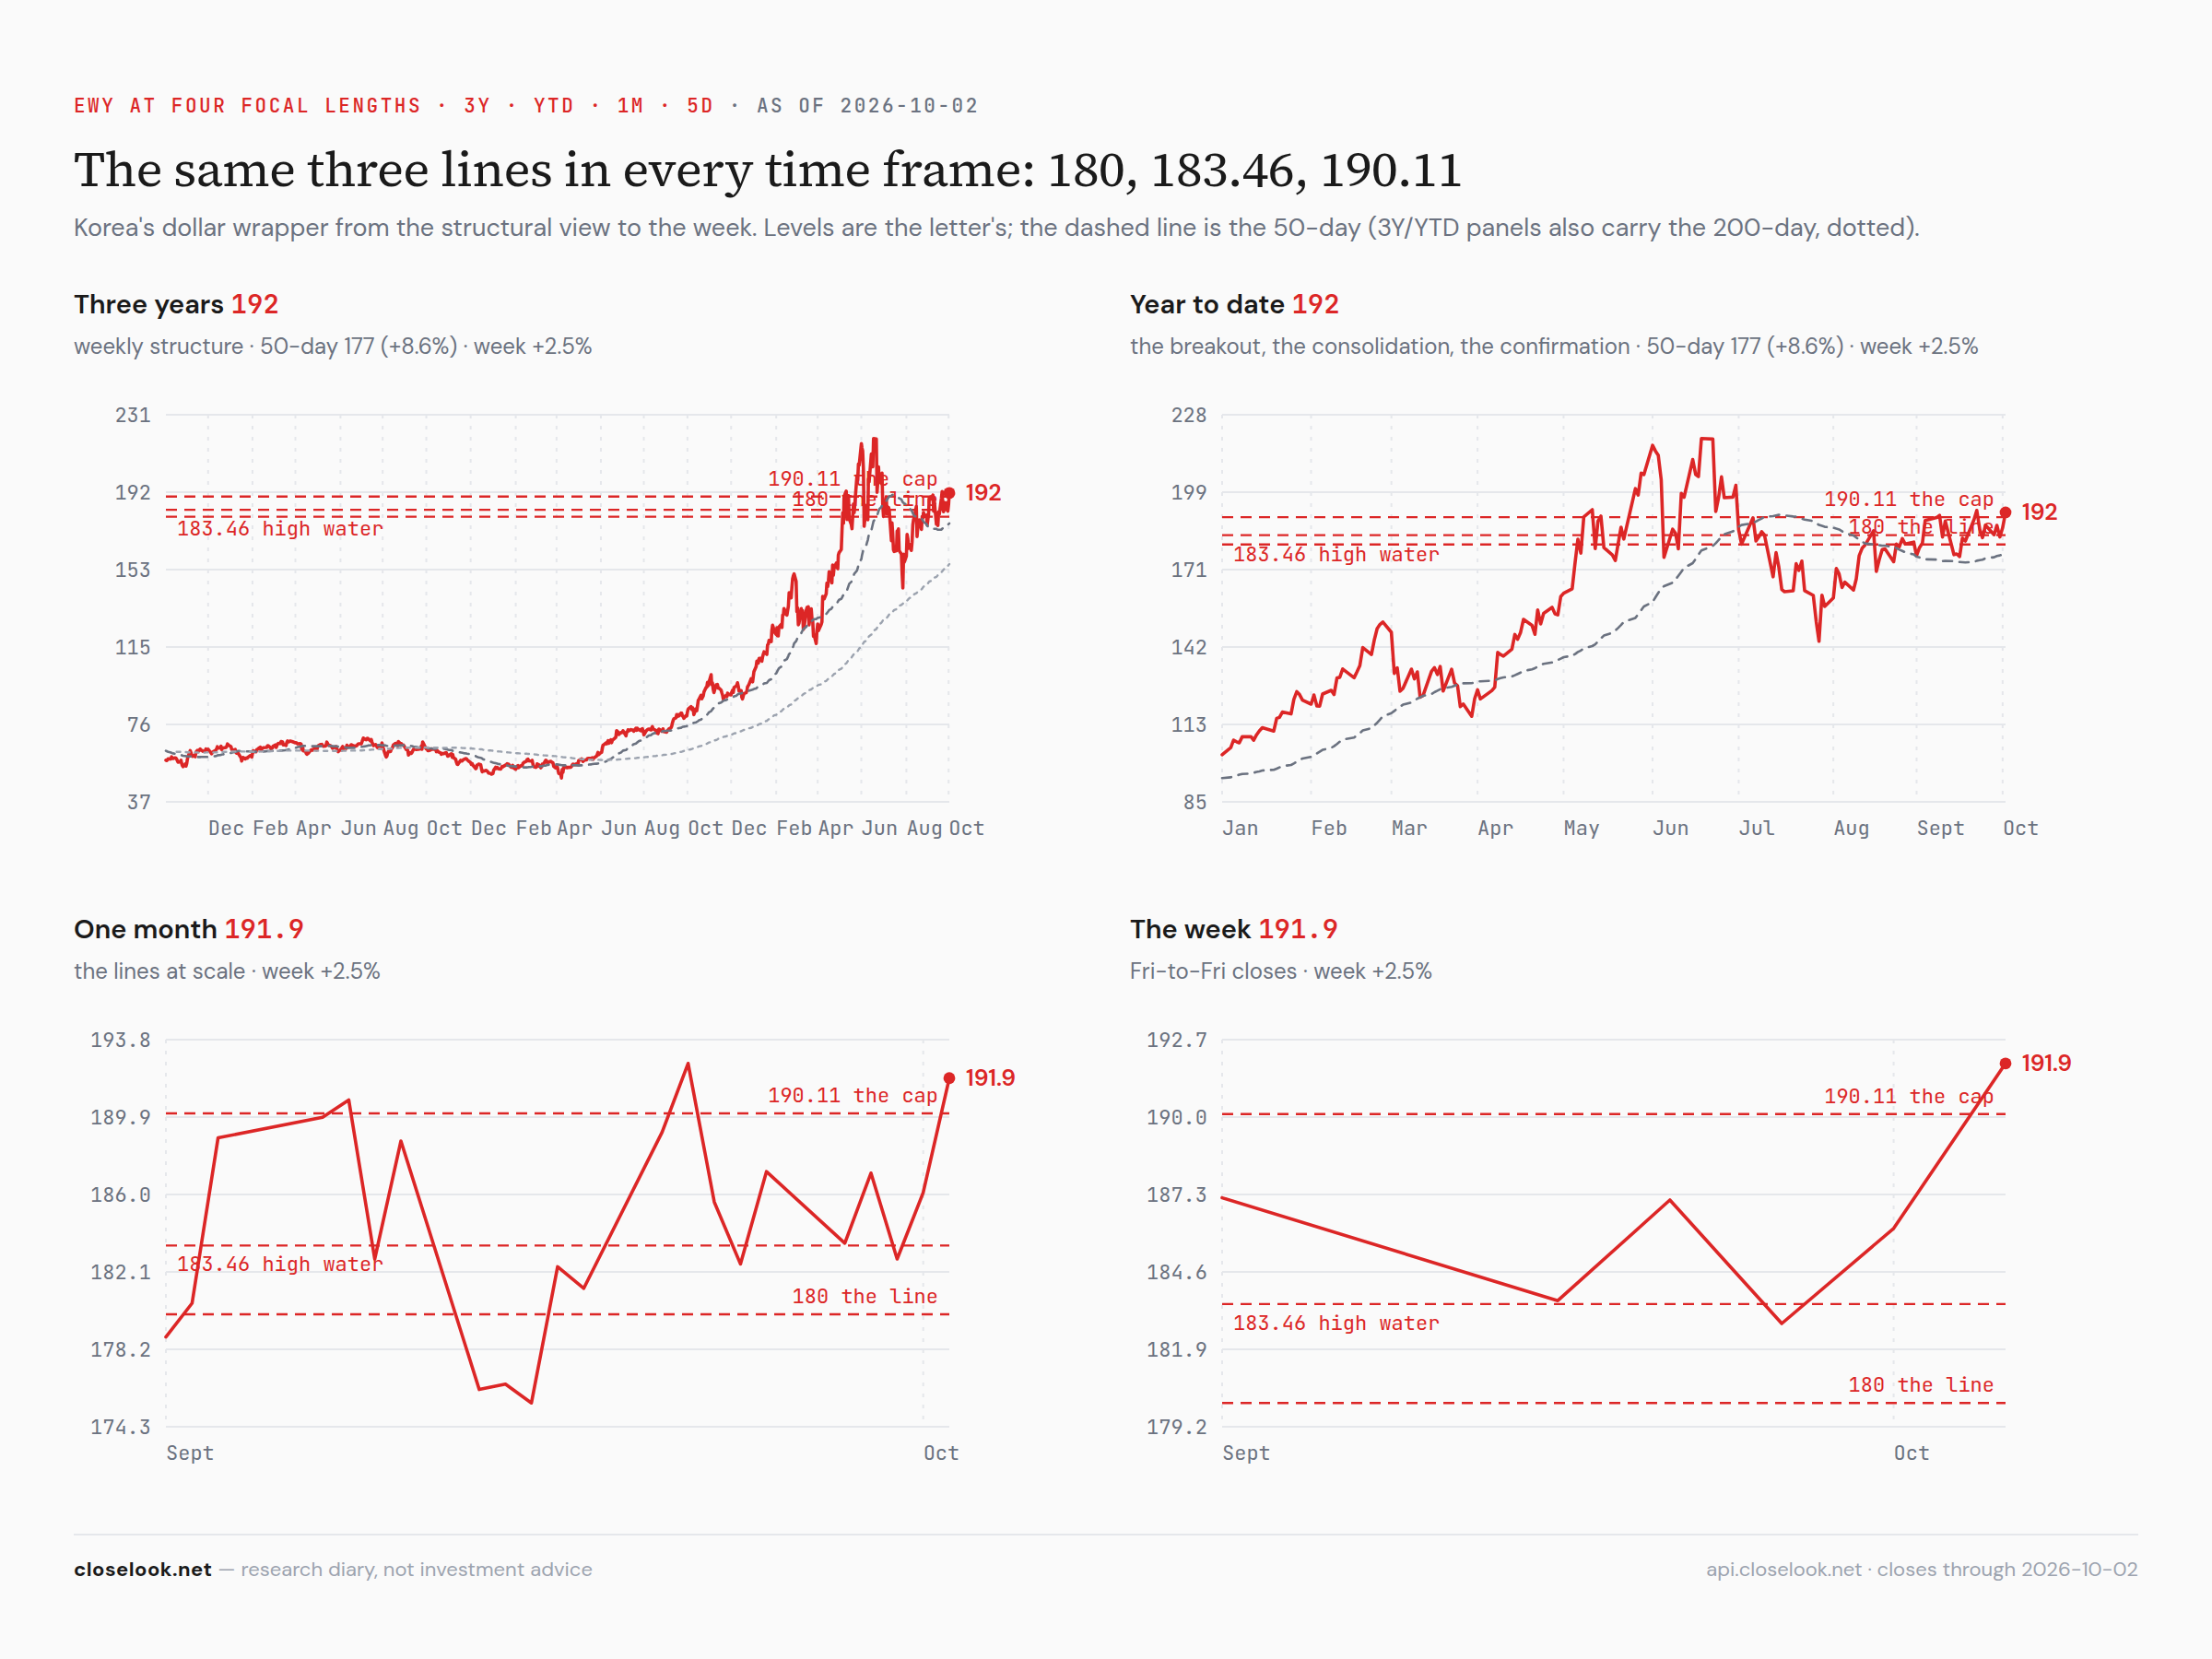
Seoul: through the cap. The fund walked 183.58 → 187.10 → 182.78 → 186.11 → 191.88 — and the weekly close is above the 190.11 cap for the first time. Last week's frame stated the rule: a weekly close above 190.11 turns the cap into the new floor and brings the June high of 219.20 back into view. That has now happened. EWY is 12.5% under the June high and +97% on the year — the best market on the board in 2026 by a distance.
Taiwan: a record with no ceiling above it. EWT closed 116.33, a record, after 114.17, 114.11, 112.90, 112.78 — two days under 113 before Friday's +3.1%. The Taiex closed at a record 48,476. Taiwan's market is now, in effect, a TSMC market, and TSMC reports its September sales next week (§4). The record goes into that number, not out of it.
Europe, the voting machine and the weighing machine — both voted no. Last week Europe's AI week was the equipment it sells to Asia. This week the equipment still rose — Euro-AI's semi-equipment layer +9.12% — but the market around it fell, and the euro with it. The voting machine sold the core and the havens; the weighing machine bought the Bund and sold the OAT. Europe has a chip-equipment industry worth owning and a sovereign-credit problem worth avoiding, and this week they moved in opposite directions.
The macro print. Three numbers: core inflation 0.2%, payrolls 29,000, the ten-year 5.28%. The first two argued for lower rates; the third did not follow. That leaves the long end trading on supply and credit, not on the Fed, and it leaves the dollar trading on the ranking of economies, not on the next cut. For the equity map it means one thing: the market is paying for growth it can see — Micron's record, Accenture's bookings, the chip exporters — and selling everything that only had the rate to offer.
Hold both halves. The equity map resolved into three speeds — America's tech and Asia's chips at records, Europe and India down. The funding tells resolved down again — the long end at a new low every day, the dollar at a high, gold through its floor. Last week the equities rose through the bond market. This week they split along it: the markets with growth rose, the markets that depend on cheap money did not.
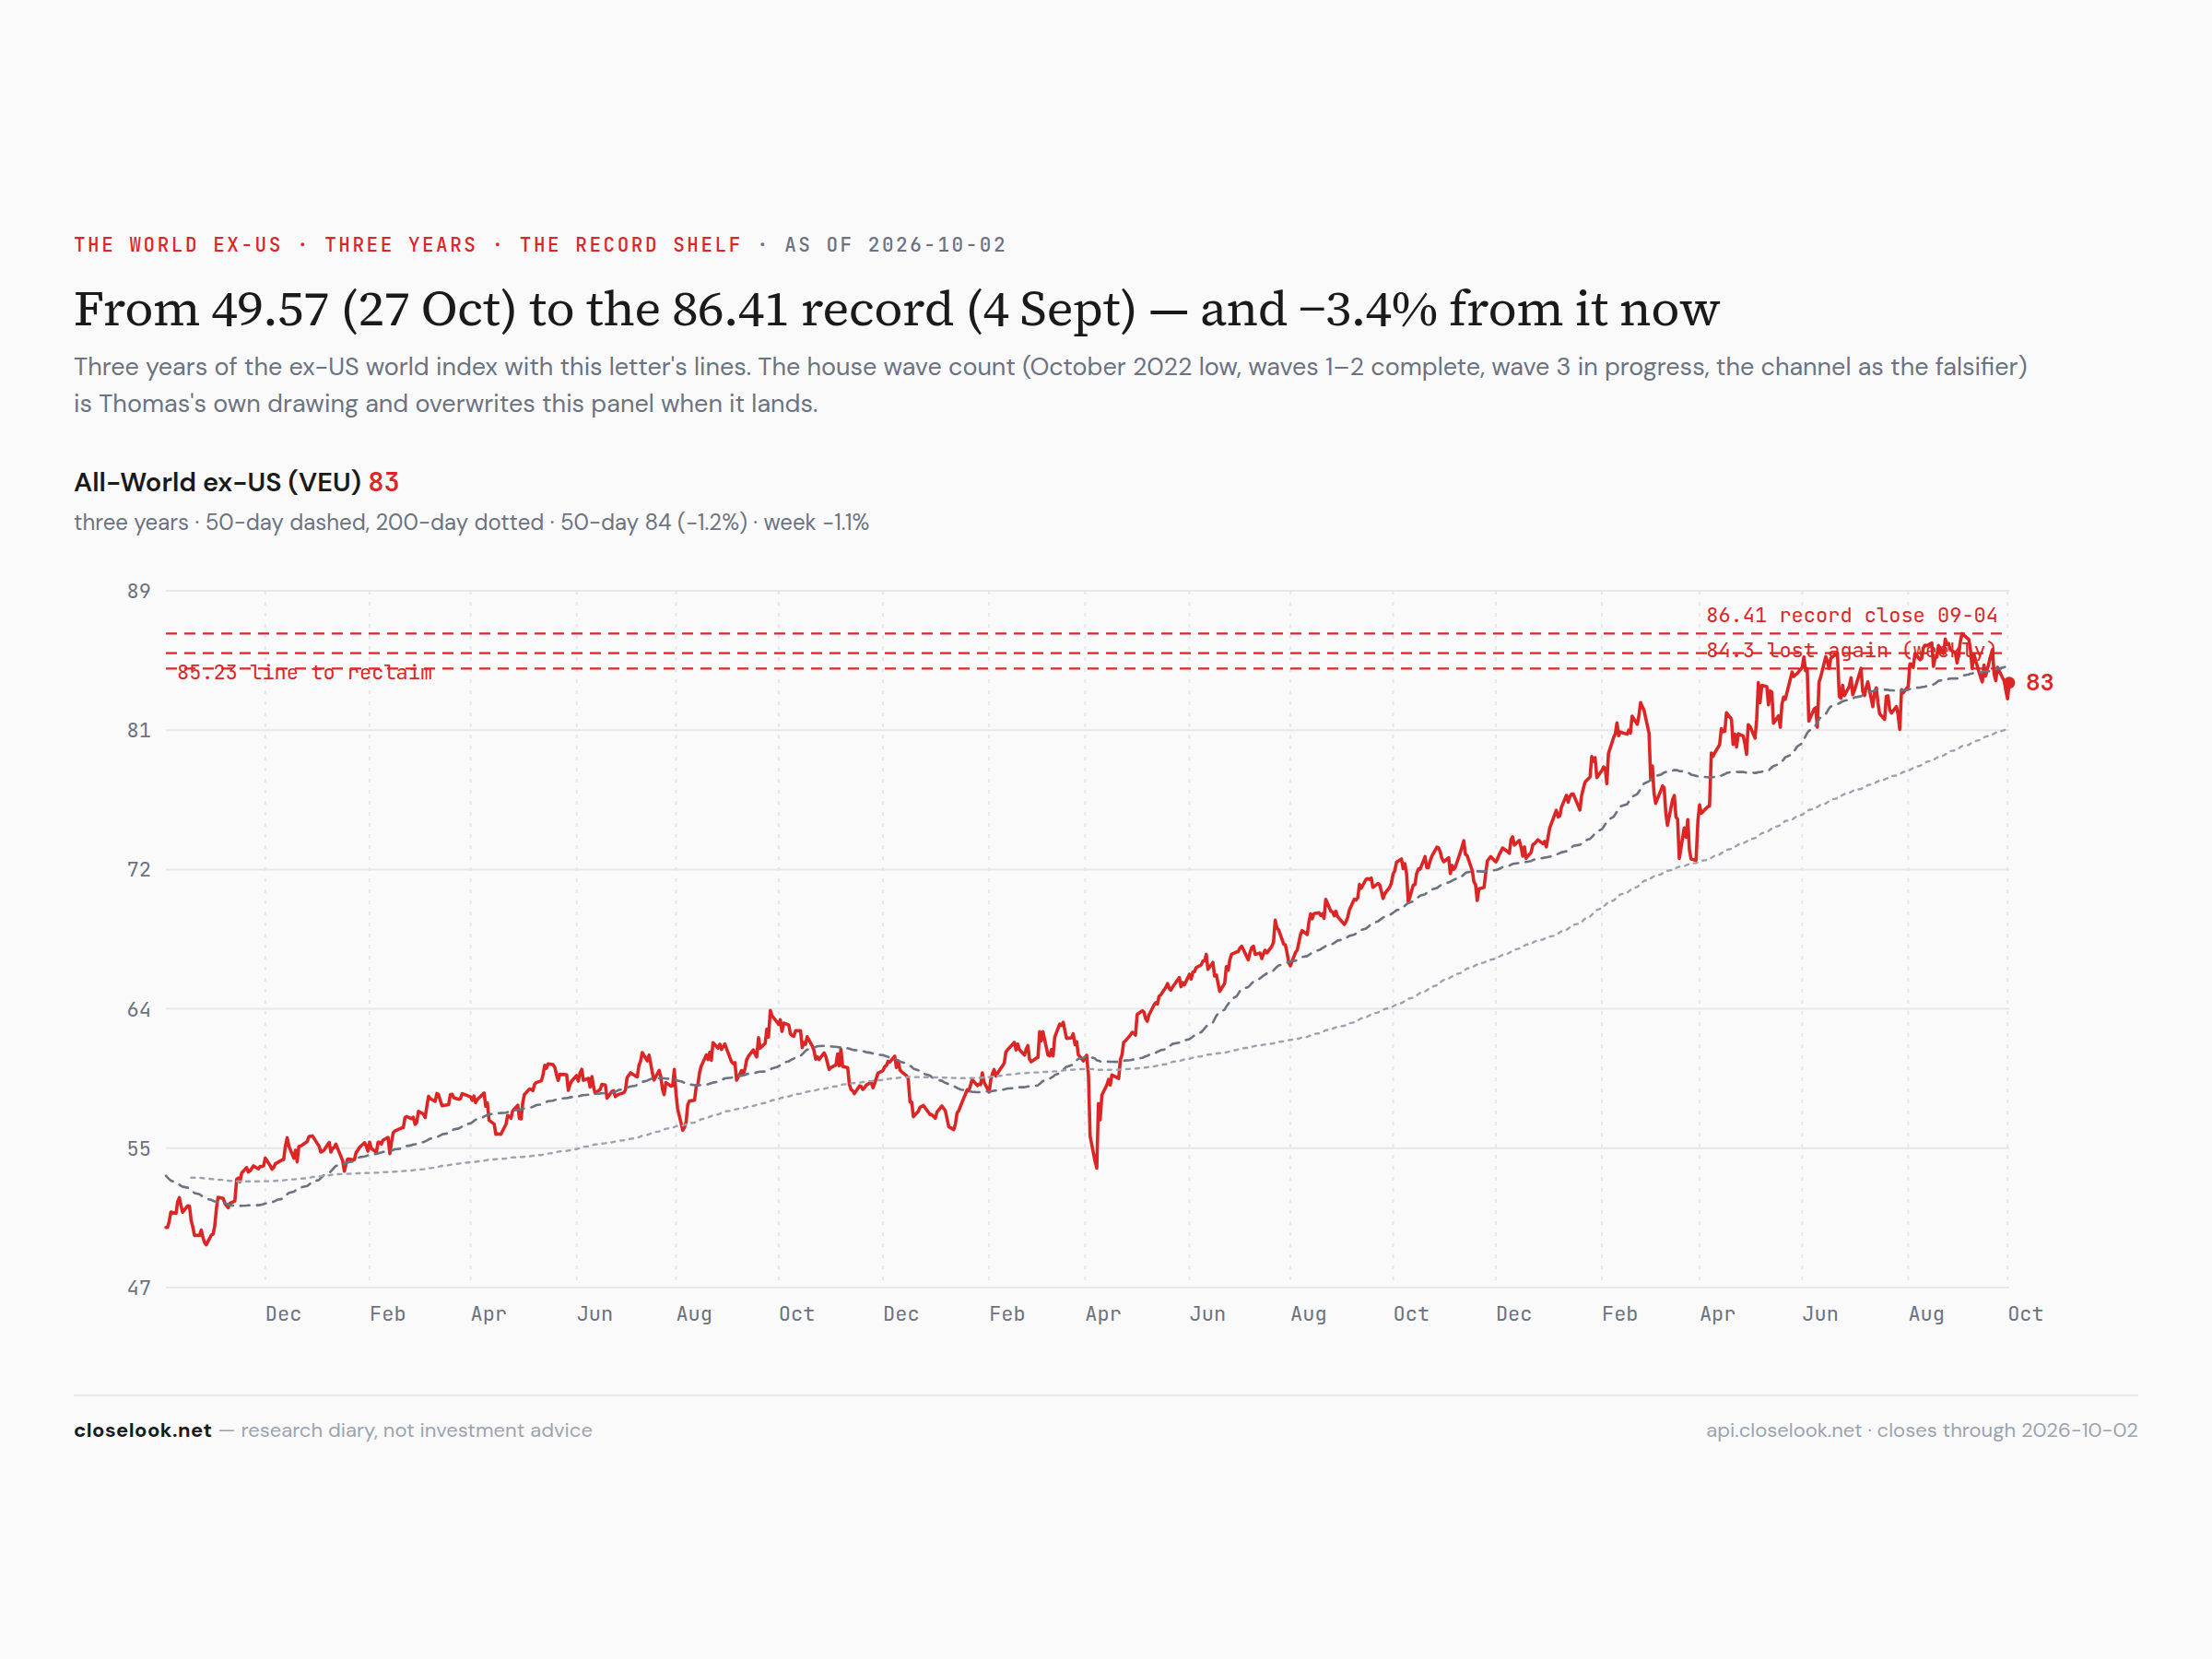
The structural read — the wave count, five years up, unchanged. From the October 2022 low the house count on the world ex-US reads waves 1 and 2 complete and wave 3 still progressing. It is falsified by a weekly close under 82.85 and confirmed by a weekly close above 86.41. Thursday's 82.48 was a daily close under the line; Friday's 83.45 put the week back above it. The count holds on the rule it was given — by 60 cents.
3 · The Outlook
The three-index read — the builder doubled again, the applications fell again. We read the three together because they are three stages of one spend: capex (Rubin Build-Out, what gets built), opex (Agentic Ecosystem, what it costs to run), applications (Agentic Winners, what gets sold on top).
Capex +5.87% on the week to 2,172.09, thirty-one of thirty-six sub-indices green, +111.3% on the year. Opex +3.25% to a record 1,738.49, +76.2%. Applications −1.06% and −8.1%. The builder rose every day of the week — 2,024.39, 2,055.57, 2,066.04, 2,112.51, 2,172.09 — through the quarterly reset of its weights on Wednesday. The opex index closed the week at its high.
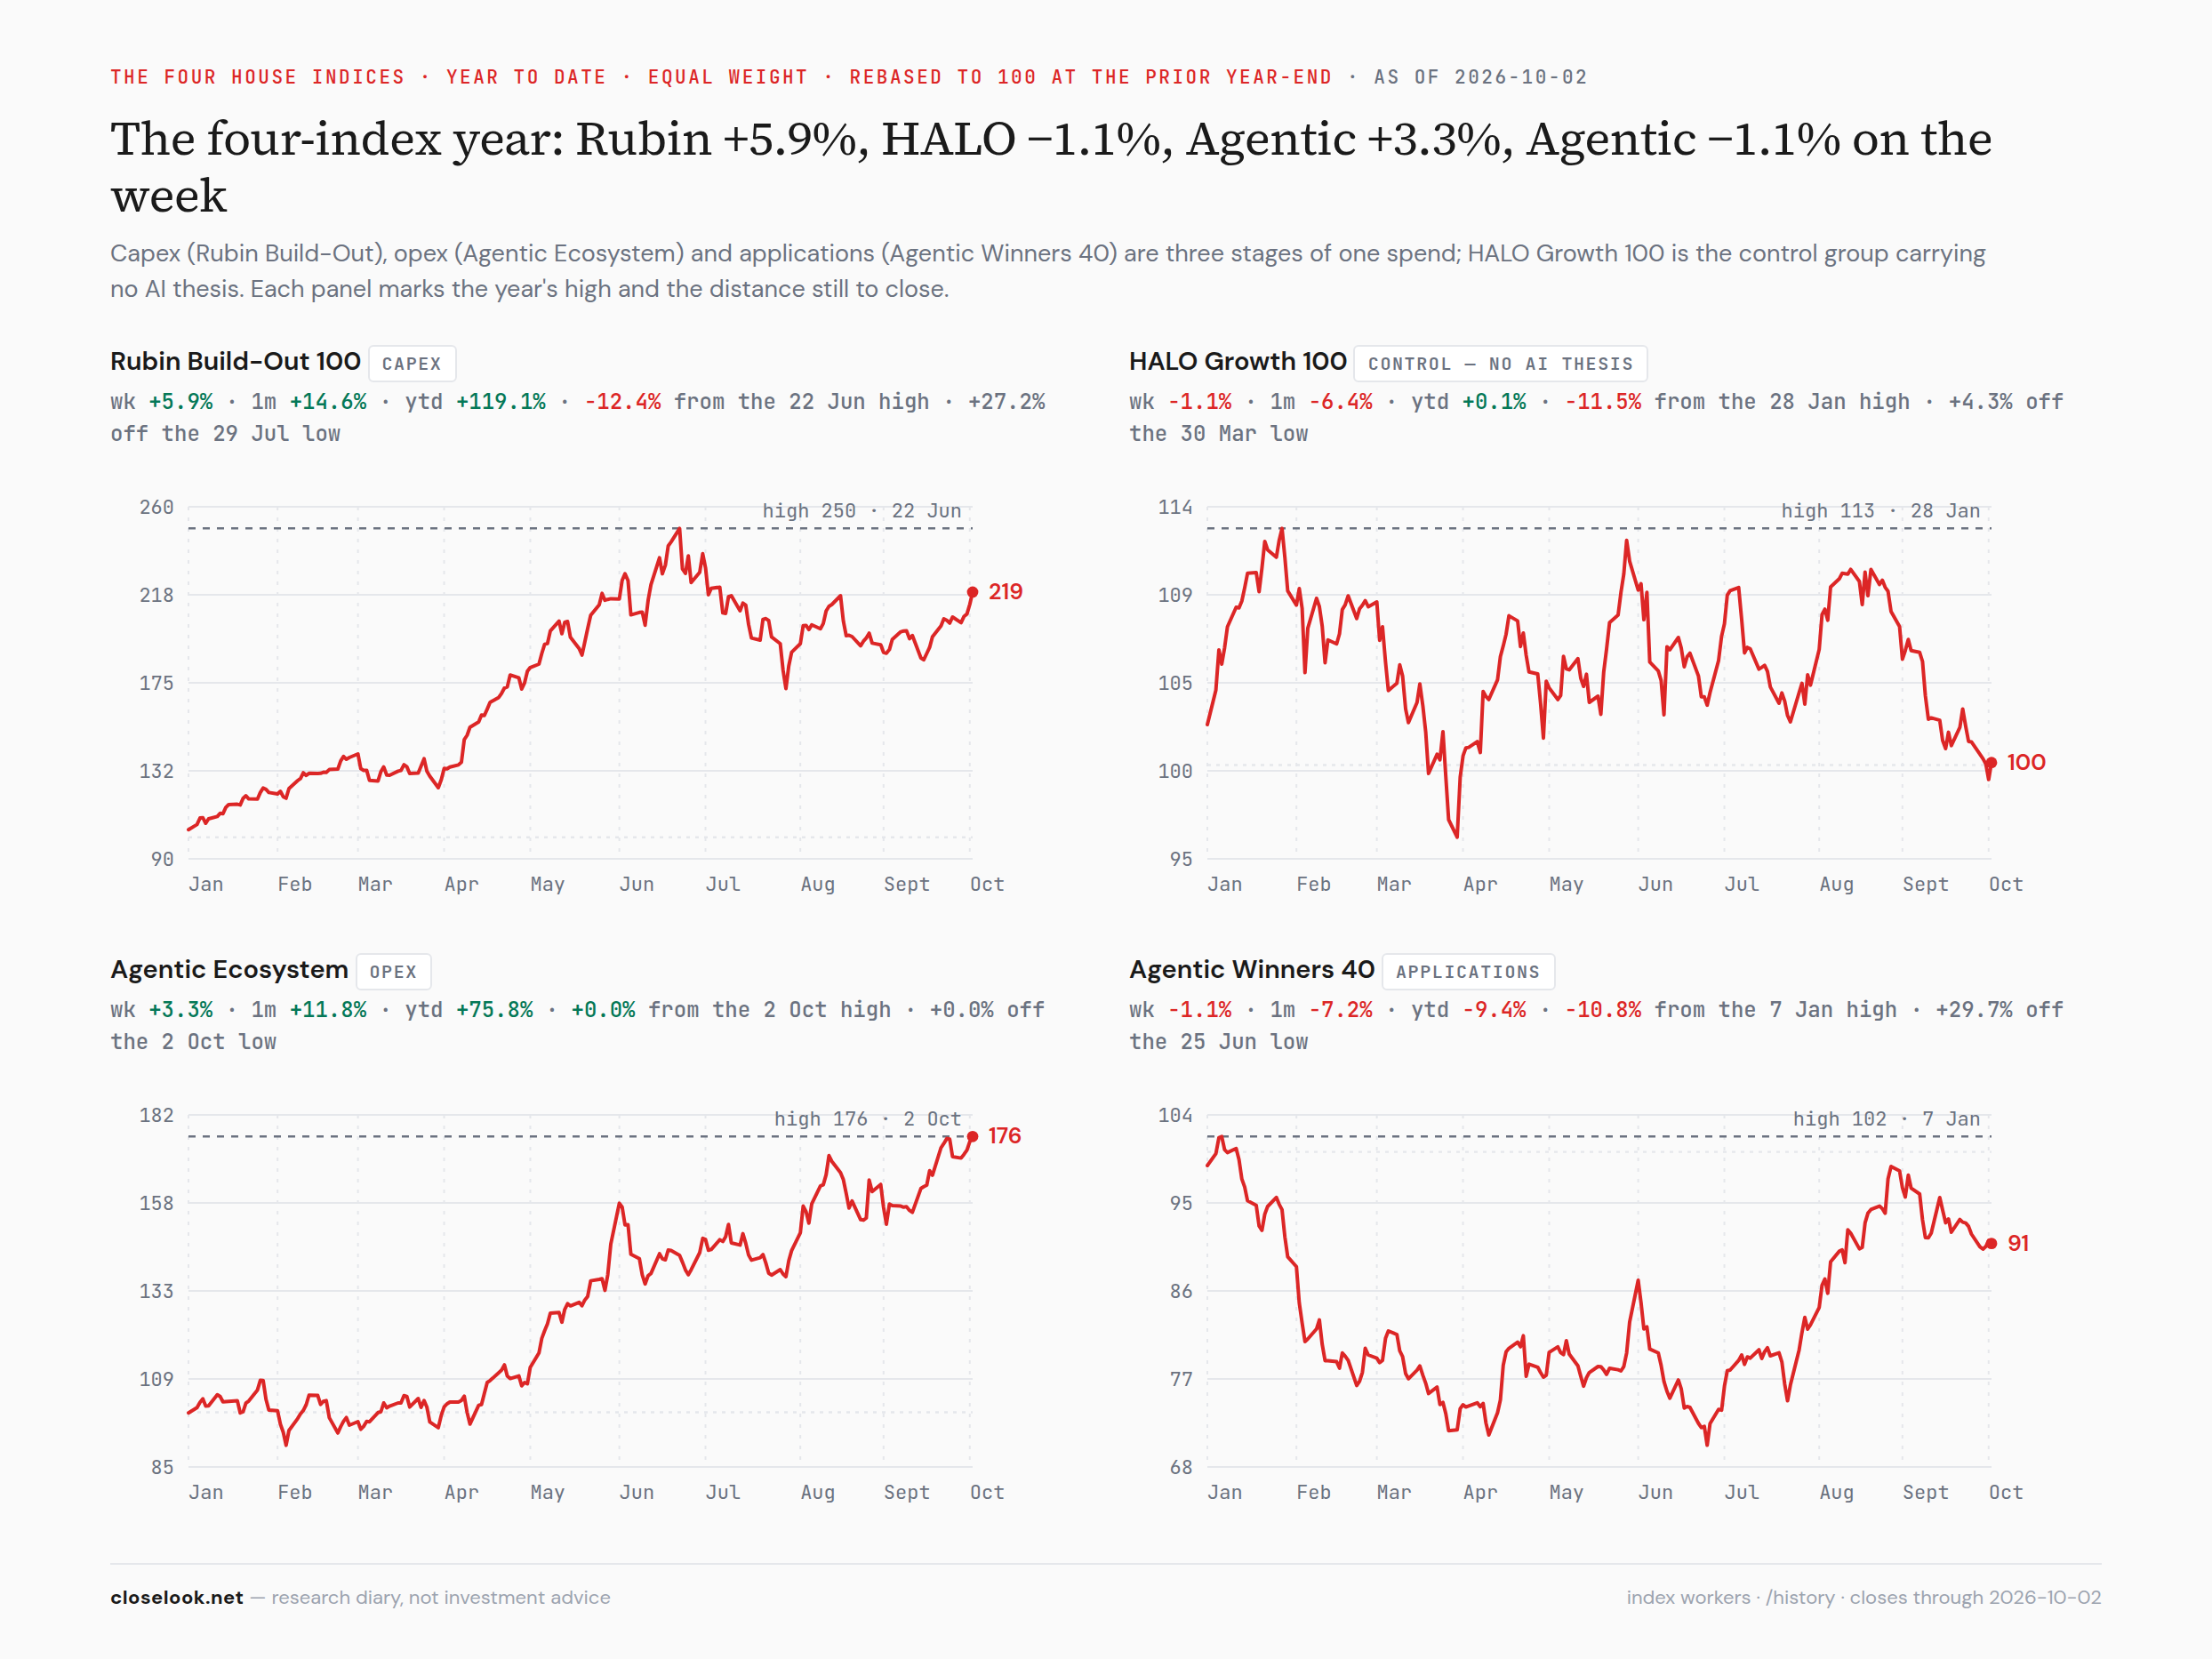
The control group fell while the builder rose six percent. HALO — our growth index carrying no AI thesis — fell 1.13%, −2.1% on the year. Growth without AI went down; growth with AI's build-out is up 111%. The gap on 2026 is 113 points. That is the same gap, at index altitude, as the one on the map between Taiwan and India.
Read the windows together. On the year capex leads: +111.3% against +76.2% against −8.1%. On the month capex and opex are level: +14.6% against +11.8%, applications −7.2%. Inside applications only one sub-index of nine rose this week — the control plane, +0.61%; the megacap gateway, which carried the platforms' agent week a fortnight ago, slipped 0.20%. The AI economy is still being paid for at the bottom of the stack and in the middle; at the top it is not yet.
The distances to the highs. Opex at its record. Capex 12.4% under its June 22 high and 27.2% above its July 29 low. Applications 10.8% under its January high. HALO 11.5% under January.
Inside capex: the materials and the testers. The best lines: advanced materials +13.88%, connectivity and materials +10.80%, fab subsystems +10.59%, machine vision +10.26%, testing and metrology +10.04%. The slowest: storage −2.60%, thermal −2.60%, the chip architects −2.50%, HBM memory −0.72%, AI factory systems −0.24%. The memory names rested in Micron's record week; the people who supply the fabs did the running.
Inside opex: the gateways and the security layer. Nine of fourteen green: runtime and API gateways +6.66%, agentic security +5.20%, execution +4.84%, govern and secure +4.67%, data and memory +4.27%. The red five: foundation models −1.93%, compute operators −1.10%, Europe's constituents −0.97%, Asia's −0.74%, substrate flat.
Euro-AI, for the ladder's sake. The sovereign-Europe index rose 2.72% to 1,320.04, +32.0% on the year, 5.1% under its June high — in a week the Europe fund fell 2.5%. Semi equipment and materials +9.12%, power, grid and cooling +2.02%, chip architecture and cloud +1.87%, enterprise AI +0.49%; medtech −0.33%, defense −0.77%, industrial AI −1.09%. Europe's AI index rose and Europe fell: the exception that proves this letter's map.
The regime gauge. The Money Temperature board closed the week at 57, from 62 — read as "mixed / transitional", the middle of neutral and, by its own construction, not a signal. The instruments: the dollar 75, bitcoin 65, the Nasdaq 100 64, the S&P 60, emerging markets 60, the world ex-US 53, the long bond 40, gold 37. The dollar hottest, gold coldest — the week on one gauge.
4 · What May Lie Ahead
The fourth quarter — stay home, because AI lives there. This letter's expectation for the rest of 2026, stated so it can be scored: the map that formed this quarter continues into the fourth. America's technology and Asia's chip corridor lead; mainland Europe, Switzerland, Britain and India trail; the dollar stays firm against the euro. The reason is not a call on any one economy. It is where the AI trade is listed: in America's platforms and chip designers, in Taiwan's and Korea's foundries and memory, in Japan's equipment makers. A global portfolio owns less of all of that than a portfolio that stays home in America and adds the corridor — and in 2026 that difference has been the whole return.
The season — strong from here, with one uncertain stretch first. Seasonally the fourth quarter is the strongest of the year for US equities, and it starts now. This letter's expectation: positive for the US to year-end. The stretch to watch is the next two weeks: uncertainty before the reporting season opens in mid-October — and before the midterm elections on November 3 — with the long bond at its low and the dollar at its high. The stance for that stretch is to buy dips, not to chase. A pullback in the first half of October into the first big reports is the ordinary shape of this calendar; it is the entry the season usually offers, not the end of it. Probability, not prophecy.
The bellwether — TSMC next week. TSMC publishes its September sales around 9–10 October, and its third-quarter results are on the vendor calendar for 15 October; ASML reports on 14 October. No company sits closer to the middle of this letter's map. Its sales are the AI build-out in one number — every accelerator, every custom chip, every high-end phone processor passes through its fabs — and Taiwan's market at a record is mostly its share price. A strong September confirms the corridor and the season into the reports; a soft one would be the first crack in the quarter's map, and it would show first in Taipei and Seoul. This letter treats it as the week's signal.
Levels and tripwires — VEU first, and the ladder slipped a rung. The marks: 86.41 the record close (September 4); 85.23 the line lost a month ago; 84.30 the line lost again on Friday's weekly close; 82.85 the structural line — under it on Thursday's daily close, above it on the weekly. Restated: 84.30 is resistance again, and a weekly close above it says this week was the visit; a weekly close under 82.85 ends the September episode on the wrong side and puts the count to the test. Below that, 82.48 is Thursday's low close.
The September frame — scored. Five weeks ago this letter stated its expectation so it could be scored: a consolidation with a decline of about five percent is what an ordinary September in this configuration delivers — the base case, not the bear case. The record came on September 4; the month closed on Wednesday at 82.97, 4.0% under it, and Thursday's low close was 4.5% under. Most of the base case, delivered — and inside it, the Nasdaq 100 at a record by the first Friday of October. The ordinary September came for the world index; it did not come for America's tech.
The long bond — 74 in view. TLT 77.48, 4.5% above 74, the October 2023 low, with five new lows in five sessions. Above, 81.2 is the line to reclaim on a weekly close. IEF 89.05, eight weeks under 93.17. Whether the fund reaches 74 before the midterms remains to be seen; a soft inflation reading and a weak jobs report did not stop it this week.
The dollar and the euro. The dollar fund's 28.96 is the year's high close; a weekly close above it extends the move. EUR/USD 1.1253, with 1.1248 the year's low close — a weekly close under it opens the euro's next leg lower. USDJPY 157.83: 156 the line from above, 160 the door, 155 the level that would bring the intervention talk back.
EWY 191.88 — the cap is the floor now. 190.11 the new floor, 183.46 the high water, 219.20 the June high. A weekly close back under 190.11 makes this week's close a false break; a hold opens the way to the June high. Seoul trades TSMC's number the same night Taipei does.
DRAM 61.78 — above 58 for a fourth week. 58 the line, 80.72 the June high. Micron's record quarter did not move the vehicle; the price is waiting for the next order book.
The four global sectors that decide the tape. Technology 151.94 — a record; the 149.74 June high is now the line from above. Industrials 192.47, 6.9% under August. Financials 126.43 — a fourth week under the 134.55 August line, 7.7% under the 137.00 record. Materials 107.80 — a sixth week under the 116.54 February line. Tech at a record with financials and materials sliding is a narrow tape; a weekly close for tech back under 149.74 would say the record was a reach.
The hard assets on the board. Bitcoin: 83,000 the floor, held on every close; 85,600 the week's high; 87,000 the close that extends the breakout. The fund: 49.01 the breakout close, 44.5 the line below. Gold: 391.74 now the line from above, 364.96 the July low below. Restated: a second week of gold under 391.74 makes the break the trend; a weekly close back above it calls the break a shake-out.
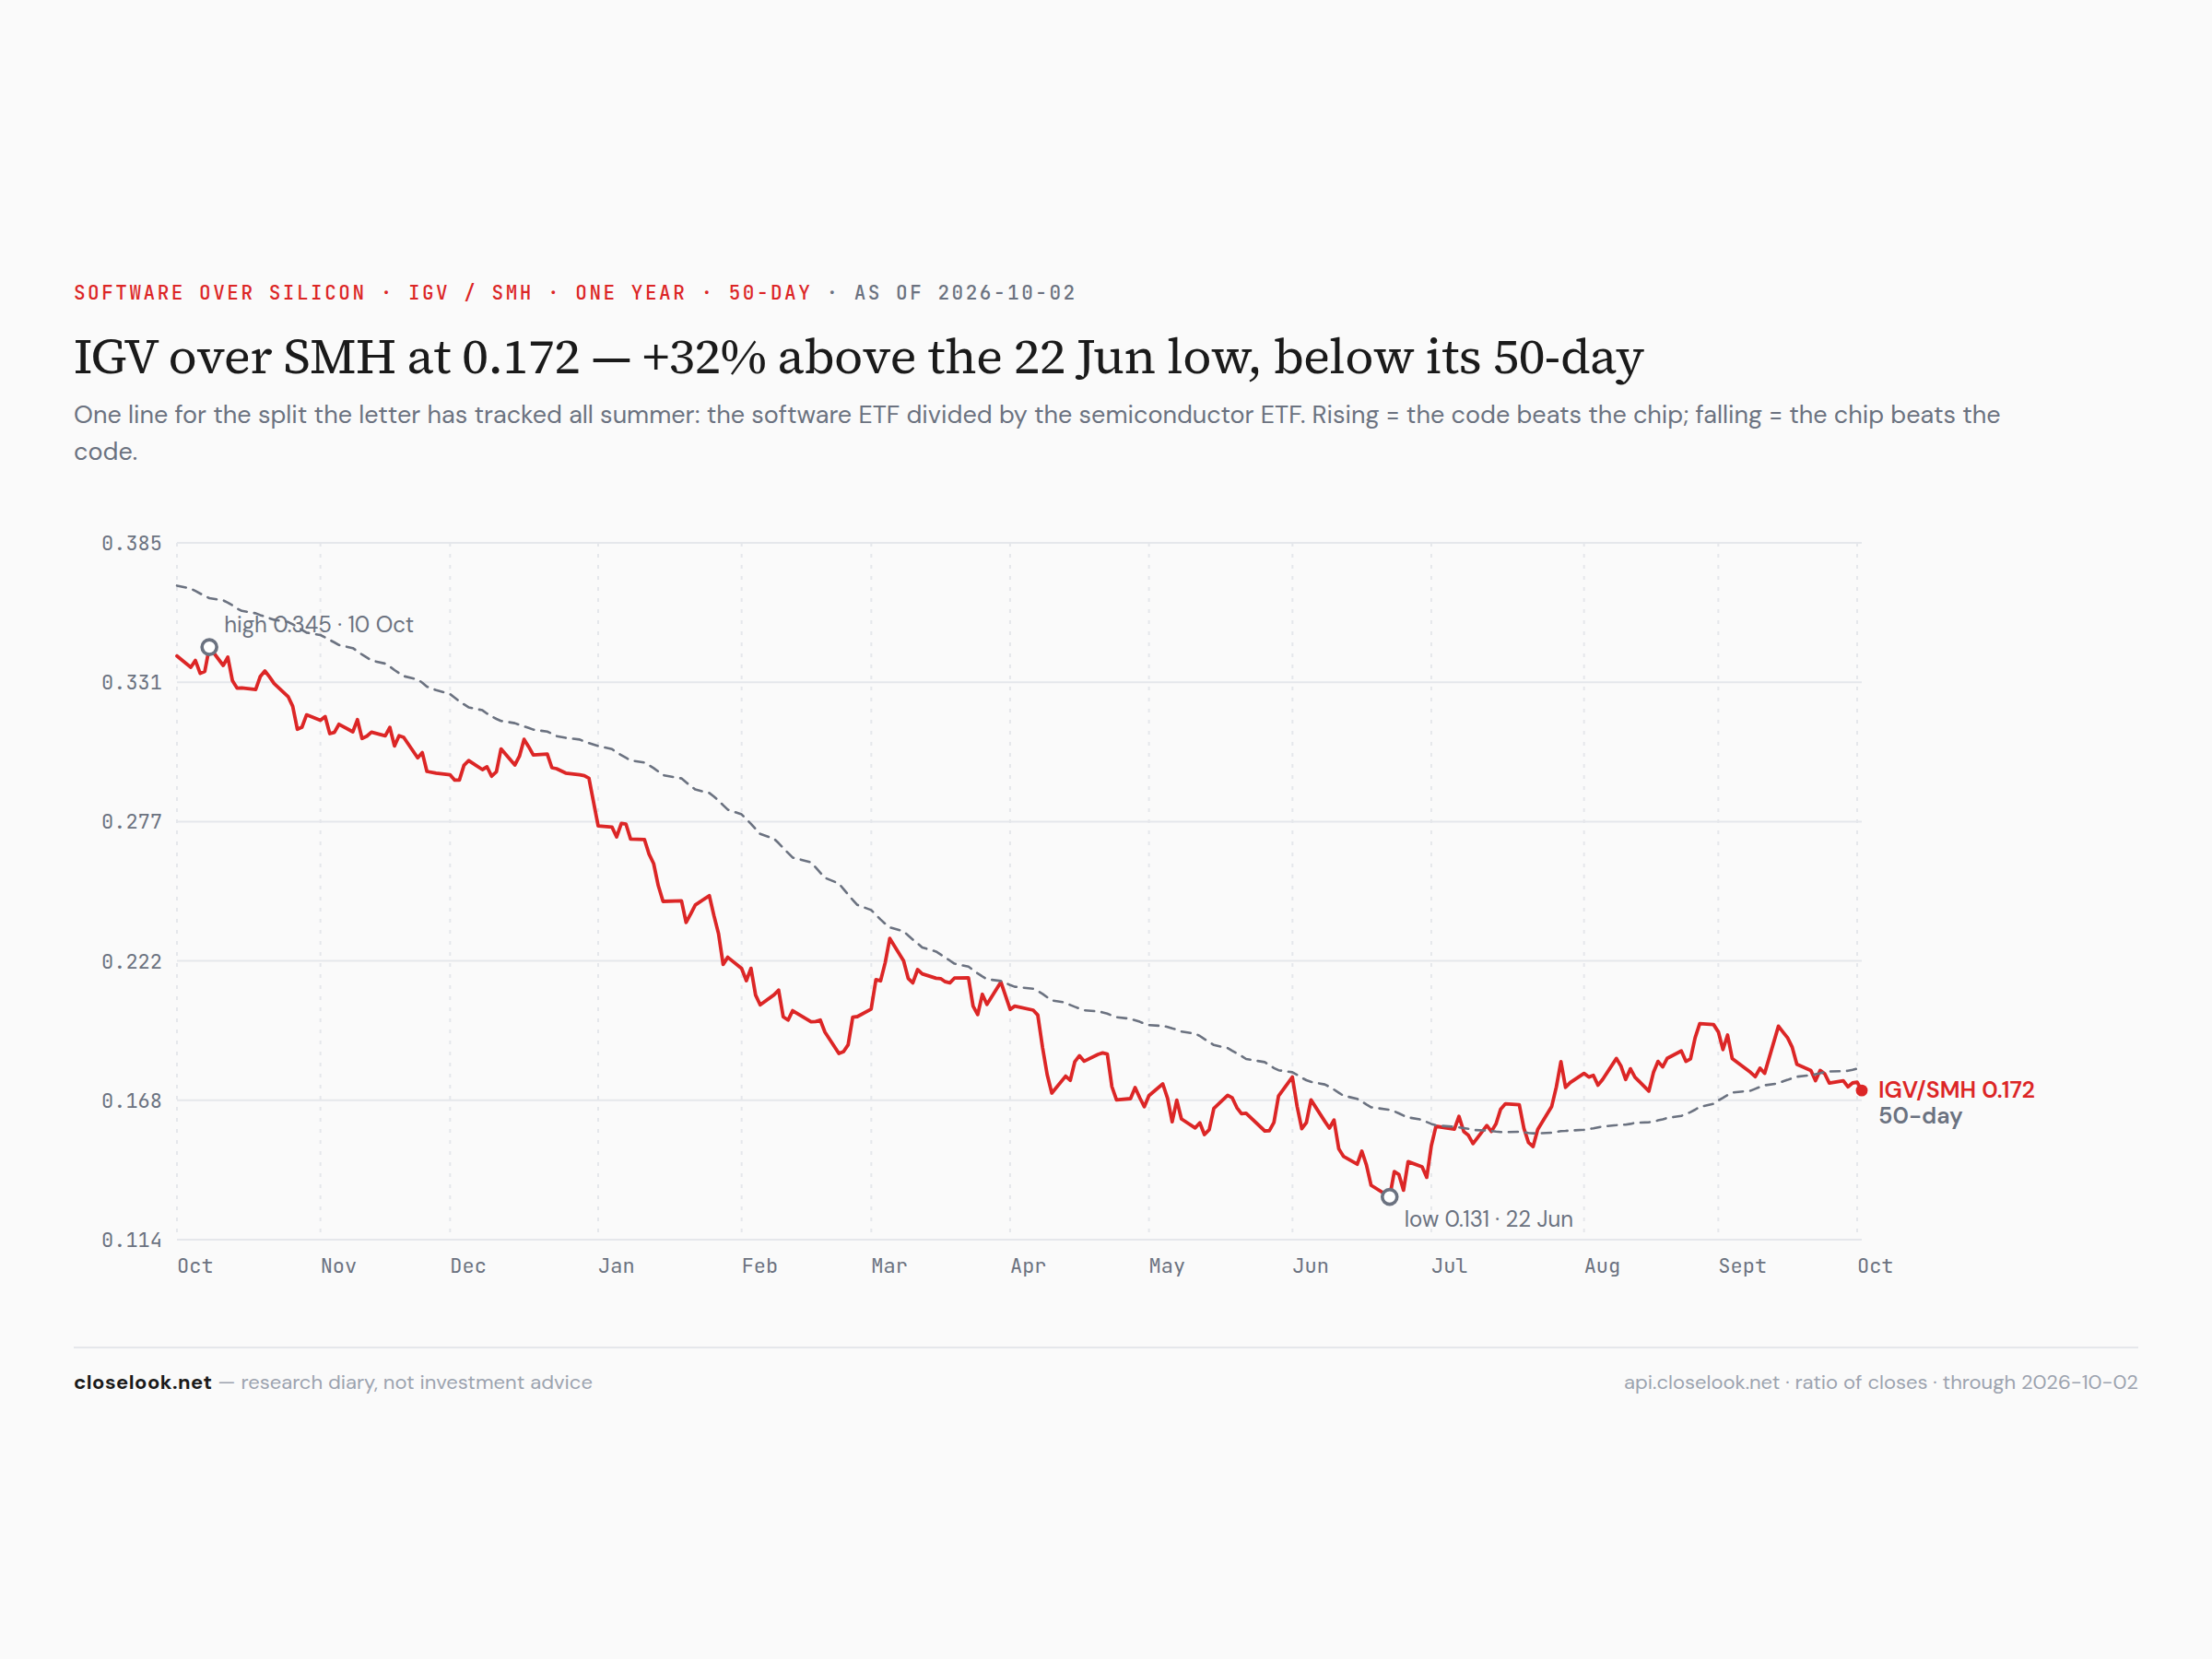
The non-tech growth focal areas — the calendar read, revised a sixth time. Last week this letter carried health care into a second green week. This week health care fell 2.65% in the US and 2.91% globally, the worst sector on both boards, and leaves the list; energy rose again (+1.26% US, +0.78% global); security rose 3.7%. The honest reading has not changed: the sort is by news, and a weekly letter naming a sector is mostly naming last week's news. The one area that has stayed on the list through every revision is security. Probability, not prophecy.
Next week's docket. Monday: mainland China still shut for Golden Week, Seoul and Tokyo trading the Nasdaq's record. Through the week: this diary's Micron, Accenture and Nike windows close (the US letter carries the scores). Thursday–Friday: TSMC's September sales. The week after: ASML on the 14th and TSMC's quarter on the 15th open the reporting season for the AI corridor. The ten-year opens at 5.28%, the thirty-year at 5.61%, the dollar at its high, the euro at its low, the long bond at its low, the Nasdaq 100 at its record.
5 · The ETF Portfolio — Global ETFs
Global ETFs — 16 positions · unrealized +12.1% · benchmark Nasdaq-100 · snapshot Oct 6, 2026
| # | Symbol | Name | Weight | Unreal. |
|---|---|---|---|---|
| 1 | VEU | — | 10.8% | +5.6% |
| 2 | SMHX | — | 9.3% | +58.6% |
| 3 | QQQM | — | 9.0% | +5.1% |
| 4 | XLK | — | 8.7% | +9.1% |
| 5 | QTOP | — | 6.9% | +37.7% |
| 6 | EWT | — | 6.7% | +17.9% |
| 7 | SPMO | — | 6.6% | -2.8% |
| 8 | TOPT | — | 6.2% | +38.3% |
| 9 | IBIT | — | 5.5% | +31.2% |
| 10 | ILF | — | 5.5% | +7.3% |
| 11 | INDA | — | 5.3% | -9.8% |
| 12 | EWY | — | 5.3% | +0.9% |
| 13 | EPOL | — | 5.1% | +10.3% |
| 14 | FLSW | — | 4.7% | -6.2% |
| 15 | GLD | — | 4.4% | -3.6% |
+ 1 more position · full per-position cost basis & P&L is C+ subscriber-only.
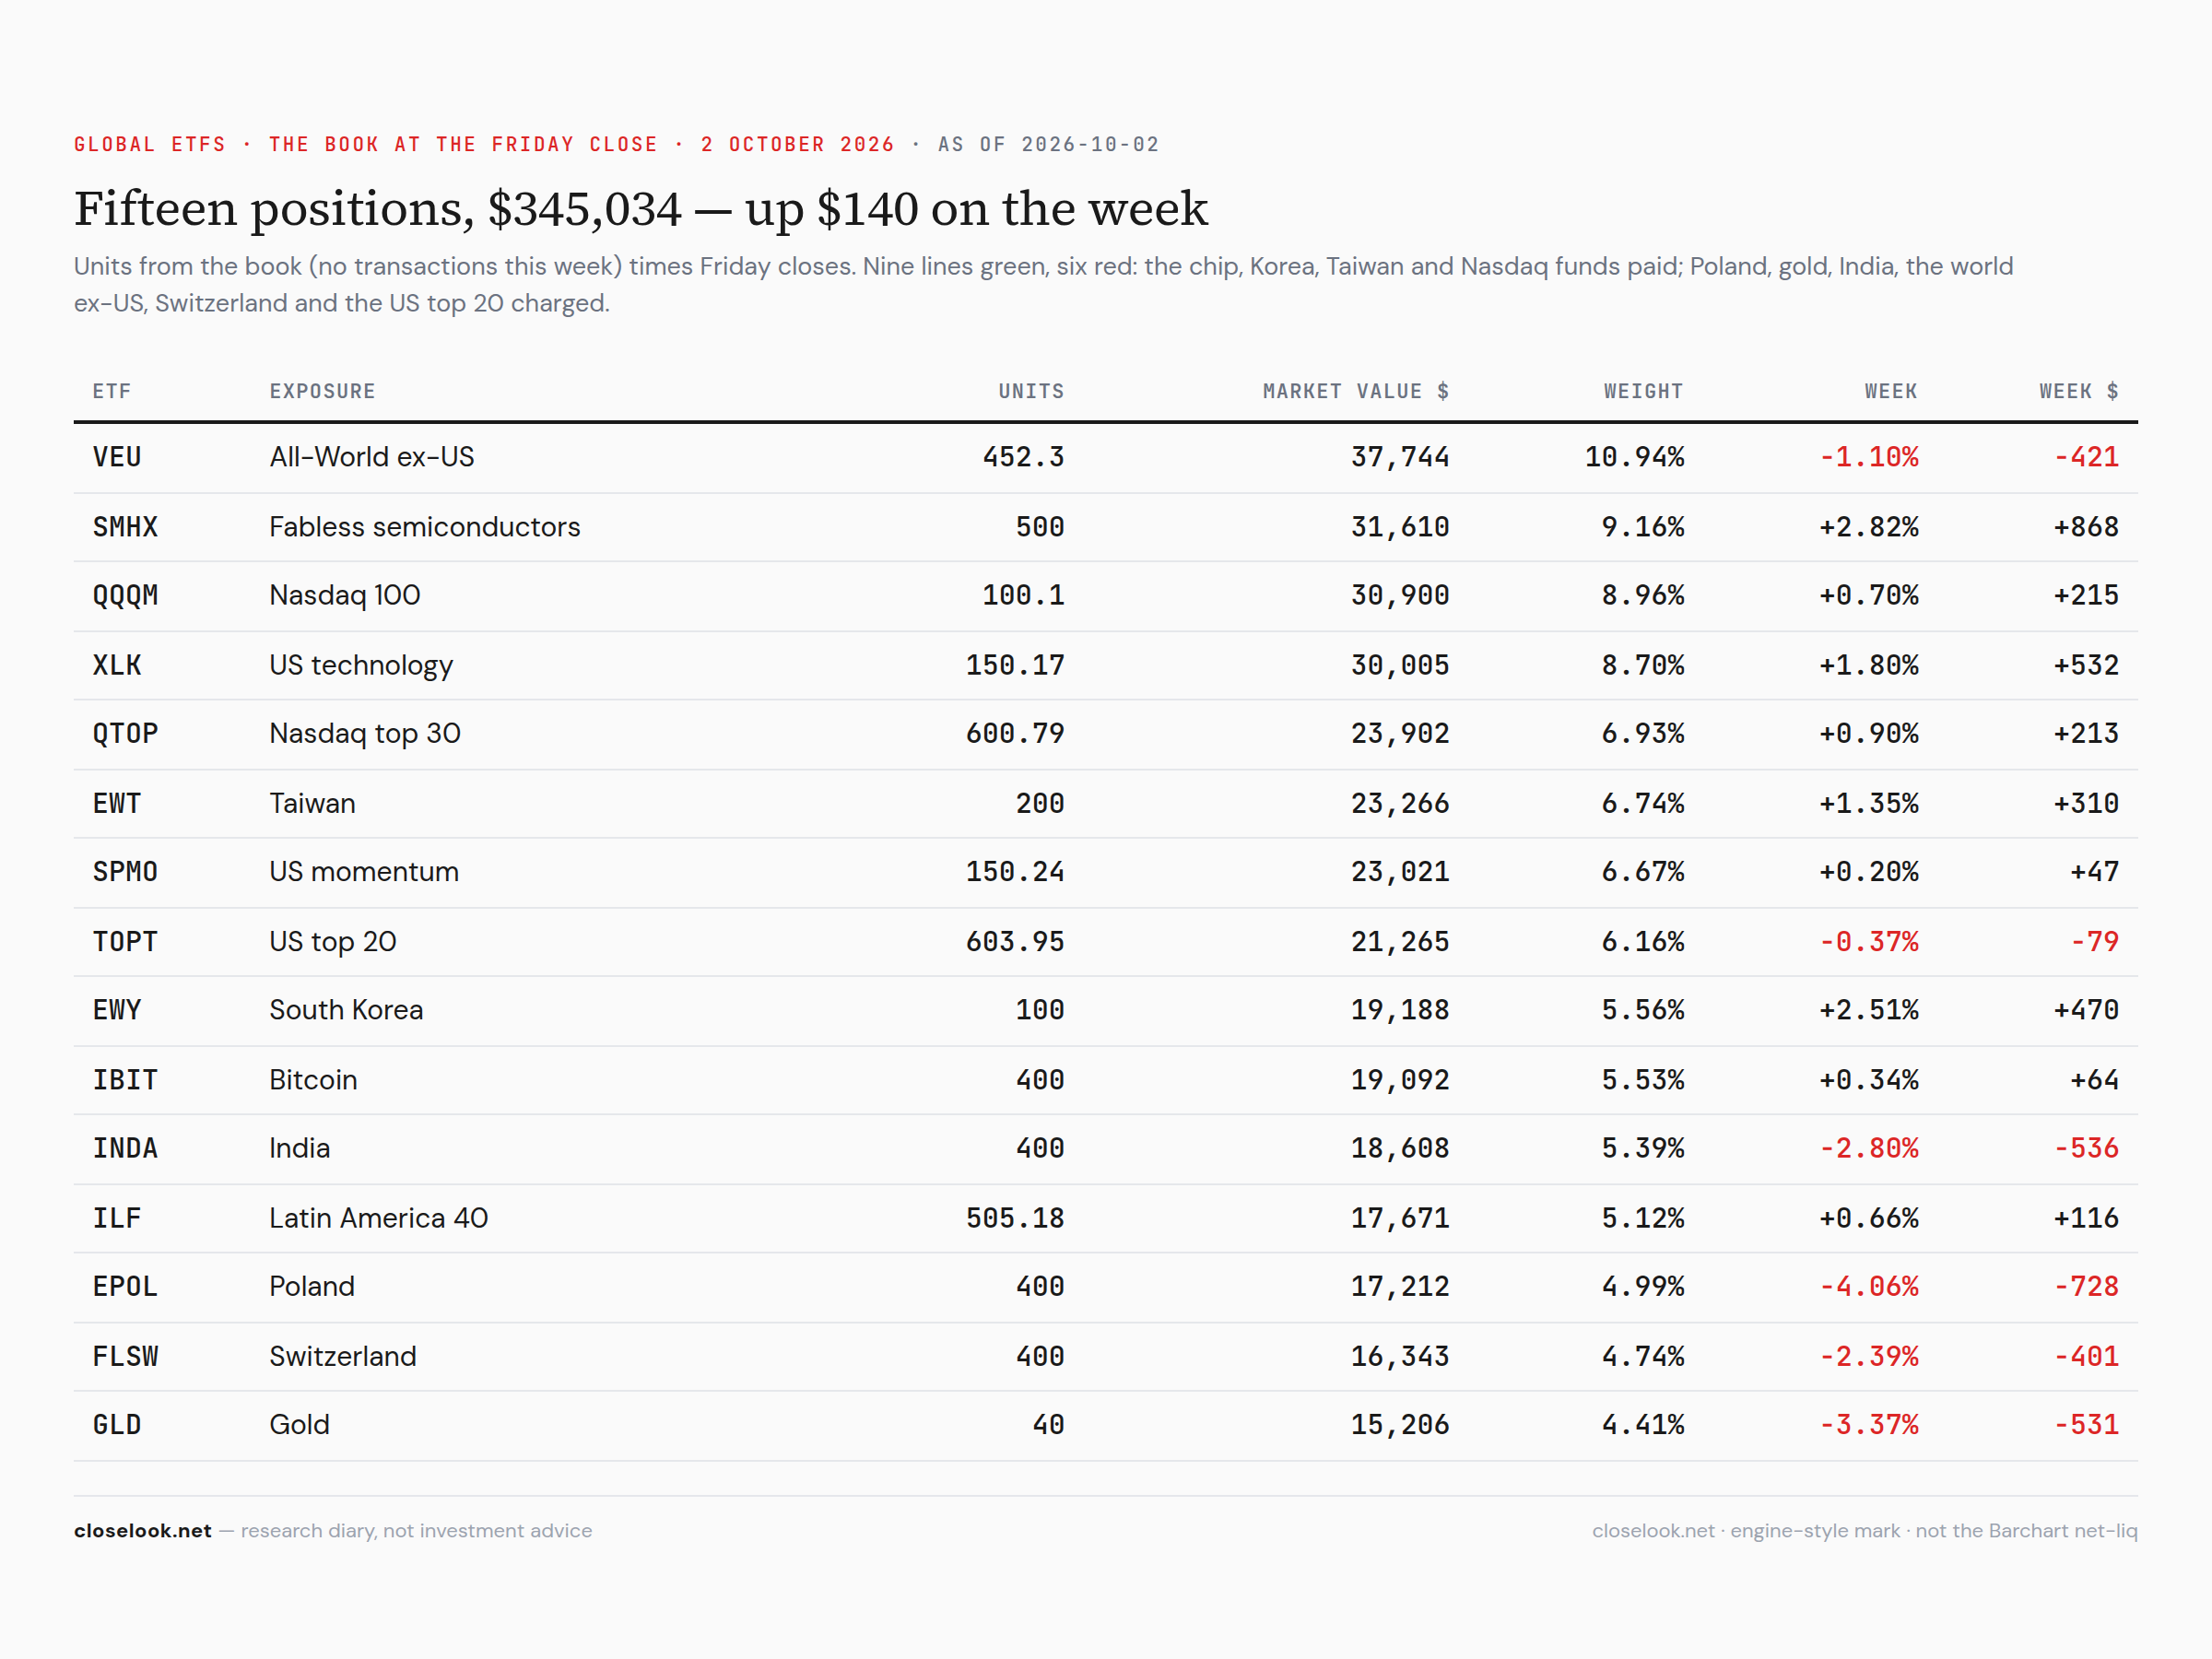
What we did this week: nothing — an eleventh consecutive week without a transaction, and no dividends inside the week (the SPMO and QQQM reinvestments in this week's file are dated last Friday and were in last Saturday's entry). The July rebuild remains the decision. Saturday's Pulse carries the equity books' ledger — AI Build-Out sold its Western Digital line a day before a 10% drop and doubled SanDisk, and Tokyo Electron split five for one — and this book, which owns the corridor, the hedges and the world through its wrappers, had a flat week.
The book, marked — the $140 week. The fifteen-position book closed Friday at a market value of $345,034 — up $140, or 0.04%, from $344,894 at last Friday's closes on this week's units. Unrealized gains +10.59% on cost, from +10.53%; realized gains unchanged at $42,599; a headline return of +30.3% on the $250,000 deposited. Nine of fifteen lines green, six red.
What the week paid it — and what it charged. The map, line by line. The fabless chip fund +2.82% (+$868, the book's best), XLK +1.80% (+$532), Korea +2.51% (+$470), Taiwan +1.35% (+$310), QQQM +$215, the Nasdaq top-30 line +$213, Latin America +$116, the bitcoin fund +$64, US momentum +$47. The charges: Poland −4.06% (−$728, the book's worst), India −2.80% (−$536), gold −3.37% (−$531), VEU −1.10% (−$421), Switzerland −2.39% (−$401), the US top-20 line −$79. The book is the map in miniature: the corridor and America's tech paid, Europe, India and the metal charged, and the two netted to zero.
What we plan to do: nothing on Monday — with one line under review. The book's European exposure is Poland and Switzerland, no euro-area core. Poland is one of the two exceptions this letter's map keeps; Switzerland is the line the map no longer supports after this week's change of view. The watch-items are the levels above — VEU against 84.30 from below, Korea against its new 190.11 floor, the bitcoin fund against 49.01, gold against 391.74 from below, TSMC's number for Taiwan and the fabless fund. The book is 34% in the fabless chip fund, XLK, QQQM and the Nasdaq top-30 line, 12% in Korea and Taiwan, and 11% in the world ex-US.
The four tradable books, open for inspection. Alongside the reference portfolios documented on this site, the four Closelooknet-companion wikifolios — the tactical stock book, the AI-cycle thesis book, the ETF distribution core, and the non-tech growth compounder — publish their own ledgers on the wikifolio platform: every transaction in each of the four is visible there, trade by trade, at Closelooknet, AI Cycle 2030, ETF Generation and The Compound. How the vehicles work, and who the issuer is, lives on the Trade the Look page. Nothing here is a recommendation; this is a research diary.
6 · What May Go Wrong
One: TSMC misses. The quarter's map rests on one supply chain, and its sales are reported next week. A soft September — or a cautious word on the fourth quarter on the 15th — would hit Taipei, Seoul and the US chip funds on the same day, and the three-speed map would lose its fastest lane first. The falsifier is stated: EWT back under its September range and EWY back under 190.11 on a weekly close.
Two: the long end stops being a bond story. Five new lows in five sessions on the long-bond fund, in a week of soft inflation and a weak jobs report, say the long end is trading on supply and credit. So far the equities with growth have absorbed it. If the thirty-year keeps climbing toward 6% while growth slows — the payrolls number is the first hint — the discount rate starts to win against the earnings, and the records on the Nasdaq become the place the selling begins. A week in which the Nasdaq 100 falls and the long bond makes another low is that week.
Three: the dollar turns. The stay-home case has been helped all quarter by a firmer dollar. A dollar that rolls over — on a run of weak US data, or on a policy push for a weaker currency — would hand the year back to the rest of the world in a few weeks, and Europe's currency cost would turn into a currency gain. The dollar fund back under its 50-day average on a weekly close is the first sign.
Four: concentration. One global sector at a record, nine of eleven red; one US sector carrying the S&P; the applications index down while the builder doubles. A market this narrow can go on longer than anyone expects, and it can also turn in a day when the one leg that carries it stumbles. The equal-weight S&P's −0.65% in a record week for the Nasdaq is the number to watch.
Five: France becomes Europe's problem. A spread that moved from 113 to 138 basis points in a week, with money leaving the OAT for the Bund, is the start of a test, not the end of one. If it spreads to Italy and the other long ends, it reaches the banks that hold them — and global financials, already a fourth week under their line, are where it would show outside Europe. Avoiding Europe protects a portfolio from the epicentre; it does not protect it from the second-round effects on global banks and on the euro.
7 · Knowledge Corner
Why a strong dollar helps the American investor and costs the European one twice. An ETF that holds European shares and trades in dollars moves with two things: the shares in their home currency, and the euro against the dollar. This week the Euro Stoxx 50 fell 1.0% in euros; the dollar-listed Europe fund fell 2.5% — because the euro also fell 1.2%. The euro-hedged fund, which strips the currency out, fell 0.9%. The difference between the hedged and the unhedged fund is the currency, and this year it has worked one way: the euro is down 4.2% against the dollar since January, so a dollar investor in Europe has lost about four points on the translation before the market has done anything. A European investor at home sees the same thing from the other side: the euro buys fewer dollars, and the assets that lead the world — America's tech, Asia's chips — are priced in dollars or in currencies that track it. The strong dollar is not a separate story from the three speeds; it is the price tag on them. Money that wants the growth has to buy the currency it is listed in, and that buying is part of why the currency is strong. When the growth moves elsewhere, the currency usually goes with it — which is why risk three above is the one that would change this letter's map fastest.
8 · Final Words
Three speeds. America's technology made records — the Nasdaq 100, the US tech sector, global tech through its June high. Asia's chip markets went with it — Taiwan to a record, Korea through its cap, the AI half of Japan up three percent while the rest of Japan fell. Mainland Europe slid, every market on the board, and Switzerland and Britain slid with it; India closed at its lowest in a year. The dollar made its high of the year and the euro its low. The long bond made a new low every day, and gold lost its floor.
The world ex-US index lost its line again, and its lead over America for the year is down to six tenths of a point. America won a fourth week. September's base case, a five-percent consolidation, was mostly delivered on the world index — and did not happen to America's tech at all.
This letter's map for the fourth quarter follows from it: stay home, because the AI trade lives in America and in Asia's corridor; avoid mainland Europe, Switzerland and Britain, with Greece and Poland the exceptions; expect a positive quarter for the US, and buy the dips that the next two weeks of uncertainty may offer before the reporting season. TSMC's September sales are the first test of that map, next week.
Price is the only truth. This week it said: the money goes where the growth is, and it buys the currency on the way. TSMC's number, the long bond against 74, the dollar fund against its high and the weekly closes — 84.30 on the world index, 190.11 on Korea, 83,000 on the coin, 391.74 on gold — will say how long it keeps saying that.